
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Tele2 Stock And EU Telecom Networks Gain Attention As Spectrum Rules Shift
EU telecom incumbents suddenly sit in the crosshairs of a bigger story, as Brussels debates spectrum rules, US regulators bristle, and talk of technological sovereignty moves from slogan to policy. That clash could reshape who controls future wireless, satellite, and cloud pipes. This article walks through three EU telecom stocks that appear closely tied to this news and explains how their exposure may be relevant for your portfolio decisions.
The three telecoms discussed below are only a sample, and the full screen surfaced 17 more EU incumbents and spectrum-heavy operators with equally compelling stories that do not fit into one article. To see the wider field, identify patterns, and analyze potential high-conviction ideas, head straight to the EU telecom incumbents and spectrum-rich network operators screener.
Tele2 (OM:TEL2 B)
Tele2 is one of the clearest examples in this screen of a regional operator built on owned spectrum and physical networks. This is exactly where EU policy debate around sovereignty and satellite access is now focusing.
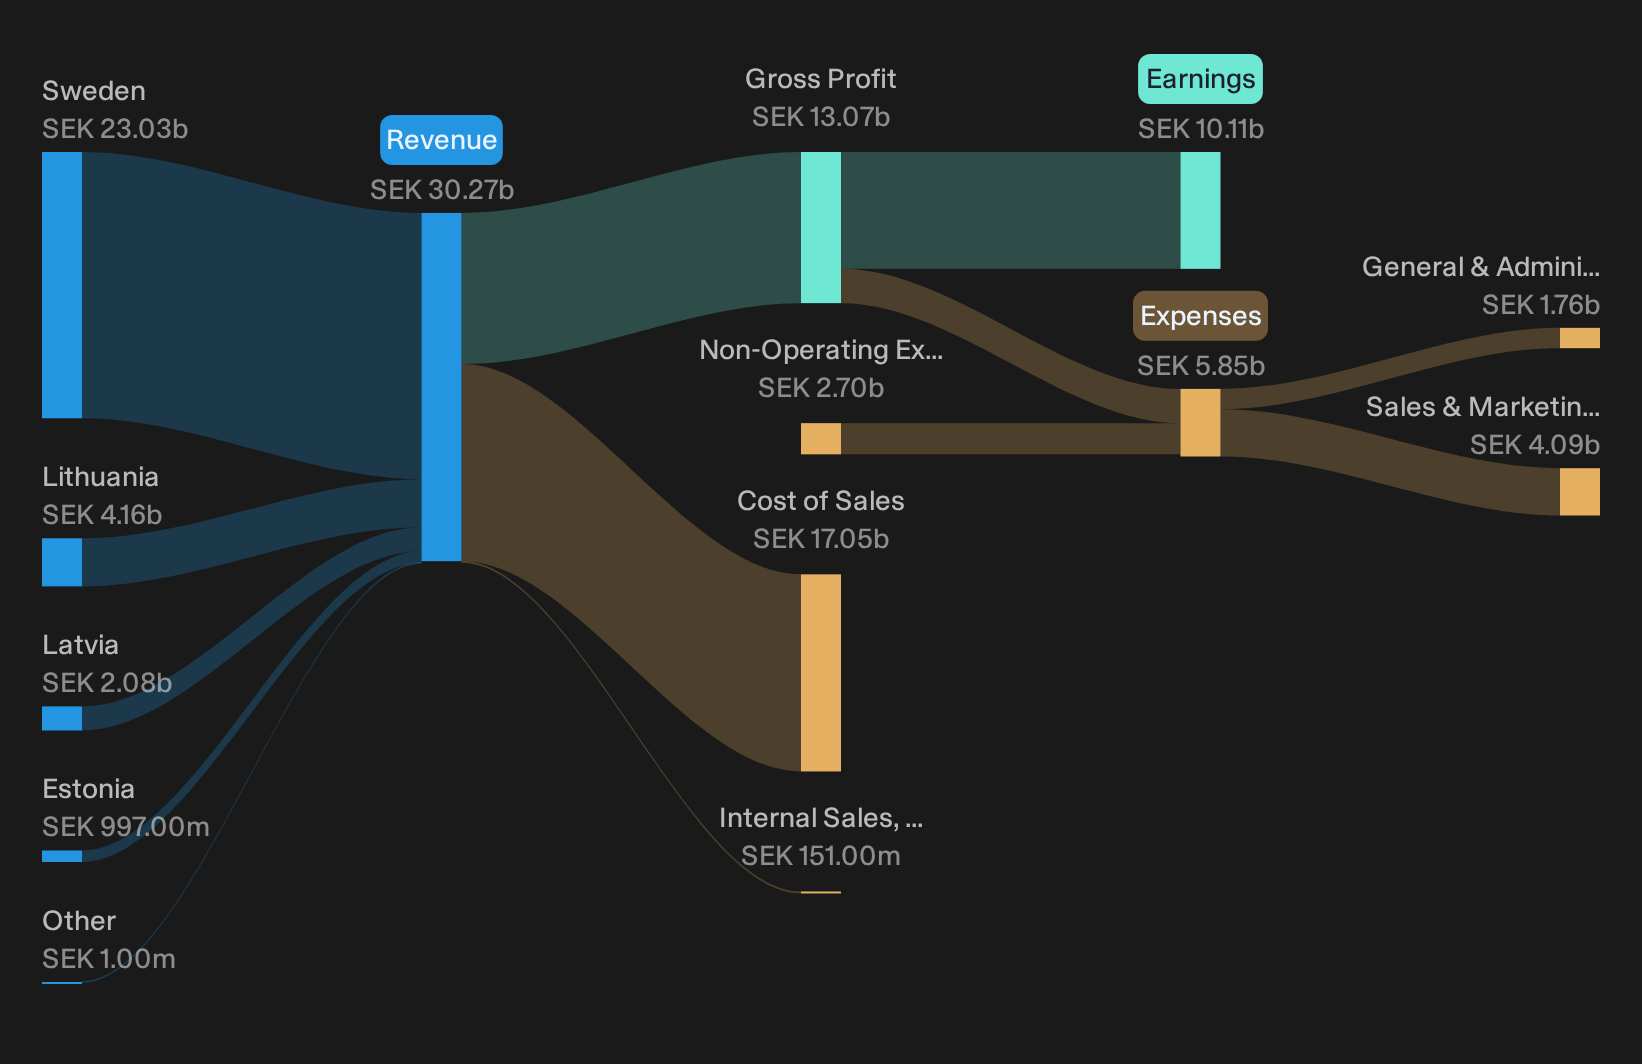
Tele2 runs fixed and mobile networks plus entertainment and enterprise services across Sweden and the Baltics, with revenue concentrated in Sweden at SEK23.0b, followed by Lithuania at SEK4.2b, Latvia at SEK2.1b and Estonia at SEK1.0b, and a market value around SEK111.3b.
"Ongoing 5G investments and rollout position Tele2 to capture a growing share of value-added and premium services, both in consumer (enhanced mobile and broadband) and business offerings (network slicing, high-capacity solutions), with medium-term expectations for improved ARPU and earnings as network usage intensifies."
What happens to those expectations if a single unseen pressure on cash generation and balance sheet flexibility moves the margin story off script?
If that pressure point worries you, read the full narrative for Tele2 to see whether cash strain, spectrum policy and 5G rollout are quietly decoupling for Tele2.
Telia Company (OM:TELIA)
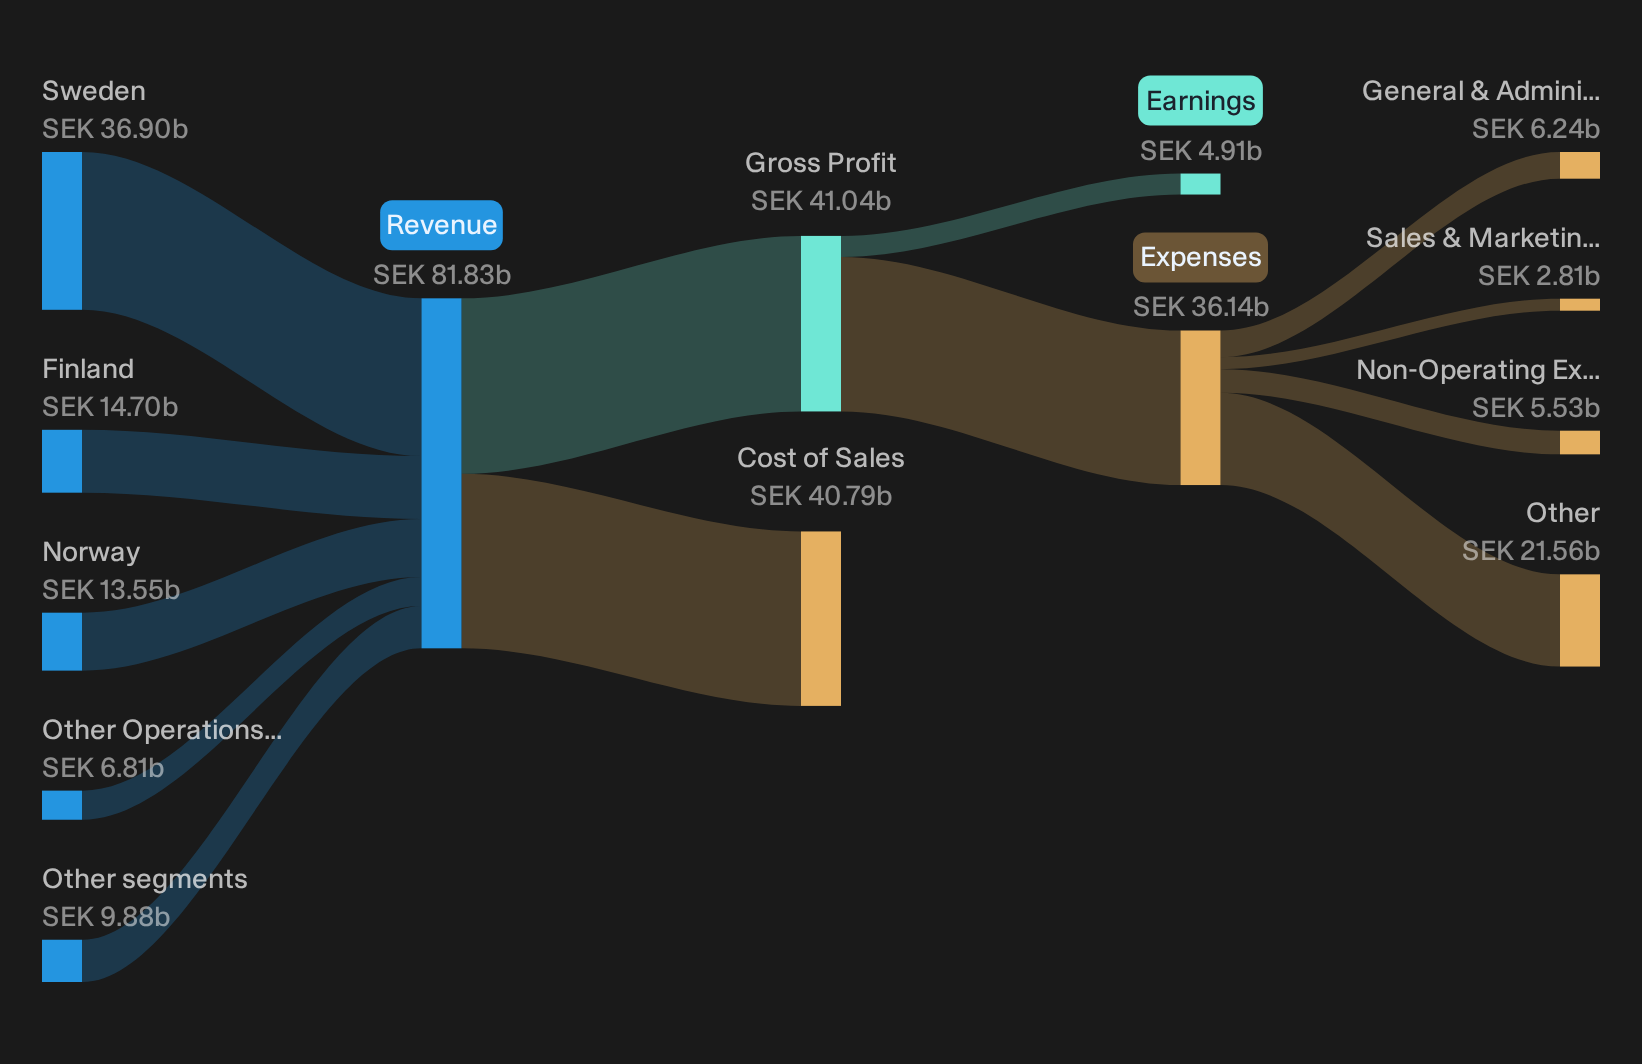
Telia Company is one of the purest plays on the screener theme, with owned mobile spectrum, fibre and fixed networks across the Nordics and Baltics giving it real weight in Europe’s push for homegrown connectivity infrastructure.
"Advancing convergence across connectivity, TV, media and cloud services remains a focus, with more than 1 million converged Swedish households and rising convergence ratios supporting higher revenue per household, lower churn and healthier EBITDA margins."
What that means for future margins and cash generation depends heavily on how one unresolved cost and funding pressure unfolds.
That cost question is exactly where the Telia story becomes interesting, so read the full narrative for Telia Company to see whether convergence is accelerating or masking deeper funding trade offs.
Orange Polska (WSE:OPL)
Orange Polska ties directly into the EU telecom incumbents and spectrum-rich operators theme because it controls nationwide fixed and mobile networks. Policymakers increasingly want these networks in local hands rather than dependent on overseas players.
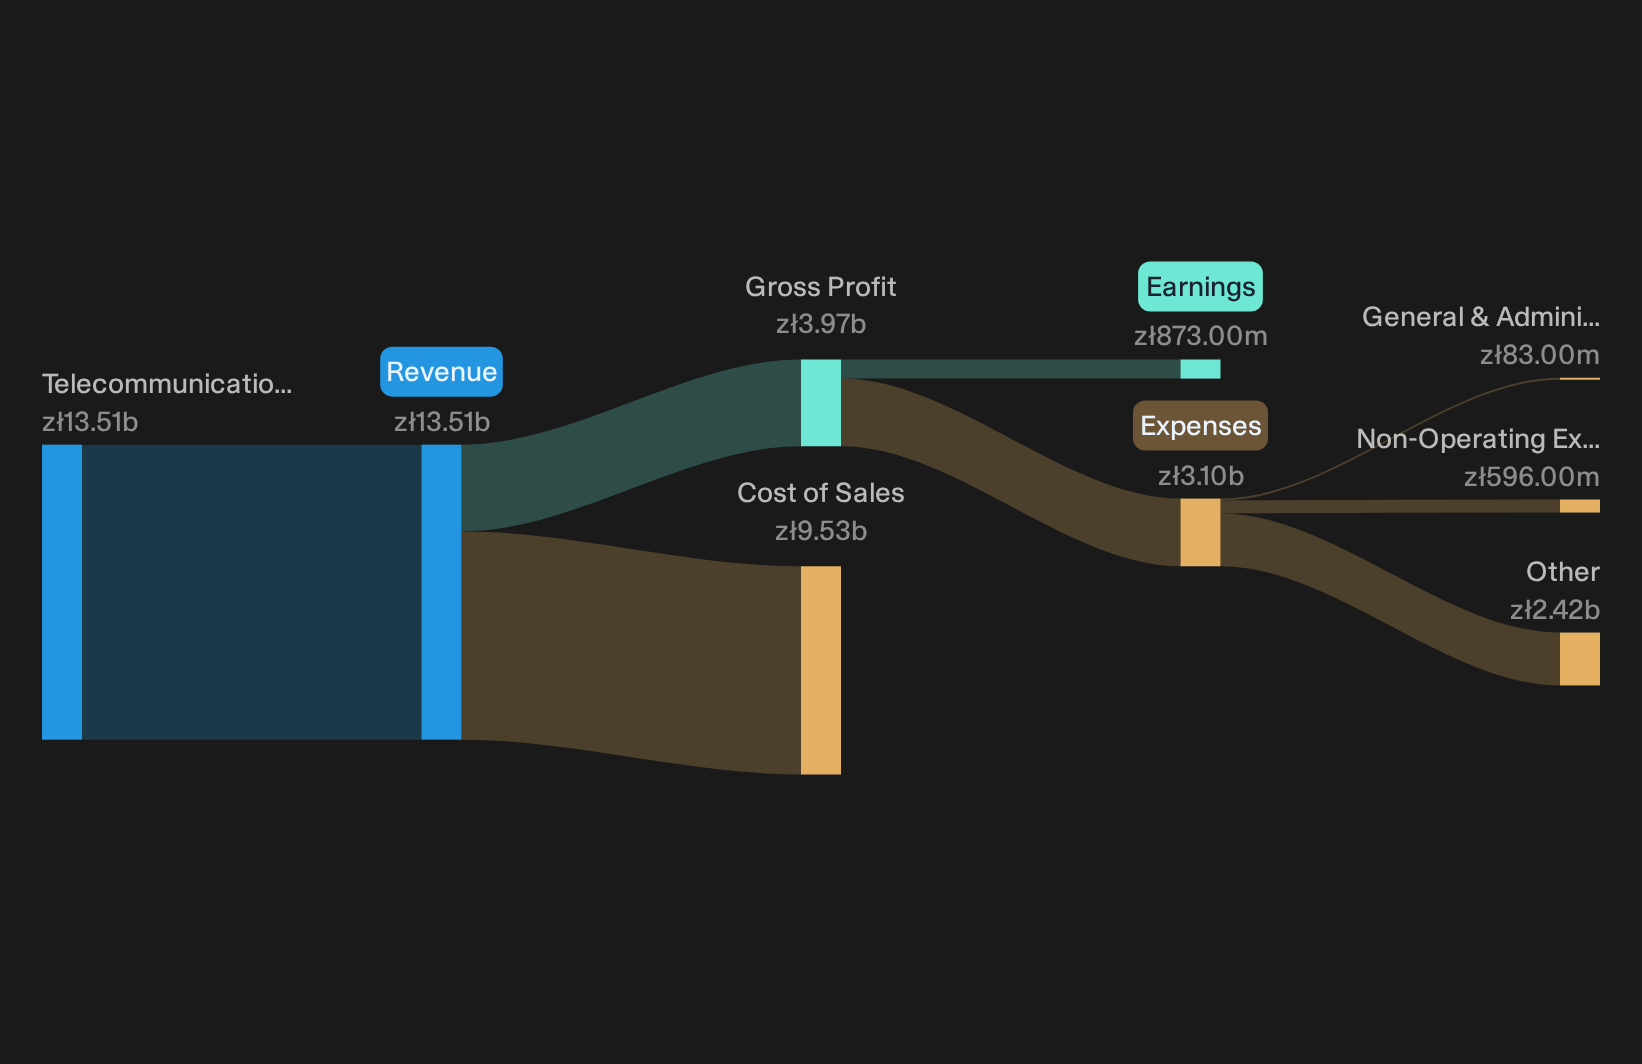
Orange Polska runs mobile, fixed-line, internet, TV and IT services across Poland, generating about PLN13.5b from telecommunications services and carrying a market value near PLN21.3b.
"Completion of fiber rollout in white zones before the end of 2026 and access to an additional 900,000 high speed broadband households through the HFC agreement create scope for Orange Polska to shift mix toward higher value broadband and convergence contracts."
What happens to Orange Polska’s margin story if a single unresolved funding and payout trade off tightens the room to keep investing at this pace?
That trade off is exactly where Orange Polska gets interesting, so read the full narrative for Orange Polska to see whether funding choices are quietly accelerating or stalling the fibre story.
Seeking Alternatives Before Momentum Flies
Fresh ideas move first. By the time a theme hits headlines, early opportunities can be slipping away. Scan under the radar for now, act now.
- Spot quieter trends before they break out by scanning the 614 high quality undiscovered gems curated to surface quality businesses still flying below most investors' screens.
- Target steadier portfolio anchors by reviewing the list of solid balance sheet and fundamentals (204 results) that highlights companies with cleaner finances while this information edge still matters.
- Ride structural demand shifts by checking the 42 power grid technology and infrastructure stocks focused on operators tied to grid upgrades before momentum gets fully caught in the price.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com