
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did First 6G Field Call Just Shift Verizon's (VZ) Investment Narrative?
- Verizon Communications and Ericsson recently completed what they describe as the first pre-standard 6G outdoor field call in the 7 GHz band from a live Verizon commercial site in Concord, California, using a 400 MHz carrier to test real world coverage, latency and signal behavior from outside to inside buildings.
- Alongside this 6G field work, Verizon is leaning on richer perks such as free Google AI Pro access and new entertainment benefits to support customer loyalty after recent price increases. This speaks directly to how the business is balancing heavy network investment with retention and pricing power.
- We will now look at how Verizon Communications' first outdoor pre-standard 6G field call could influence the broader investment narrative.
Verizon Communications Investment Narrative Recap
To own Verizon Communications you need to believe its heavy network spend on 5G, broadband and now early 6G testing can support steady service revenue and cash generation while customer churn stays under control. The Concord field call looks more like long term R&D than a near term catalyst and does not meaningfully change that near term thesis.
The bigger swing factor still sits in execution on broadband expansion, cost cuts and pricing after recent increases, while competitive pressure and high debt remain the clearest risks. Fixed wireless growth, spectrum capacity and customer loyalty offers matter far more to the next year of results than this 6G milestone.
The 6G field call aligns most clearly with Verizon Communications fixed wireless and broadband ambitions that analysts already view as a key driver for future service revenue and ARPU. Lab work moving into outdoor and outside to inside tests in the 7 GHz band helps management understand real world coverage, capacity and latency limits for future high frequency deployments.
For catalysts that investors watch now, the partnership with SKYBOXE to resell Verizon Business 5G fixed wireless data plans appears more directly tied to near term broadband additions and utilization of existing 5G assets. Execution risk sits in using that extra demand without crimping mobile performance or pushing capital intensity higher than cash generation can comfortably fund.
Verizon Communications' narrative projects US$147.7b revenue and US$23.0b earnings by 2029. This implies 2.1% yearly revenue growth and an earnings increase of about US$6.8b from US$16.2b today.
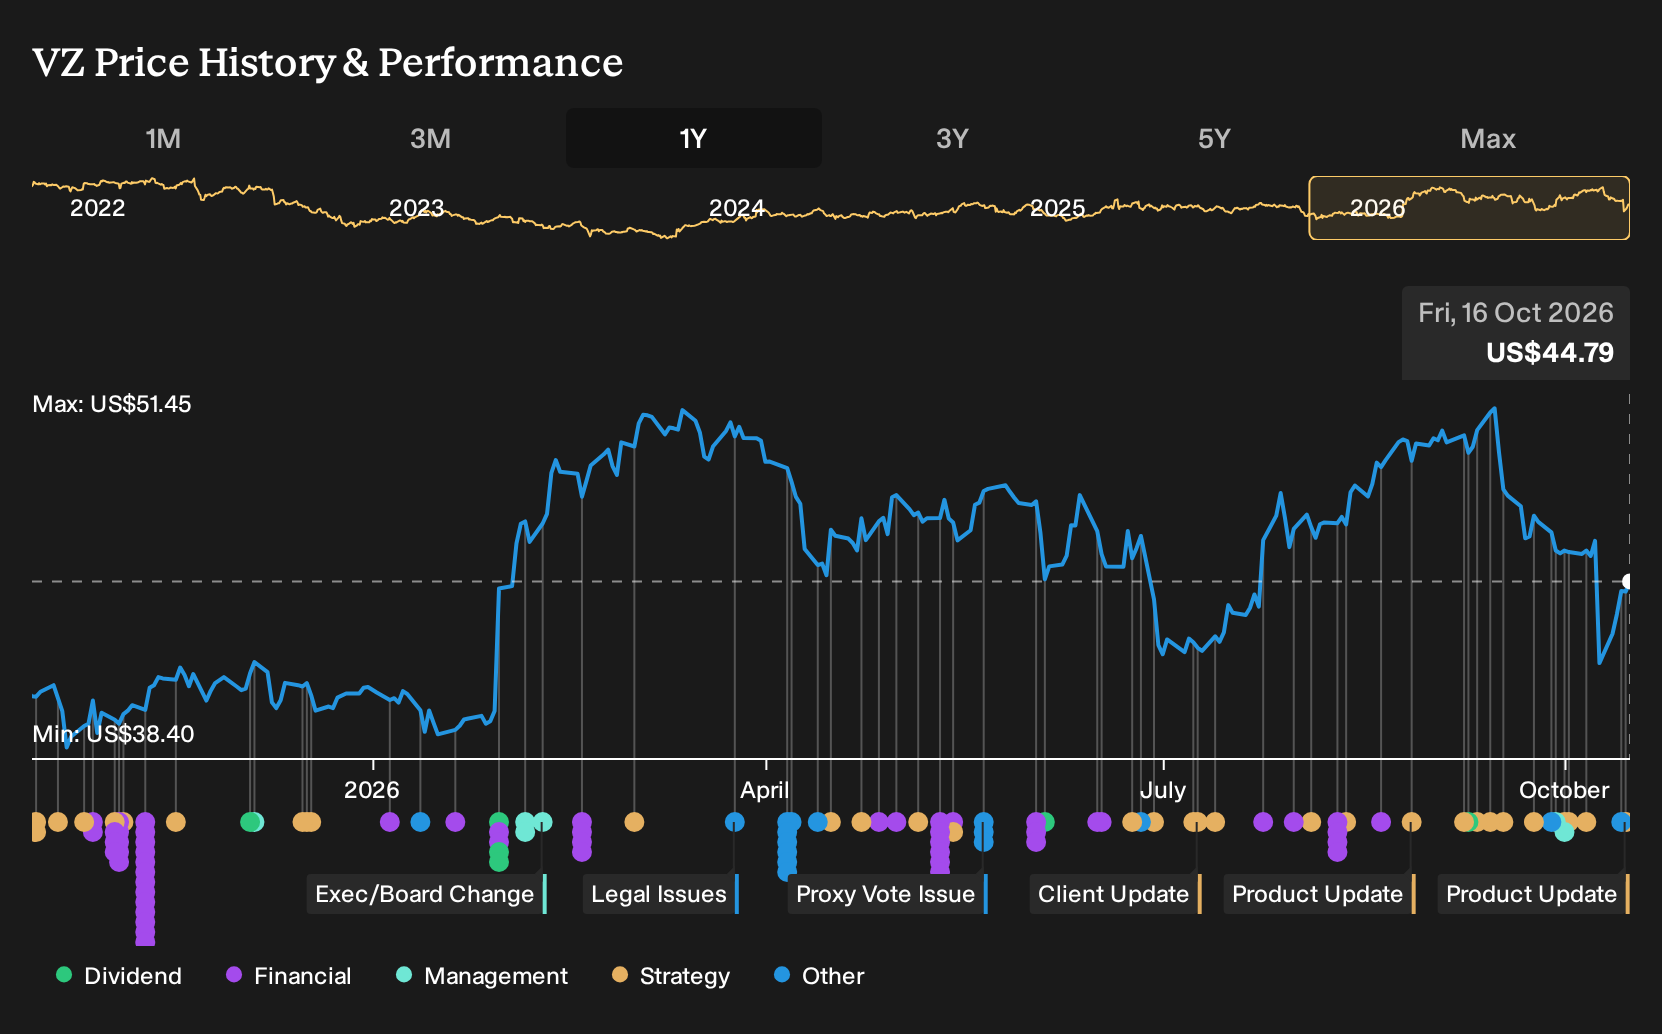
Uncover how Verizon Communications' fair value indicates a 15% potential upside to its current price before that discount closes for Verizon Communications.
Exploring Other Perspectives
One alternate view focuses on Verizon Communications capital intensity rather than 6G upside. The most cautious analysts were penciling in revenue of about US$143.8b and earnings of roughly US$21.8b by 2029, with only 1.2% yearly top line growth. Those expectations reflect concern that heavy fiber and fixed wireless spending caps earnings, although the fresh 6G field call could eventually nudge that story in a different direction.
Explore 6 other Verizon Communications fair value estimates, including one that suggests it could be worth just $50.50.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Verizon Communications research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Verizon Communications. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Verizon Communications' overall financial health at a glance.
Looking For More Investment Ideas Beyond Verizon Communications?
If you want to stress test your view on Verizon Communications, it helps to weigh it against a broader watchlist. The Simply Wall St Screener lets you move from a single ticker to a full bench of potential candidates that share similar qualities in balance sheet strength, income potential or valuation.
- If capital preservation matters most to you, focus on companies that pair sturdy finances with lower risk profiles by reviewing the 32 resilient stocks with low risk scores.
- If income is your priority, scan for businesses targeting higher yields and consistent payouts through the 8 dividend fortresses.
- If you are hunting for mispriced opportunities with room for a re rating, line up potential ideas using the 33 high quality undervalued stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com