
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Kirby (KEX) Made A Must Own List, Is The Stock Still Cheap?
Kirby (KEX) moved onto more investors’ watchlists after Roundhill Investments strategist Drew Pettit unexpectedly included the barge operator among eight “must own” stocks for the rest of 2026.
Kirby’s shares trade at about $136, with the 1-year total shareholder return of 59.46% and 5-year total shareholder return of 140.11% pointing to strong longer term momentum, even as the 90-day share price return declined 5.60%, which may suggest some cooling enthusiasm after a strong run.
Explore a curated set of resilient, cash-generating businesses with hard assets similar to Kirby by using the 32 resilient stocks with low risk scores, which is designed to highlight stronger balance sheets and lower risk profiles.
Bulls see Kirby as a durable cash engine that AI hype cannot touch. Bears look at the recent pullback and worry the good news is priced in. Which story does the valuation support next?
Most Popular Narrative: 18% Undervalued
Kirby closed at $136.43, while the most followed narrative pegs fair value around $166.17 using a 7.57% discount rate and detailed cash flow assumptions. That gap frames the current debate over whether the recent pullback is a reset or an entry point for investors who buy the barge and power story.
Disciplined capital allocation that pairs focused marine and power generation capacity investments with heavy share repurchases, including over US$400m of free cash flow in 2025, guided 2026 operating cash flow of US$575m to US$675m, a US$95.8m inland fleet acquisition and completion of a US$952.42m buyback that retired 18.83% of shares, increases the potential for per share earnings and cash flow growth.
See why 12 investors see Kirby as 18% undervalued.
Result: Fair Value of $166.17 (UNDERVALUED)
Still, if Kirby stumbles on oil and gas equipment demand or if medical cost inflation keeps biting into margins, that underappreciated cash engine narrative can flip quickly.
Find out about the key risks to this Kirby narrative.
Another View: Kirby Looks Pricey On Earnings
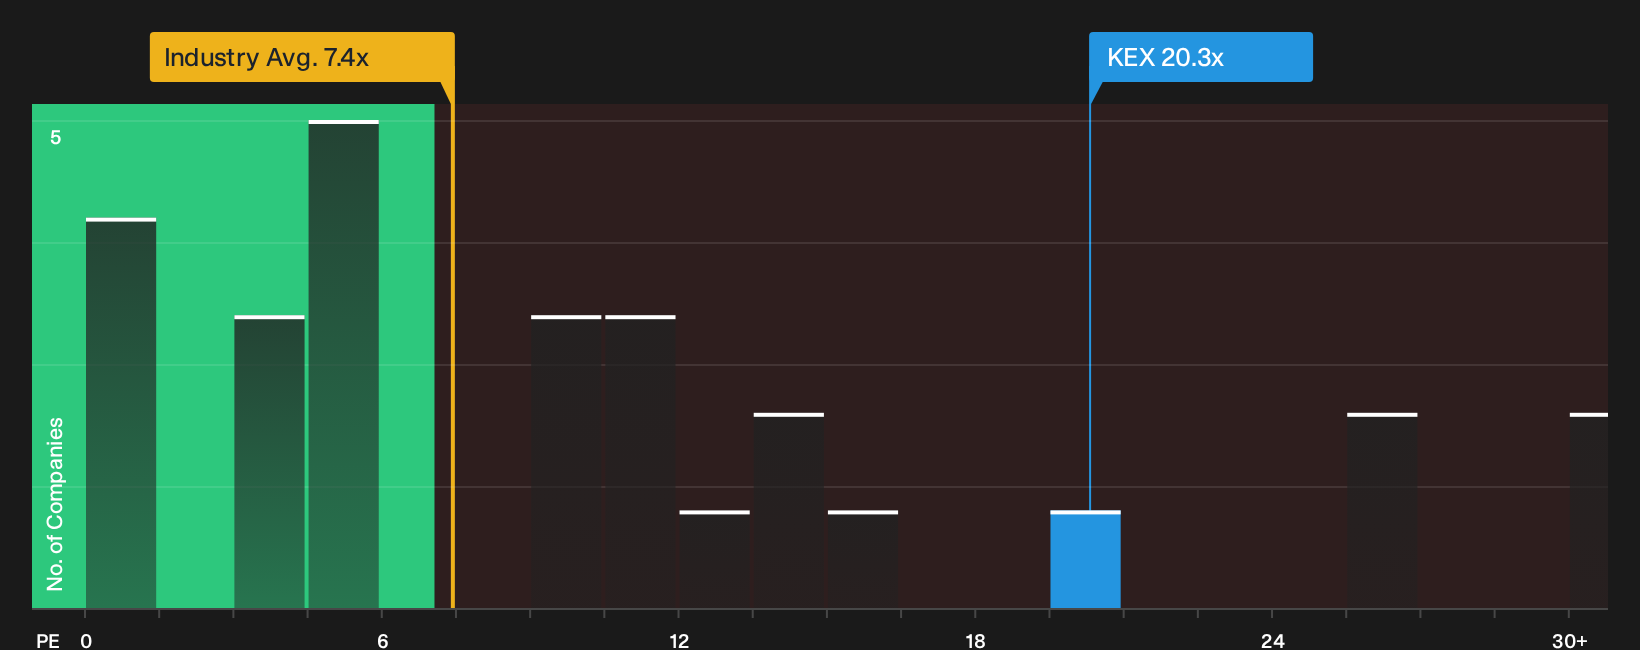
There is a catch. While Kirby screens as 36.1% below the SWS estimate of future cash flow value at $213.45, the current P/E of 20.3x sits well above the fair ratio of 16.5x, the US Shipping industry at 7.4x, and peers at 14.3x, which points to a real valuation risk if expectations cool.
For investors weighing which signal to trust, it helps to see how the earnings based multiples line up against cash flow assumptions in detail, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Visualising how Kirby's current earnings multiple stacks up against both the industry and that fair ratio can also make the trade off clearer at a glance through
Next Steps
If this mix of optimism and caution around Kirby feels familiar, that is the point; markets rarely hand out clear answers. Act quickly and pressure test the bullish case yourself through the 4 key rewards.
Looking for more investment ideas beyond Kirby?
Do not stop your research with Kirby alone. Broaden your opportunity set and use data rich screeners to find stocks that better match your risk, income, and value goals.
- Target undervalued quality by scanning companies with strong cash generation and healthy balance sheets through the 33 high quality undervalued stocks.
- Strengthen your income stream by focusing on established payers that combine payout potential with resilience using the 8 dividend fortresses.
- Prioritise resilience and capital preservation by filtering for businesses with sturdier financial footing through the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com