
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Birchcliff Energy (TSX:BIR) Lifted Production Guidance, Is The Stock Still Cheap?
Fresh guidance on higher production, improved operational efficiency and wider natural gas market access has put Birchcliff Energy (TSX:BIR) into focus as investors reassess the stock’s earnings power and cash generation profile.
The recent production guidance has arrived alongside a 1-month share price return of 8.11% and a 3-month gain of 7.77%, even though the share price is down 8.36% year to date. At the same time, the 1-year total shareholder return of 17.50% and 5-year total shareholder return of 34.04% suggest longer term holders have already seen meaningful rewards as sentiment around Birchcliff Energy’s cash generation story has improved.
Scan 5 high quality undervalued stocks selected to highlight other cash generative energy plays that, like Birchcliff Energy, combine established operations with valuations that have not fully run ahead of recent optimism.
Birchcliff Energy has already rewarded patient holders, yet the recent move remains modest against those returns and fresh production guidance. Is the valuation starting to look full, or does the current pricing still leave meaningful upside?
Price-to-Earnings of 19.5x: Is it justified?
On a simple P/E check, Birchcliff Energy is being valued at 19.5x earnings, which sits below both its direct peers and the broader Canadian oil and gas sector. That gap matters because it hints at how much earnings strength and cash generation the market is willing to pay for at the current CA$6.80 share price.
The P/E ratio compares what investors are paying for each dollar of profit. For a producer like Birchcliff Energy, which is closely tied to commodity prices and capital spending cycles, this metric helps you see how the market weighs current earnings against the volatility that comes with the sector. A lower P/E relative to similar businesses can point to a more cautious stance from investors or simply a cheaper entry into the same earnings stream.
Context around the recent income profile is important. Earnings grew 25.1% over the past year and net profit margins are currently 13.4% compared with 11.8% a year earlier, while revenue is reported at CA$716.14m. At the same time, return on equity sits at 4.1%, which is described as low, and earnings over the past 5 years have declined 38.6% per year. That mix of improving recent profitability and weak longer-term history helps explain why the market is not putting an aggressive earnings multiple on Birchcliff Energy yet.
The comparison with other producers is where the valuation gap shows up clearly. Birchcliff Energy trades on a 19.5x P/E that is below the peer average of 31.8x and also under the Canadian oil and gas industry average of 21.6x. That is a firm discount on both measures, which indicates the market is pricing Birchcliff as cheaper than many similar energy stocks despite the recent improvement in earnings growth and margins.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 19.5x (UNDERVALUED)
Still, Birchcliff Energy’s story can be knocked off course if natural gas pricing weakens further or if planned production growth demands heavier capital spending than expected.
Find out about the key risks to this Birchcliff Energy narrative.
Another view on Birchcliff Energy’s value
While the 19.5x P/E suggests Birchcliff Energy looks inexpensive next to peers on earnings, the SWS DCF model sends a very different message. On that framework, the shares at CA$6.80 trade well above an estimated future cash flow value of CA$0.85. This frames the stock as overvalued rather than cheap.
That kind of gap matters for anyone leaning on cash flow driven valuation, because it signals much less room for error if production plans or commodity prices do not line up with expectations.
Look into how the SWS DCF model arrives at its fair value.
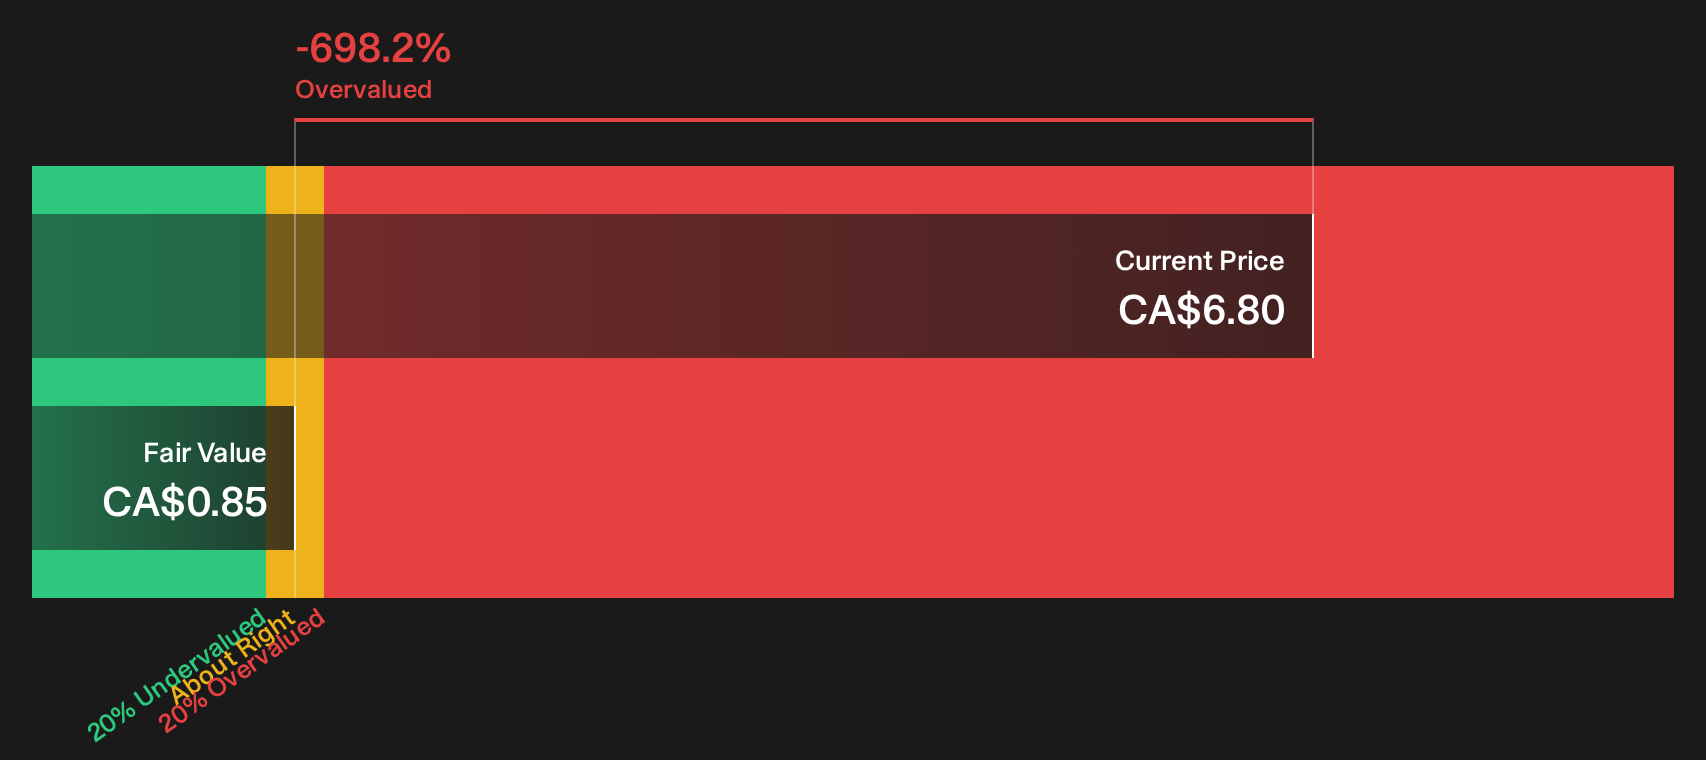
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Birchcliff Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Uncertain whether Birchcliff Energy’s recent moves point to a bargain or a stretched story, given both flagged concerns and clear bright spots in the data, you can move quickly to review the full set of 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Birchcliff Energy?
If Birchcliff Energy has sharpened your focus on value and cash generation, do not stop here. Broaden your watchlist so you are not relying on a single story.
- Target potential mispricing in quality companies by scanning our 5 high quality undervalued stocks that combine solid fundamentals with prices the market has not fully recognised yet.
- Reinforce your income stream by reviewing a curated set of 3 dividend fortresses that aim to keep payouts front and center.
- Prioritise financial resilience by screening a list of solid balance sheet and fundamentals (8 results) so you are focusing on businesses built to handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com