
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can Marex Group (MRX) Stay Undervalued After Its Settlement Approval And New Chair?
Marex Group (MRX) is back in focus after a proposed class action settlement for purchasers of its ordinary shares moved forward in federal court and the board installed a new Chair.
Those legal and boardroom developments land after a strong run for Marex Group, with the share price giving back 2.5% over the past day and 5.2% over the past month, yet still showing an 85.8% year to date share price return and a 133.7% total shareholder return over the past year. Recent weakness therefore appears more like a pause in trading activity as investors reassess both growth potential and the legal risk being cleared up, rather than a decisive shift in momentum.
Scan other financial platforms going through leadership or legal resets by reviewing our curated list of 32 resilient stocks with low risk scores alongside Marex Group.Marex Group has sprinted higher over the past year, then cooled just as the legal overhang and leadership reshuffle hit the headlines. Is that a second chance to enter, or a sign to stay patient for a lower price?
Most Popular Narrative: 12% Undervalued
On the most followed narrative, Marex Group screens as undervalued, with a fair value of $79.88 versus a last close at $70.50. This puts the focus squarely on how durable the current earnings profile really is before investors lean on that gap.
Significant investments in technology and scalable platforms are already yielding desk-level productivity gains, higher revenues per employee, and improved front-office efficiency, supporting further operating leverage and net margin expansion as the business grows.
See why 7 investors see Marex Group as 12% undervalued.
Result: Fair Value of $79.88 (UNDERVALUED)
Still, the Marex Group story can change quickly if acquisition integration stumbles, or if heavier compliance and control costs start to squeeze profitability more than analysts expect.
Find out about the key risks to this Marex Group narrative.
Another View On Marex Group’s Value
The earlier narrative leans on analyst earnings forecasts and a fair value of $79.88. The SWS DCF model paints a more cautious picture. On that framework, Marex Group at $70.50 trades above an estimated future cash flow value of $49.34, which points to the shares looking overvalued rather than cheap.
That gap between an earnings-based fair value and a lower cash flow estimate raises a simple question for investors: Which set of assumptions do you trust more when growth, acquisition pace, and funding costs all carry moving parts?
Look into how the SWS DCF model arrives at its fair value.
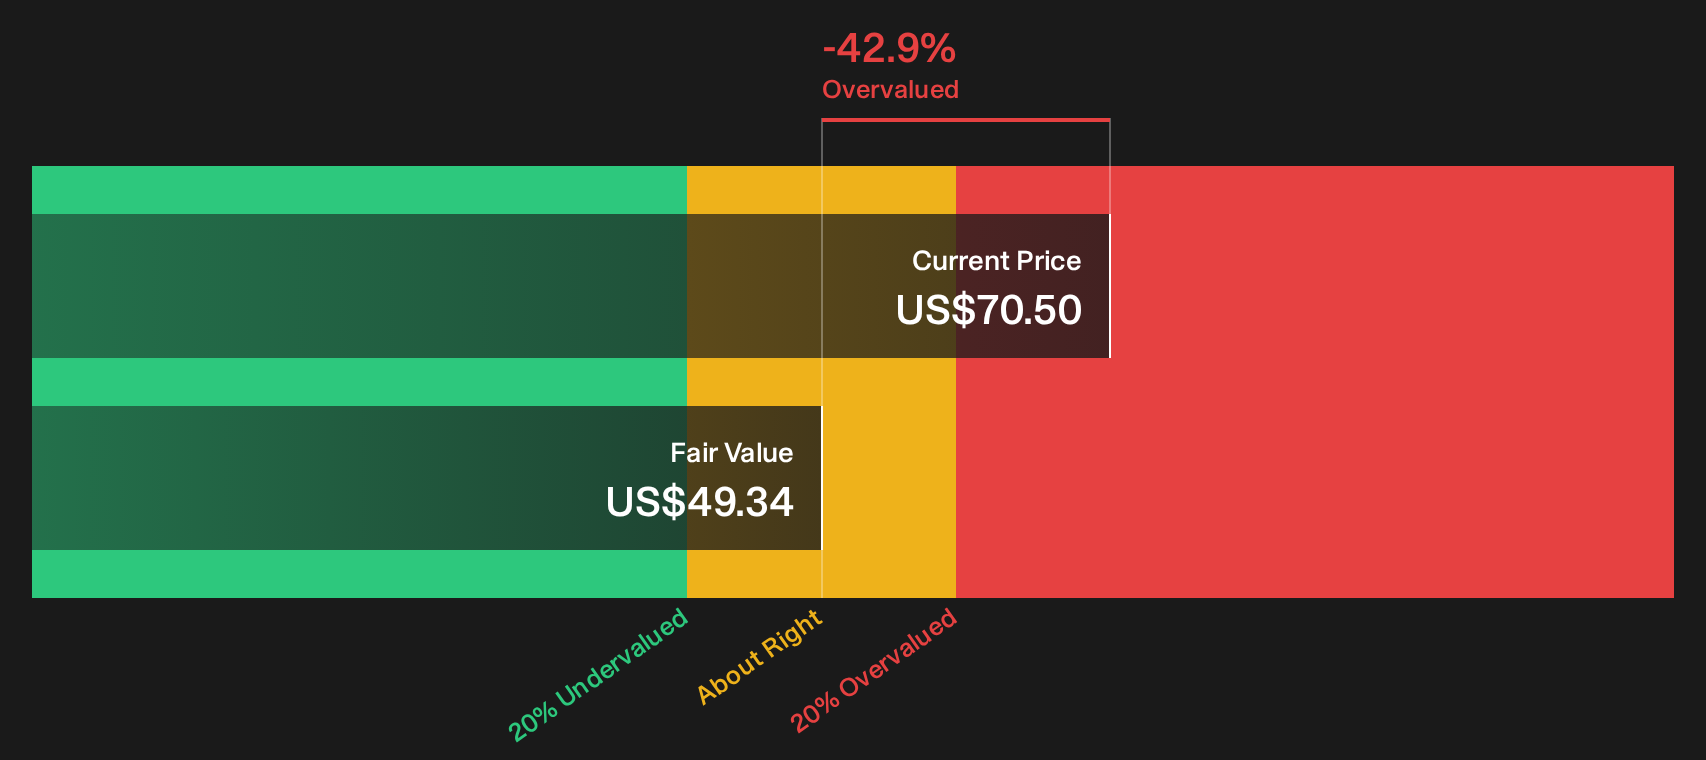
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Marex Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Marex Group can pull sentiment in both directions, so move quickly, review the data and weigh both the 4 key rewards and 1 important warning sign.
Looking for more Marex Group sized opportunities?
If Marex Group has sharpened your focus, do not stop here. Use the Simply Wall St screener to surface fresh ideas before the crowd catches on.
- Target resilience by running your filters through a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without overstretching finances.
- Hunt for potential mispricing with a 33 high quality undervalued stocks that may trade below what their fundamentals suggest.
- Stack up potential income ideas using a 8 dividend fortresses that could help support a steadier cash return profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com