
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Burgan Bank K.P.S.C Bears Were Right Before The Drop
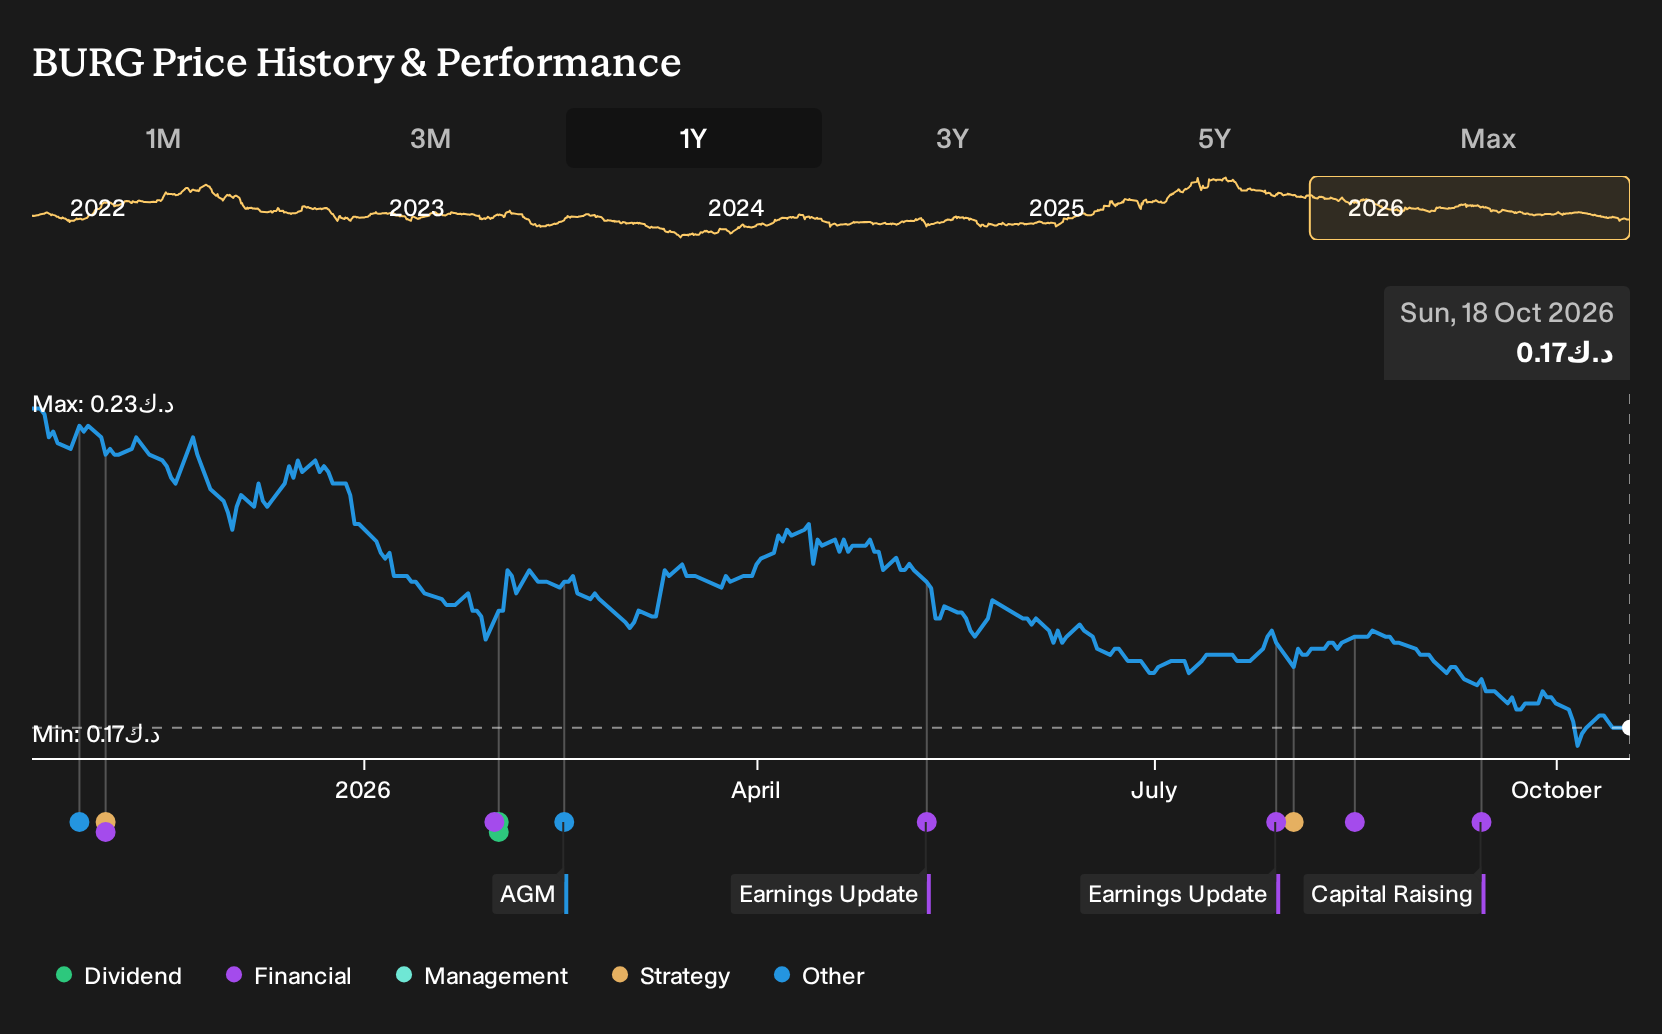
If you had backed Burgan Bank K.P.S.C at the start of this period, the result would have felt uncomfortable. Holding Burgan Bank K.P.S.C over the past year would have meant a 20.7% loss, including dividends. If that decision date on 18 October 2025 was yours, the real question now is which parts of the bullish digitalization and Vision 2035 case, or the bearish cost and credit concerns, were not properly weighed against the risks already visible then?
If the move has made Burgan Bank K.P.S.C harder to judge, start where the gap is still open and scan 189 high quality undervalued stocks.
The Two Burgan Bank K.P.S.C Stories Investors Were Weighing
The shares cost KWD0.24 at the start of the period, and Burgan Bank K.P.S.C sat between two sharply different readings of the same business.
The bullish argument pointed to digitalization and Kuwait’s Vision 2035. It treated KWD0.31 as a fair value, meaning a price that might line up with its more optimistic assumptions, anchored on faster consumer lending and stronger non interest income from new platforms.
The bearish view worked off a fair value of KWD0.18, again an implied price from its own model, and focused on high cost to income, recurring non performing loan spikes from large clients, and Turkey inflation risk feeding into heavier provisions.
What The Burgan Bank K.P.S.C Results Actually Tested
The clearest fact is the Q2 2026 result. Burgan Bank K.P.S.C reported total revenue of KWD23.458m and net income of KWD3.385m, both below Q2 2025, while net margin improved from 12.8% to 14.4%. That mix of weaker top line and profit, together with a slightly stronger margin, cut both ways for the bullish efficiency story and the cautious earnings concerns.
The useful takeaway is simple. When a thesis leans on margin improvement, track whether higher profitability comes with at least stable revenue rather than being helped mainly by shrinking activity.
What Burgan Bank K.P.S.C's Lower Price Now Asks You To Believe
Burgan Bank K.P.S.C trades at KWD0.17 today after a 20.7% share price and dividend decline over the past year. The selected Narrative’s Fair Value sits above the current price and rests on digital platforms, regional mix and fresh capital eventually supporting an earnings profile that differs from the recent headline numbers.
The key assumption you would be testing at today’s level is whether higher operating spend and the new capital raise genuinely convert into a more efficient, resilient and profitable group over the next few years.
"The main thing that has to go right is that Burgan Bank K.P.S.C converts its current period of higher operating expenses and capital raising into sustainably better efficiency, stable asset quality and profitable growth across its loan book."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Go Straight To The Source
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 24% below our estimate - captures senior lawyers exiting partnerships for a tech-enabled, fee-sharing platform structure.
- Company 2 - 19% below our estimate - scales supplement output as automated production and distributor-led expansion increase manufacturing capacity.
- Company 3 - 34% below our estimate - grows fee revenue by raising capital into renewable and infrastructure-focused investment products.
Three companies from the same screener. Open the full list of 204 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com