
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Q2 Earnings Beat Could Be A Big Moment For Atea Stock (OB:ATEA)
- Atea reported Q2 2026 figures showing higher revenue, improved profit, and a thicker net margin, supported by demand for hardware, hybrid cloud work, and AI related infrastructure projects.
- The earnings mix pointed to growing contributions from cloud services and public sector contracts, which can change how dependable Atea’s future cash flows look compared with a hardware heavy model.
- The next step is to examine how Atea’s investment narrative could shift if stronger margins from AI driven infrastructure demand prove repeatable.
What Is Atea's Investment Narrative?
A shareholder in Atea needs to believe that the mix is steadily tilting toward higher margin services around hybrid cloud, cybersecurity, and AI infrastructure while the traditional hardware side still pulls its weight. The Q2 2026 report, with firmer revenue and a thicker net margin, points in that direction and is consistent with forecasts for earnings and revenue growth ahead of the broader Norwegian market. For now, the key near term swing factors appear tied to project execution quality, vendor incentives, and how consistently public sector and managed services work shows up in the order book.
Capital intensity and cash conversion are the other pressure points. Atea trades on a P/E that is below both an internal fair value estimate and the European IT average. This suggests investors already weigh in the AI and cloud thesis quite generously. The 20.9% share price gain over the past year indicates that optimism has been rewarded, but it also raises the bar if margin progress or hardware refresh demand slows from here.
Even so, there is a quieter issue around how comfortably the current dividend policy fits with...
There's only one way to know the right time to buy, sell or hold Atea. Head to Simply Wall St's company report for the latest analysis of Atea's Fair Value.
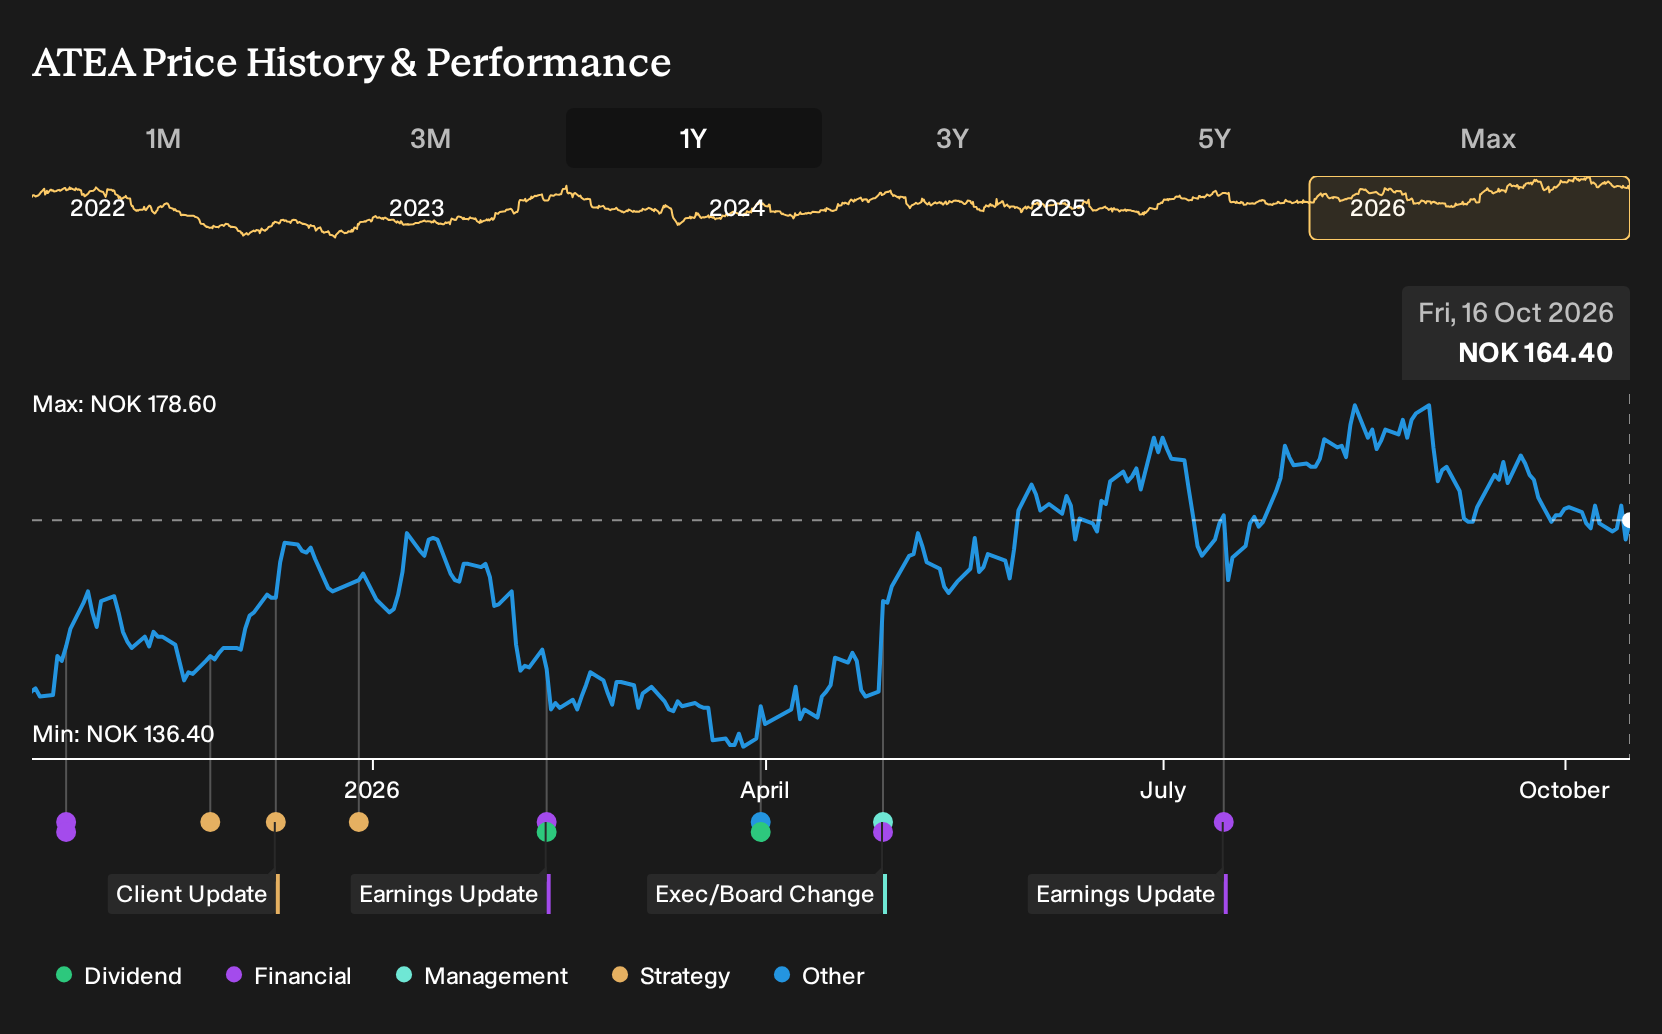
Exploring Other Perspectives
One big swing factor for Atea that bullish analysts highlighted before this Q2 report was margin expansion from higher value services. Some of them were pencilling in around 6.8% annual revenue growth with earnings reaching NOK 1.6b by about 2029. That is a much more optimistic path than consensus. Treat those projections as just one of several possible futures and use this result as a prompt to compare different scenarios for where Atea could go next.
Explore 3 other Atea fair value estimates, including one that suggests potential upside of up to 120% from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Atea research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Atea. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Atea's overall financial health at a glance.
Looking For More Ideas Beyond Atea?
If Atea's mix of AI infrastructure, hybrid cloud, and services has your attention, it can help to line it up against other potential opportunities on your radar. A focused screener lets you filter by the traits you care about most so you can quickly build a watchlist that fits your risk profile and income needs.
- If you want income to play a bigger role in your portfolio, scan for established payers through 215 dividend fortresses that meet your yield and balance sheet requirements.
- If capital protection ranks higher for you than chasing every new theme, filter for steadier profiles using the 234 resilient stocks with low risk scores that screen well on resilience metrics.
- If you are hunting for quality businesses that fewer investors are paying attention to, widen your net with the 614 high quality undiscovered gems that already show strong fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com