
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Missed Nabors Industries' 96% Gain? Here's What Investors Got Right
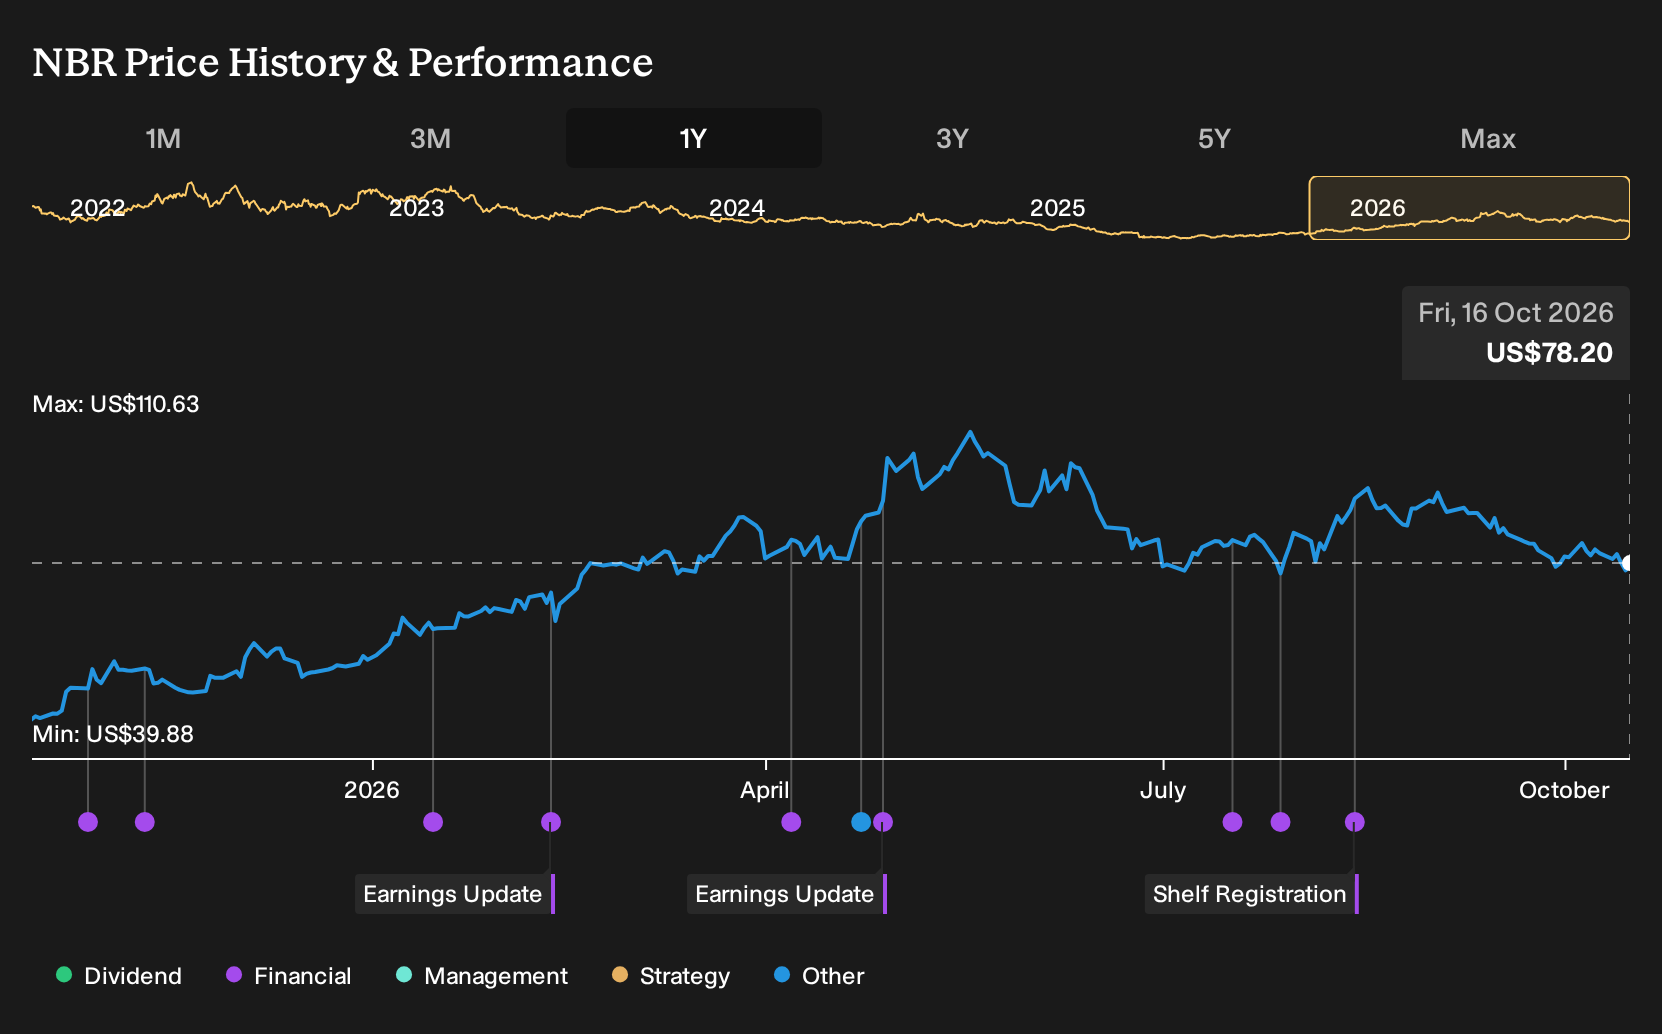
Nabors Industries has not only been signing decade long rig commitments in Saudi Arabia and backing next generation geothermal drilling through Quaise Energy. Holding Nabors Industries over the past year would have returned 96.1%, including dividends. If you had been weighing that kind of outcome on 16 October 2025, you would have been staring at mixed signals on debt, margins, and drilling demand and asking what had to be true about advanced modular rigs and energy transition bets for that decision to make sense.
Nabors Industries has already moved. See which of 33 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing On Nabors Industries
The shares cost US$40.32 at the start of the period, and Nabors Industries sat between two sharply different but reasonable stories about where drilling economics could go next.
The bullish narrative pointed to a Fair Value of US$50, a notional price tied to expectations that revenue could grow 6.9% a year and profit margin could shift from a loss to 7.0% over three years, helped by advanced modular rigs and the SANAD 10 year, 50 rig program.
The more cautious case saw Fair Value at US$37.44, based on worries about high debt, heavy capital needs, and pressure on U.S. Lower 48 rig margins as contracts rolled over at lower day rates.
What The Results Changed For Nabors Industries
Project Obsidian moved from concept to funded plan when Nabors Industries put US$35 million into Quaise Energy’s US$180 million Series B and took a 14% stake, which backed the bullish story about modular rigs feeding energy transition work. The later Q2 2026 numbers told a cooler story, with revenue lower but net loss and net margin both improving. The evidence cut both ways and left profitability assumptions unproven.
The clear hinge here was whether higher margin projects actually improved net margin. When you assess another contractor, track how each quarter’s net margin and absolute profit move against any new long term contracts or technology bets.
What Nabors Industries' Price Now Asks You To Believe
Nabors Industries now trades at US$78.2, after a 96.1% gain over the past year. The selected Narrative sees Fair Value above that level and ties the gap to deeper partnerships, long contracts, and higher earnings power from technology and acquisitions.
If you pay today’s price, you are effectively asking whether multi-year international rig demand and high margin drilling solutions can keep supporting that Narrative over time.
"Key Takeaways: Deepening partnerships, multi-year contracts, and advanced rig capabilities are described as drivers of sustained global growth, reduced cyclicality, and earnings visibility. Innovation in technology and sustainability, along with the integration of acquisitions, is highlighted as supporting margin expansion and cash flow."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
One Step Beyond Nabors
Nabors shows what happens when rigs and drilling technology sit front and center. It is a capital heavy way to tap subsurface potential.
Step sideways and the picture changes. Another business can own the mineral rights underneath producing regions and planned development.
Operators then decide where and when to drill. The mineral holder collects its share when wells on that acreage produce, without running a rig fleet.
It is a different exposure to the same rock Nabors works above. Your question becomes how that landlord style role behaves across cycles.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 24% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com