
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Deep Source Holdings (SEHK:990) Lands A 10 Year Data Centre Deal, Is It Undervalued?
Deep Source Holdings (SEHK:990) is in focus after subsidiary DeepSource (PN) Sdn. Bhd. signed a 10 year data centre colocation agreement covering 67MW of IT capacity in Malaysia.
At a share price of HK$0.565, Deep Source Holdings has seen short term sentiment soften, with a 7 day share price return of 3.42% and a 30 day share price return of 2.59%. This comes after a stronger 90 day gain of 8.65% and a year to date decline of 21.53%, while longer term total shareholder returns of 20.42% over one year and 37.19% over five years indicate momentum has generally been fading despite news such as the new 10 year data centre agreement.
Scan beyond Deep Source Holdings and compare this contract driven story with other data infrastructure plays in our hand picked list of 55 AI infrastructure stocks.
Deep Source Holdings now pairs a long-dated data centre contract with a share price that has fallen over the past year and five years. Do you lean into the current level, or wait for a cheaper entry as valuation stacks up next?
Preferred P/E of 10.4x: Is it justified for Deep Source Holdings?
Valuation for Deep Source Holdings currently hinges on a P/E of 10.4x at a last close of HK$0.565, which screens as expensive versus direct peers yet cheaper than the broader Hong Kong Trade Distributors industry.
The P/E ratio compares what investors are paying for each unit of earnings. At 10.4x you are effectively valuing Deep Source Holdings at a little over ten times its current profit per share. For a group that mixes bulk commodity trading with financial services, that multiple becomes a quick shorthand for how the market is weighing recent earnings strength against a tougher multi year record.
On one hand, earnings grew very strongly over the past year and net profit margins widened to 3.1% from 0.9%. On the other hand, profits have declined 16.4% per year over the past five years and Return on Equity of 10.5% is described as low, which suggests the P/E at 10.4x may be pricing in a cleaner earnings base rather than a clear turnaround trend.
Compared with the direct peer average P/E of 5.8x, Deep Source Holdings screens as expensive. However, relative to the wider Hong Kong Trade Distributors industry average of 11.3x, the stock is framed as good value. That split view hints at a tension between short term earnings acceleration and longer run profitability metrics that have lagged, and it leaves the current 10.4x multiple sitting in a middle ground where buyers and sellers may both find supporting data.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 10.4x (ABOUT RIGHT)
Still, Deep Source Holdings faces clear pressure points if earnings slip again or if the 10 year data centre deal ties up capital without lifting overall returns.
Find out about the key risks to this Deep Source Holdings narrative.
Another View: What Our DCF Model Says About Deep Source Holdings
The SWS DCF model presents a different perspective on Deep Source Holdings. At a share price of HK$0.565 and an estimated future cash flow value of HK$1.23, the stock appears to be trading about 54% below that fair value estimate. This suggests a wide gap between what the market pays today and the cash flows implied by the model. The key question is whether you place more weight on the earnings track record or on the long term cash flow view.
Look into how the SWS DCF model arrives at its fair value.
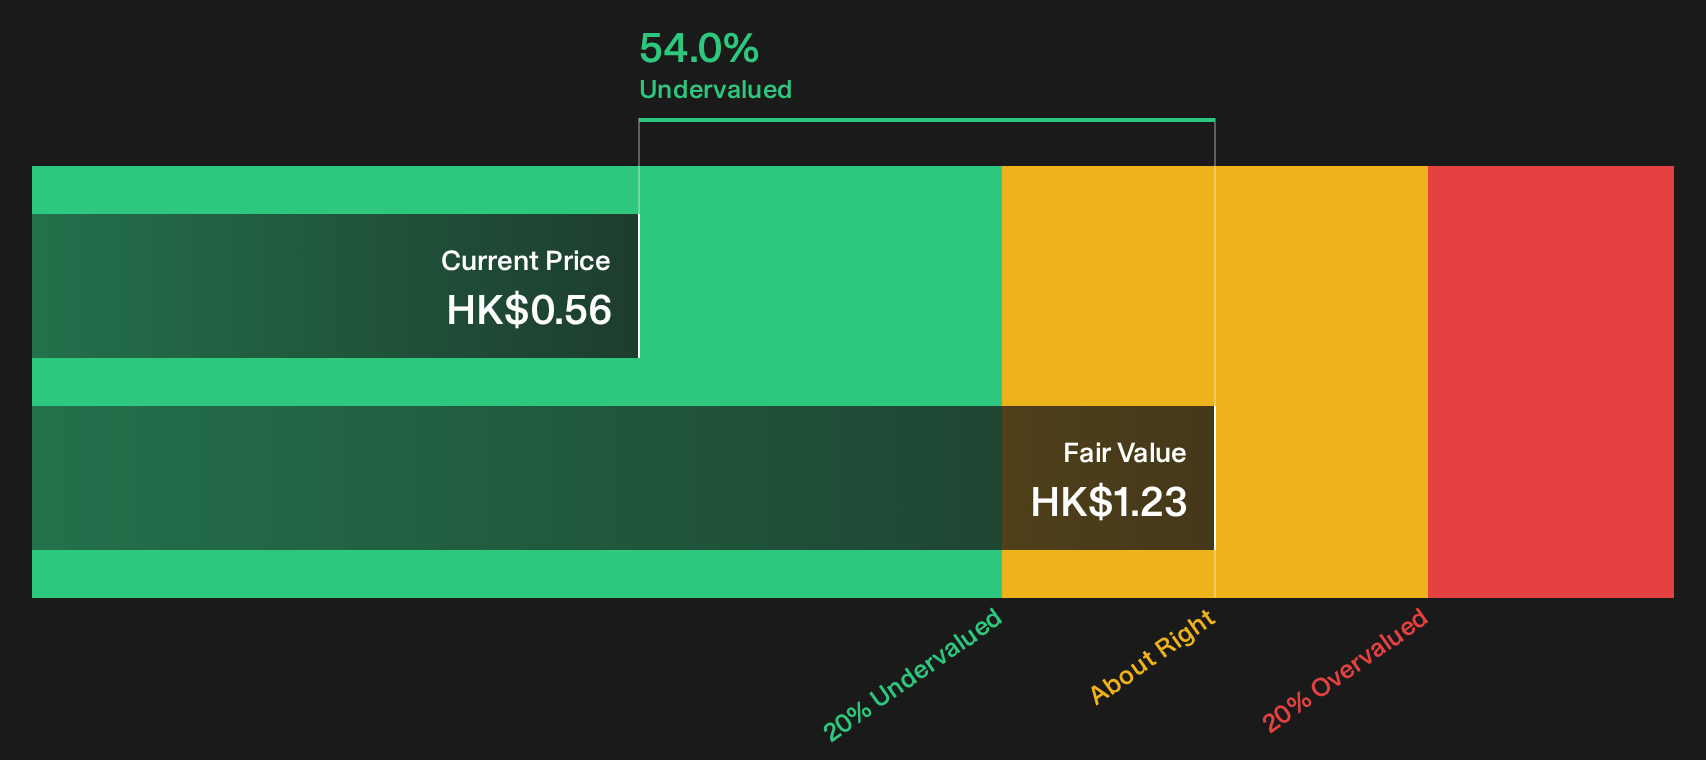
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Deep Source Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 189 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around Deep Source Holdings leave you on the fence, act promptly to review the underlying data and form your own stance using 2 key rewards and 1 important warning sign.
Looking for more Deep Source Holdings sized ideas?
Do not stop at Deep Source Holdings. Broaden your watchlist with fresh opportunities that match different risk, income, and quality profiles across the market.
- Chase potential mispricing by reviewing a curated set of companies that pair solid fundamentals with appealing valuations through the 189 high quality undervalued stocks.
- Build steadier income streams by scanning for resilient payers with higher yields using the 215 dividend fortresses.
- Dial down portfolio risk by focusing on businesses that pass tighter balance sheet and quality checks inside the list of solid balance sheet and fundamentals (204 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com