
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Pulse Biosciences (PLSE) Expensive After Its Clayman Thyroid Center Partnership?
Pulse Biosciences (PLSE) is back on investor radars after announcing a partnership with the Clayman Thyroid Center in Tampa, linking commercial use of its Vybrance System with new real-world thyroid nodule data.
The share price of Pulse Biosciences has pulled back over the past week and month, with 7 day and 30 day share price returns both down around 17%, even though the 90 day share price return is up 53.4% and the year to date share price return is up 231.8%. At the same time, total shareholder return over the past year is 153%, and over three years it is roughly 10x. This suggests that recent thyroid and atrial fibrillation updates are landing on top of already very strong long term momentum and shifting views on both growth potential and risk.
Scan other high-momentum healthcare names riding fresh clinical data and partnership news using the hand-picked 33 healthcare AI stocks that echo what is playing out at Pulse Biosciences.
Pulse Biosciences now pairs a strong story in thyroid and atrial fibrillation with a share price that has run hard this year. The real question is whether US$44.43 already bakes in that promise.
Most Popular Narrative: 29% Undervalued
Against the last close at $44.43, the most followed fair value narrative at $62.33 points to a wide gap that hinges on Pulse Biosciences turning its thyroid and atrial fibrillation pipeline into meaningful revenue and earnings over time.
Growing clinical evidence through PRECISE BTN, NANOCLAMP AF, and European feasibility studies is expected to strengthen reimbursement, support guideline inclusion, and drive higher procedure adoption. This is anticipated to improve revenue visibility and operating leverage as fixed R&D and commercial infrastructure is spread over a larger sales base.
See why 2 investors see Pulse Biosciences as 29% undervalued.
Result: Fair Value of $62.33 (UNDERVALUED)
Still, the fair value story for Pulse Biosciences hinges on early trials and reimbursement falling into place, and any stumble there could quickly challenge that 29% discount.
Find out about the key risks to this Pulse Biosciences narrative.
Another View: What Multiples Say About Pulse Biosciences
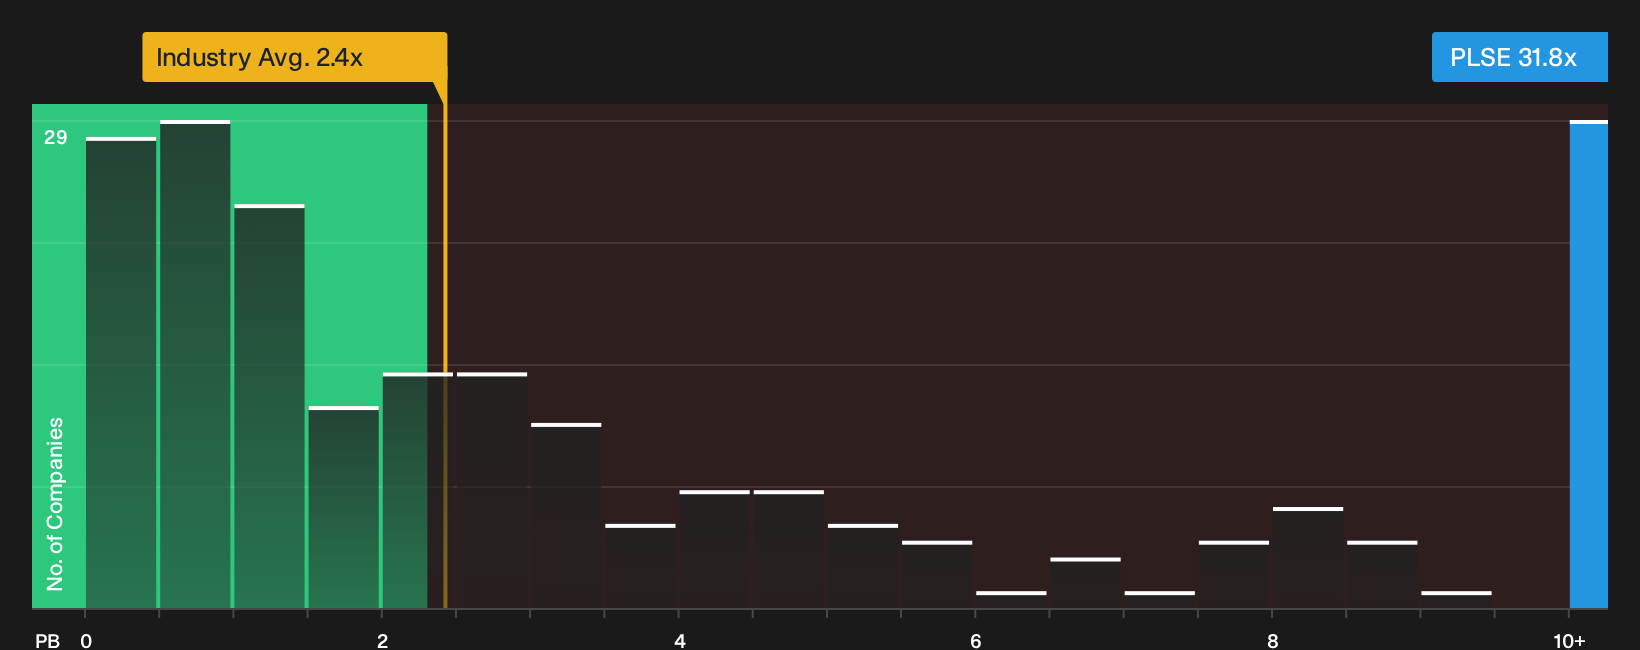
That analyst fair value story for Pulse Biosciences runs straight into a very different signal from simple market ratios. The stock trades on a P/B of 31.8x, compared with 2.4x for the US Medical Equipment group and 8.4x for closer peers, which points to a rich valuation and far less room for error than the 29% discount implies.
For readers weighing these cross currents, the real question is whether that premium reflects future thyroid and atrial fibrillation value, or leaves too much valuation risk if the story takes longer to play out. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Pulse Biosciences so far. If you want to move quickly yet confidently, weigh both sides of the story with the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Pulse Biosciences?
If Pulse Biosciences has you thinking harder about risk and reward, do not stop here. Use the Simply Wall Street screener to surface other focused opportunities before the crowd does.
- Target potential mispricing by scanning the 33 high quality undervalued stocks that match your view on quality, cash flows, and balance sheet strength.
- Build a cash flow cushion by reviewing the 8 dividend fortresses that combine income potential with resilience across different market conditions.
- Reduce downside shocks by filtering for the 32 resilient stocks with low risk scores that align with your comfort level on volatility and financial health.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com