
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Cathay Pacific Airways Doubters Overlooked
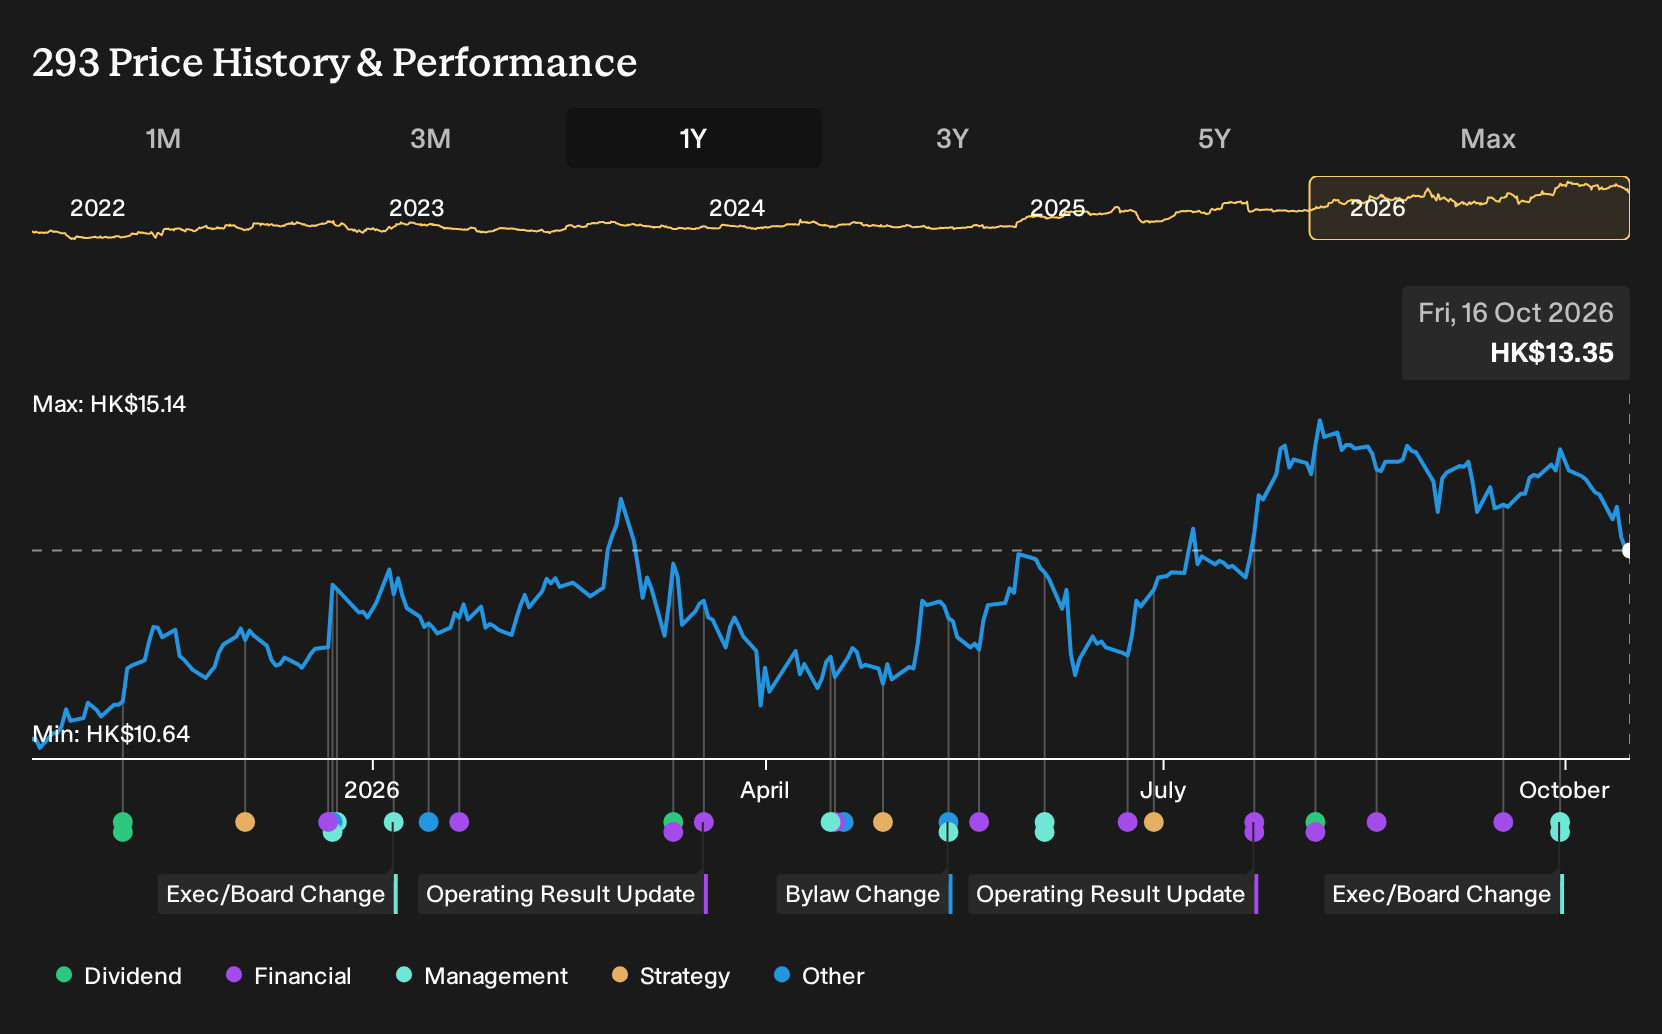
A single aircraft lease captured Cathay Pacific Airways’ mixed year. Its Air Hong Kong unit agreed to take on a long term A330 freighter to support DHL and other express clients, even as war risk later forced the group to halt some Middle East cargo restarts and reroute passengers around conflict zones. For Cathay Pacific Airways shareholders, the return over the past year was 35.0%, including dividends. If you were deciding back in October 2025, what would need to be convincing about this cargo heavy model for that decision to feel sensible?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind Cathay Pacific Airways. Zero in on 189 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On Cathay Pacific Airways
The shares cost HK$10.77 at the start of the period, so any thesis on Cathay Pacific Airways had to justify paying just above or below that line.
The bullish narrative set fair value at HK$13.1, or 22% above the start price, and was based on Cathay using over 100 new aircraft to expand its network faster than rivals while focusing on premium cargo and loyalty earnings.
The bearish view put fair value at HK$9.15, or 15% below the start price, and emphasized Cathay’s heavy cargo exposure and the risk that a US China trade war could drag on volumes and keep the future P/E near 8.0x.
What The Results Changed For The Cathay Pacific Airways Thesis
Cathay Pacific’s H1 2026 report showed revenue of HK$68,061m and net income of HK$6,243m, with net margin at 9.2% compared with 6.7% in H1 2025. That rise in profitability and the Air Hong Kong A330 freighter lease both leaned toward the bullish view on premium cargo and earnings power, although halted Middle East cargo flights kept the bear case alive. Overall, the evidence cut both ways.
The episode turned on one clear assumption. Any future thesis around Cathay Pacific needs to connect cargo heavy ambitions and profit forecasts directly to reported margin trends and route decisions, then track whether those actually move in the same direction over time.
What Cathay Pacific Airways’ Price Now Assumes
Cathay Pacific Airways trades at HK$13.35 today, after a 35.0% gain over the past year, and this Narrative’s Fair Value now sits below that level on a cautious view.
The Narrative focuses on heavy capex, higher fuel and operating costs and the need for that spending to translate into pricing power and cargo demand. For today’s price to feel justified, a buyer must believe Cathay can fund its HK$150b build out while keeping margins resilient against fuel shocks and rising non fuel costs.
"Cathay’s commitment of about HK$150b for fleet and product investment, including 105 aircraft already on order and a long term target of 150 new aircraft and 150 destinations, creates a rising depreciation and financing burden that may pressure earnings and free cash flow if passenger and cargo yields do not keep pace with the enlarged asset base."
The price and this Narrative do not agree. → Uncover what this Narrative says Cathay Pacific Airways is actually worth
Cathay Pacific And A Different Bet
Cathay Pacific keeps leaning into long haul aircraft, fuel and routes. You could also look at a very different aviation bet.
One developer is spending heavily on electric aircraft that take off vertically. The focus is short urban hops, airport shuttles and defense work rather than global networks.
It is pushing toward certification, autonomy software and new propulsion ideas together. That mix keeps cash needs high and timelines closely tied to regulators.
If those air taxis and defense variants gain traction, the economics look unlike Cathay Pacific’s fleet heavy model. The open question is how quickly real passengers and governments show up.
One Narrative has already put a figure on it. → Uncover the company trading 55% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com