
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is EQ Resources (ASX:EQR) Still Below Fair Value After Record Tungsten Production?
EQ Resources (ASX:EQR) has drawn fresh attention after reporting record tungsten production at its Spanish Barruecopardo and Australian Mt Carbine operations, which contributed to higher recent revenue figures and cash generation for the miner.
Recent record output and stronger cash generation have arrived after a sharp run up, with EQ Resources’ share price posting a 27.27% 90 day gain and a very large year to date share price return of 237.35%. The 1 year total shareholder return of around 7x indicates momentum has been strong, despite a 30 day share price pullback of 38.46% and a weaker 7 day share price return of 13.85%, suggesting some investors may be reassessing the premium now attached to the stock.
Spot similar momentum and premium stories to EQ Resources by scanning our curated list of 32 best rare earth metal stocks in one place.After a 7x one year total return, EQ Resources now trades at a reported 57% discount to an intrinsic value estimate and a roughly 91% gap to analyst targets. Is that caution or mispricing?
Preferred Price-to-Sales of 8.8x: Is it justified?
EQ Resources now carries a price-to-sales, or P/S, ratio of 8.8x against its last close of A$0.28. This suggests the market is paying a steep revenue multiple after a very strong one year total return.
The P/S ratio compares the miner’s market value to its A$165.439 million in revenue and shows how much investors are paying for each dollar of sales. For a producer of tungsten and other minerals, that figure can reflect expectations around future volumes from Mt Carbine and Barruecopardo, as well as confidence in the company’s ability to convert record output into durable cash generation.
On peer and fair value checks, the picture is mixed. Against the Australian Metals and Mining industry average P/S of 83.3x, EQ Resources screens as cheap, with the market assigning a far lower revenue multiple than the wider sector. However, compared to closer peers on 3.5x P/S and an estimated fair P/S of 5.7x, EQ Resources looks expensive. This implies the current premium already factors in stronger growth or execution than similar miners and sits above the level the market could move towards if sentiment cools.
Explore the SWS fair ratio for EQ Resources.
Result: Price-to-Sales of 8.8x (OVERVALUED).
Still, the EQ Resources story could be knocked off course if recent production strength fades, or if tungsten pricing weakens and squeezes margins.
Find out about the key risks to this EQ Resources narrative.
Another view on EQ Resources valuation
A different lens tells a very different story. Our DCF model points to an intrinsic value of about A$0.65 per share for EQ Resources, which is above the last close of A$0.28. On this view, a stock that looks expensive on an 8.8x P/S ratio screens as undervalued. Which signal do you trust when the two pull in opposite directions?
For a closer look at how this cash flow view is built, you can walk through the full SWS DCF model for EQ Resources, step by step, in our valuation breakdown, Look into how the SWS DCF model arrives at its fair value.
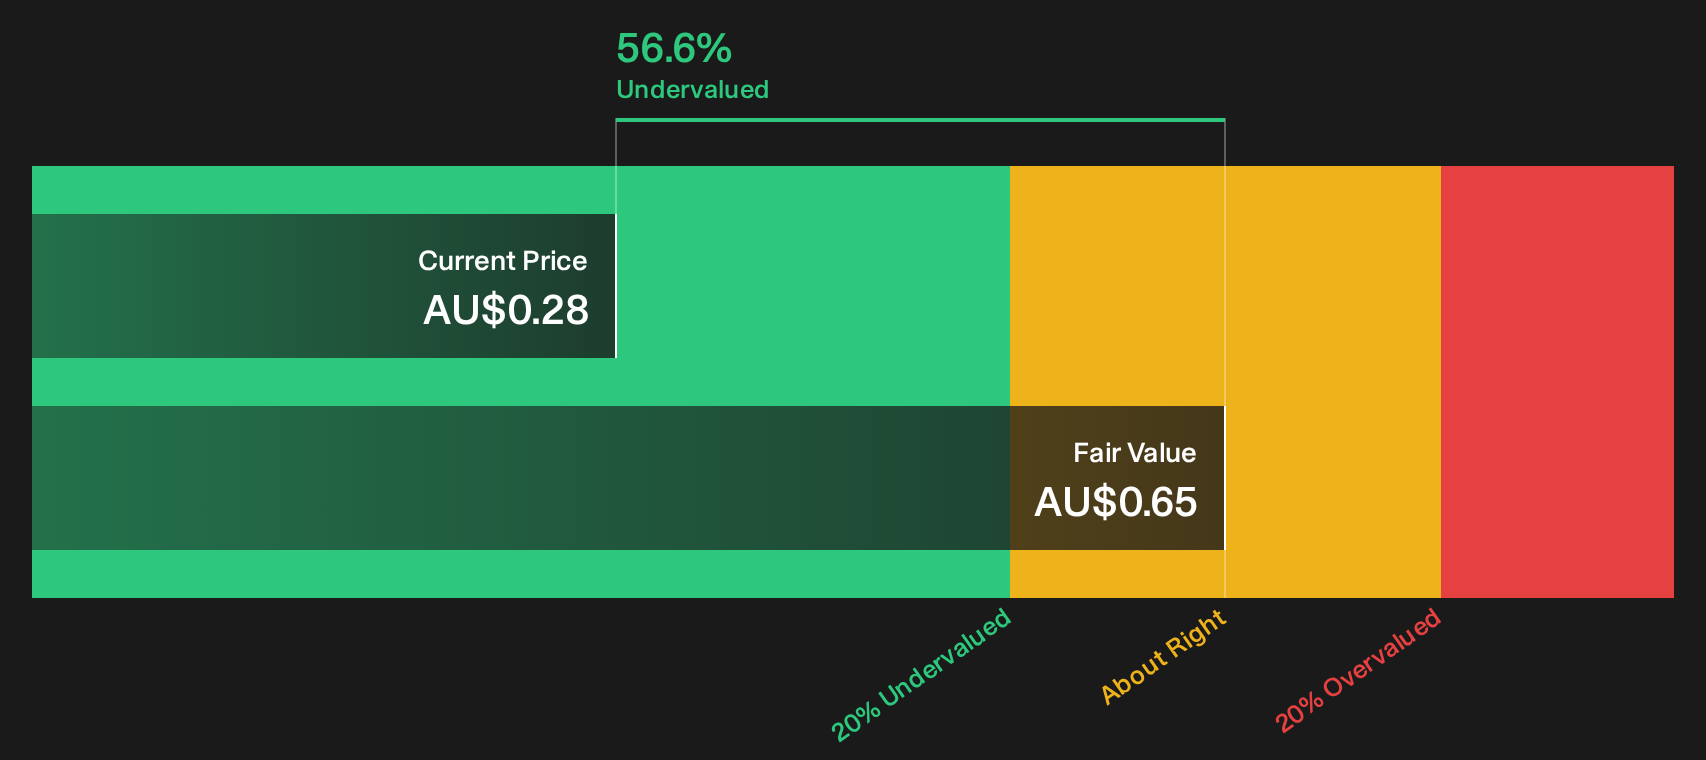
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out EQ Resources for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on EQ Resources so far. If you want to move quickly and build your own take from the numbers, start with the 3 key rewards and 3 important warning signs.
Looking for more EQ Resources style ideas?
If EQ Resources has sharpened your focus on opportunity, do not stop here. Broaden your watchlist now and give yourself more options when momentum shifts.
- Target potential mispricing across the market by scanning a curated pool of 5 high quality undervalued stocks that combine quality fundamentals with marked-down valuations.
- Strengthen your income toolkit by reviewing a focused group of 4 dividend fortresses that pair higher yields with business models built to support regular payouts.
- Reduce portfolio stress by concentrating on a 6 resilient stocks with low risk scores where financial health and lower risk scores sit at the front of the filter set.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com