
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Johnson Controls Doubters Overlooked
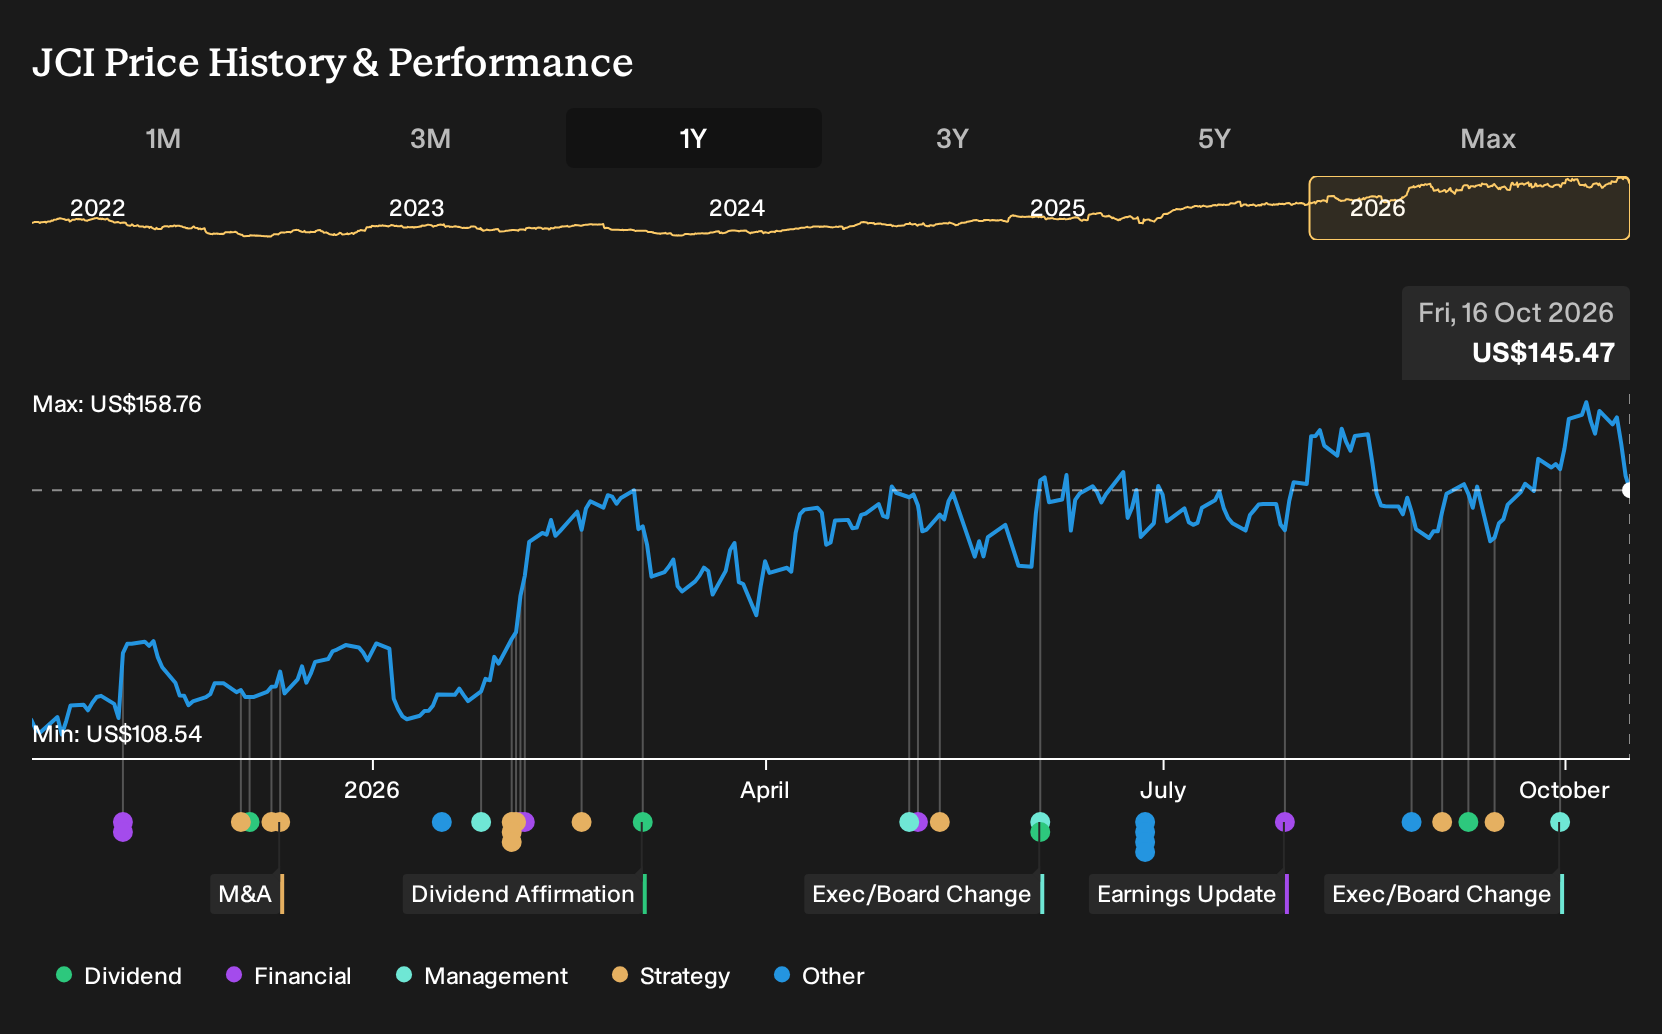
Johnson Controls International has spent the past year tying its future more tightly to data center cooling, from the Alloy Enterprises acquisition to new absorption chiller designs that turn waste heat into extra AI capacity. For Johnson Controls International shareholders, the return over the past year was 35.3%, including dividends. If you were deciding back on 16 October 2025, what beliefs about OpenBlue, smart cities and data center demand would have justified buying in?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Johnson Controls International has already moved. Pinpoint other ways to investigate the theme among 55 AI infrastructure stocks.
The Two Stories Johnson Controls Investors Were Weighing
The shares cost US$109 at the start of the period, so anyone looking at Johnson Controls International back then had to decide which story felt more convincing.
The optimistic narrative put Fair Value at US$131, based on assumptions that OpenBlue, smart cities and data center cooling could support revenue growth of 5.8% a year and a move in profit margins from 9.6% to 13.1% by 2028.
The cautious view saw Fair Value at US$79 and focused on risks such as reliance on mature North American and European markets and higher procurement costs from geopolitical and supply chain pressure.
What The Results Changed For Johnson Controls International
Johnson Controls International leaned into the bullish story. Q3 2026 revenue reached US$6,614m versus US$6,052m a year earlier, and net income excluding extra items moved from US$618m to US$749m. Net margin rose from 10.2% to 11.3%. Together with Alloy Enterprises and absorption chiller moves in data center cooling, the period largely supported the optimistic case.
The useful takeaway is where to look first. When a thesis leans on higher margins from platforms like OpenBlue or AI infrastructure, it can be helpful to track segment revenue in those areas and the reported net margin trend rather than focusing only on headline guidance or analyst upgrades.
What Johnson Controls International’s Price Already Assumes
Johnson Controls International now trades at US$145, with this Narrative’s Fair Value sitting below that quote. The gap reflects concern that enthusiasm for AI cooling and building tech may already be embedded in the valuation.
The Narrative focuses on execution. A buyer today effectively assumes high single digit organic growth and strong operating leverage, so the key question is how PFAS cash outflows and possible data center delays affect that path.
"The main requirement is that Johnson Controls International converts its strong order growth, business system gains, and portfolio reshaping into sustained high single-digit organic revenue growth and 30%+ operating leverage, without material setbacks from issues such as PFAS remediation or data center project delays."
The price and this Narrative do not agree. → Uncover what this Narrative says Johnson Controls International is actually worth
Go Straight To The Source
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 48% below our estimate - target large-format LED installations as transportation hubs and youth sports venues modernize.
- Company 2 - 45% below our estimate - sell modular digital banking stacks as regional lenders shift routine transactions to apps.
- Company 3 - 43% below our estimate - supply control hardware and software as utility-scale solar fields consolidate vendor relationships.
Three companies from the same screener. Open the full list of 33 companies trading below our fair value estimates →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com