
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Trupanion (TRUP) Rebounds On Margin Focus, Is The Stock Still Cheap?
Trupanion (TRUP) has drawn attention after recent trading, with the stock closing at US$28.12. Investors are weighing this pet insurance provider’s subscription driven model against its mixed return profile across different time frames.
Recent trading tells a two sided story for Trupanion. Short term momentum has been firm, with a 1 month share price return of 12.17% and a 7 day gain of 7.90%. However, the stock remains down 24.41% on a year to date share price basis, and the 1 year total shareholder return has fallen 34.45%. This leaves long term holders with a mixed picture, despite a 3 year total shareholder return of 23.82% and a 5 year total shareholder return that has declined 73.83%.
Compare Trupanion’s mixed return profile with other insurance peers that combine subscription style revenue with stronger recent trends by scanning our curated list of list of solid balance sheet and fundamentals (25 results).
Trupanion’s recent rebound still leaves the shares trading below the average analyst price target of US$33.25. Is that discount a sign of opportunity, or does the uneven return record justify the market’s caution?
Most Popular Narrative: 18% Undervalued
Against Trupanion’s last close at $28.12, the most followed narrative places fair value closer to $34.25. This frames the current discount around disciplined margin execution and measured revenue growth.
Improved underwriting discipline, focus on higher lifetime value pets, and optimization of acquisition channels are driving higher-quality book growth and supporting strong free cash flow, setting up for scalable and more profitable expansion in coming years.
See why 6 investors see Trupanion as 18% undervalued.
Result: Fair Value of $34.25 (UNDERVALUED)
Still, the bullish Trupanion narrative can unravel quickly if subscriber additions remain sluggish while relying heavily on price increases, or if competitors keep taking share in a slower market.
Find out about the key risks to this Trupanion narrative.
Another View: Trupanion On Earnings Multiples
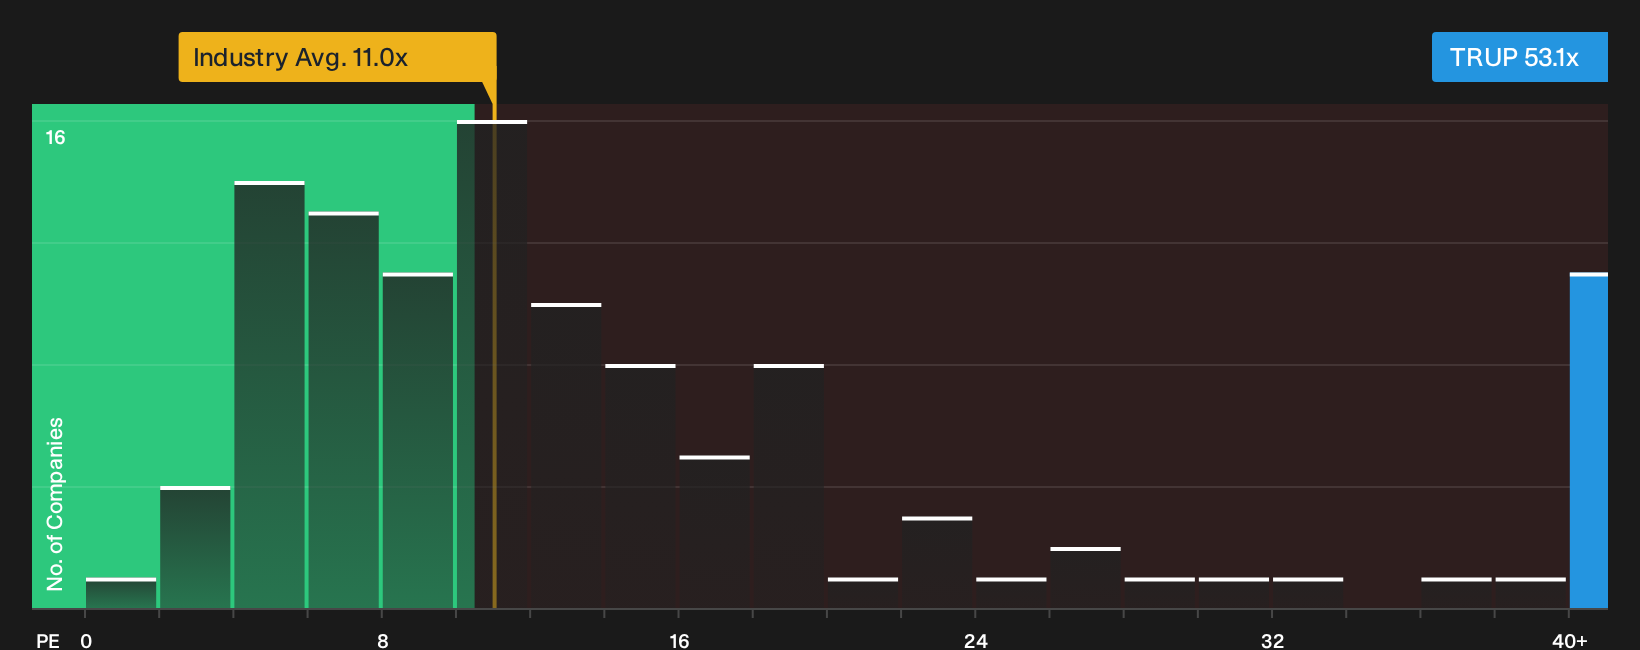
While the Trupanion narrative points to a fair value of $34.25, the current P/E of 53.1x tells a very different story. That valuation is far above the US Insurance industry at 11x and peers at 12.6x, and it even exceeds a fair ratio of 12.8x that the market could move toward. For anyone weighing the stock, the key question is whether current optimism leaves little margin for disappointment.
To see how these earnings multiples stack up against the underlying numbers and where valuation pressure could build, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Trupanion’s value story are one thing; your own read of the data is another. To see what has investors optimistic, review the 2 key rewards
Looking for more Trupanion sized investment ideas?
You do not need to stop at Trupanion. Broaden your watchlist now with a few targeted screens that surface different types of opportunities before others react.
- Hunt for quality at a discount by scanning companies that appear mispriced on fundamentals using the 33 high quality undervalued stocks
- Strengthen your defensive side by checking resilient stocks with dependable balance sheets through the list of solid balance sheet and fundamentals (25 results)
- Spot potential future market favorites early by reviewing a focused set of under followed businesses via the 20 high quality undiscovered gems
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com