
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Record Earnings Will Impact Charles Schwab (SCHW) Investors
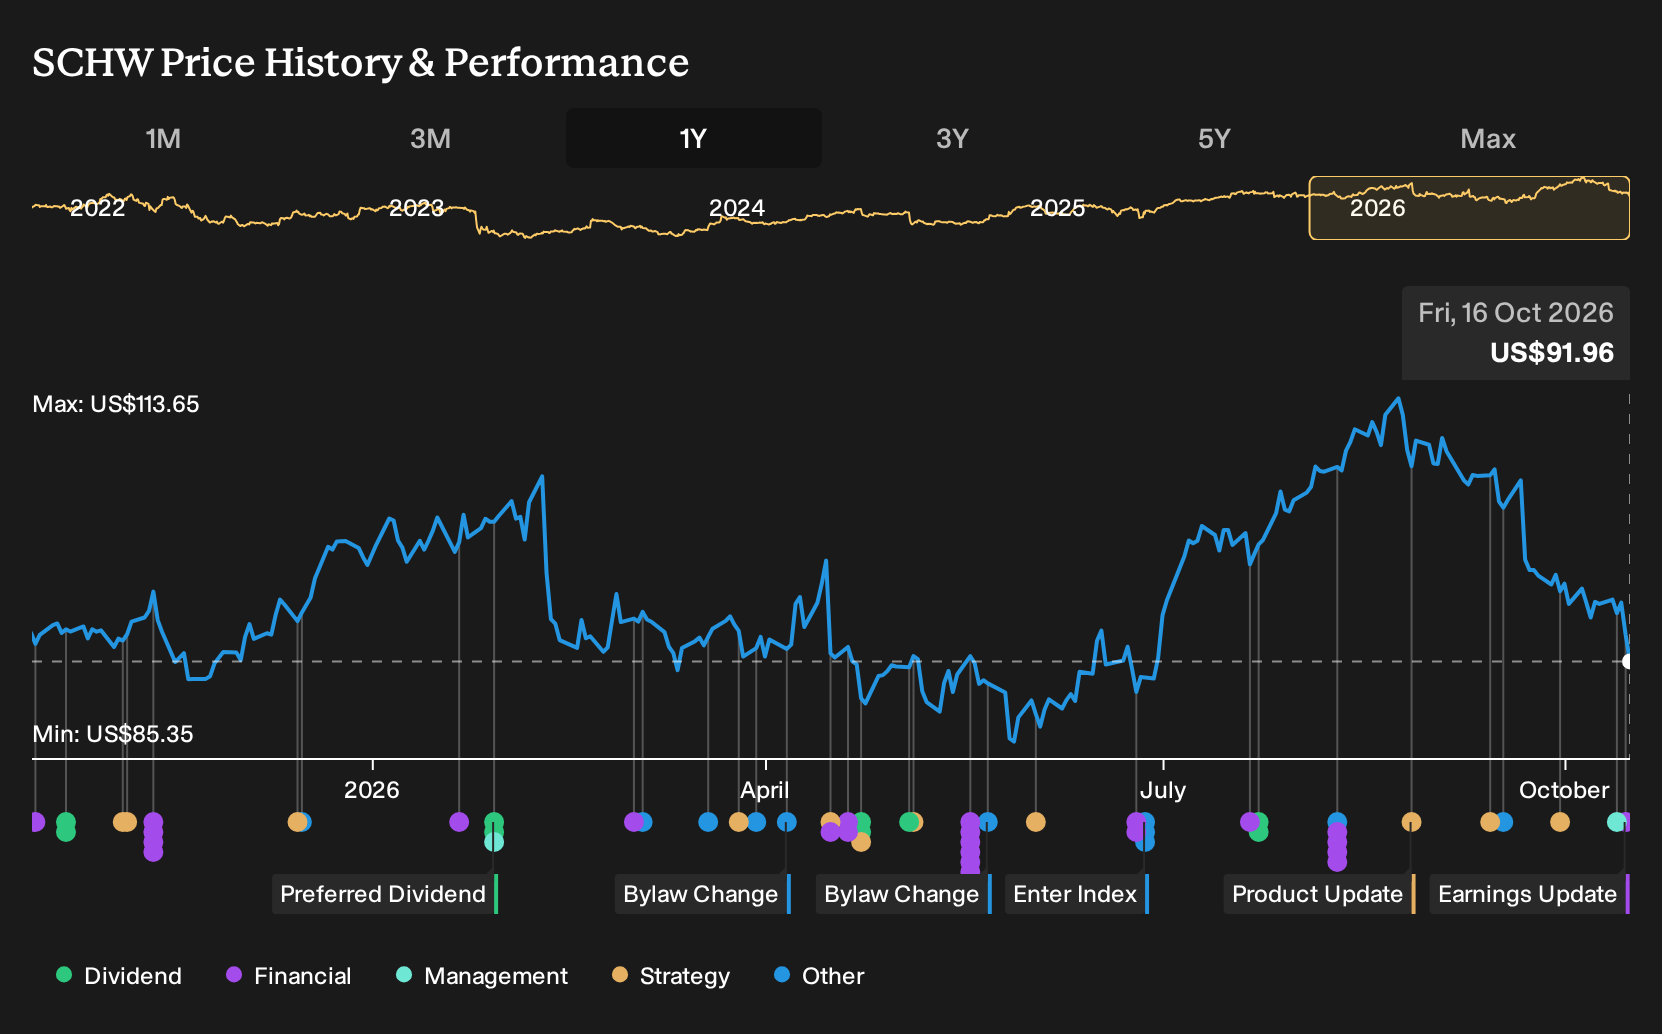
- Charles Schwab reported third quarter 2026 net income of US$2.906b, up from US$2.358b a year earlier, with diluted EPS from continuing operations rising to US$1.62 from US$1.26.
- The firm paired these record results with new AI driven products, including the Charley assistant and prediction markets, which could influence how clients trade, borrow, and use advice on its platform.
- Next, the focus will be on how Charles Schwab's earnings trends and AI initiatives may affect the longer term investment narrative.
Charles Schwab Investment Narrative Recap
To stay comfortable owning Charles Schwab, an investor needs to believe the firm can keep turning its scale in brokerage, advice, and banking into steady earnings while controlling technology and AI spending. The Q3 2026 report, with net income of US$2.906b and nine month profit of US$8.185b, supports that profitability story without changing it radically.
The near term swing factor is whether Schwab can grow lending, advice, and trading activity while keeping expense growth below revenue growth. The biggest operational risk is that heavy AI and platform investments, plus volume related costs, push expenses higher than planned and compress margins if revenue momentum cools.
The most relevant announcement for this earnings print is the launch of Schwab's AI assistant, Charley, alongside broader AI tools for traders and advisors. Management also highlighted that clients connecting AI models to Schwab's systems have roughly doubled in six months, which points to rising digital engagement on the platform.
If Charley and related tools deepen trading activity, advice uptake, and use of banking products, they could support the core catalysts around fee and interest income. The flip side is execution risk. If AI driven offerings require higher ongoing technology spend or create operational and supervision challenges, they could add to the cost and compliance pressures already flagged as key risks.
Charles Schwab's current analyst story points to forecast revenues of US$35.8b and earnings of US$15.4b by 2029, based on assumed yearly revenue growth of 11.3% and an earnings increase of about US$5.7b from US$9.7b today.
Uncover how Charles Schwab's fair value indicates a 33% potential upside to its current price, which could narrow quickly if sentiment turns more optimistic.
Exploring Other Perspectives
For Charles Schwab, the bullish twist comes from lending. The most optimistic analysts were already penciling in revenue of US$41.6b and earnings of US$16.8b by 2029, based on the view that pledged asset lines and margin loans scale quickly. You can now ask whether the latest AI launch and earnings beat push that scenario closer or further away, and explore both angles before deciding what makes sense for you.
Explore 3 other Charles Schwab fair value estimates, including one that suggests as much as 57% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Charles Schwab research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Charles Schwab. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Charles Schwab's overall financial health at a glance.
Looking For More Investment Ideas Beyond Charles Schwab?
Once you have a handle on Charles Schwab's trajectory, it can help to widen the lens and line up a few alternatives that share similar qualities or offer different risk and income profiles. The Simply Wall St Screener lets you move from a single stock story to a watchlist built around clear rules that match your style, whether that means stability, value, or growth potential.
- For investors who want mispriced quality with room for sentiment to catch up, scan our curated 33 high quality undervalued stocks that pair stronger fundamentals with prices that sit below our fair value estimates.
- If capital preservation and smoother returns matter most to you, focus on companies screened for financial resilience using the 32 resilient stocks with low risk scores which filters for lower risk scores and sturdier balance sheets.
- When income is a priority and you are hunting for higher yields, use the 8 dividend fortresses to zero in on businesses offering 5%+ payouts while still meeting basic financial health checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com