
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Great Canadian Dividend Stocks To Own In October 2026
Inflation in the US recently reached 3.7%, driven largely by higher energy costs, and that kind of price pressure often pushes investors toward reliable cash payouts. Regular income from established Canadian dividend stocks can feel more predictable than trying to anticipate where markets will move next. This article reviews three high-yield dividend payers with yields above 3%, with a focus on well covered, growing, and steady payouts.
The three stocks highlighted here offer a compelling starting point if you want exposure to well covered, growing, and stable dividend payers. However, if you want the names that matter most, these 3 dividend aristocrats stocks are the strongest companies we've found.
Sun Life Financial (TSX:SLF)
Sun Life Financial is a global insurer and asset manager whose life, health, and wealth products generate recurring premiums and fee income that support its role in a 3%+ dividend yield screen.
Sun Life Financial earns about CA$15.7b in Canada, CA$13.0b in the U.S., CA$7.7b from Sun Life Asset Management and CA$2.6b across Asia, with a market value around CA$62.5b.
"Strong growth in Asia individual insurance sales, with $875 million of quarterly sales and over $7 billion of contractual service margin in the region, supports the view that Sun Life Financial can keep expanding its addressable market and add new premium and fee income streams that feed into earnings growth."
What happens to that carefully balanced earnings mix if a single pressure point quietly reshapes where the next dollar of profit really comes from?
If that profit mix is quietly shifting, you will want the full narrative for Sun Life Financial to see what might be accelerating beneath Sun Life Financial's headline numbers.

Magna International (TSX:MG)
Magna International builds many of the parts and full vehicles that keep global car production running, with growing exposure to EV battery enclosures, powertrains, and ADAS hardware. These help fund a 3%+ dividend through cash flows tied to long term auto programs.
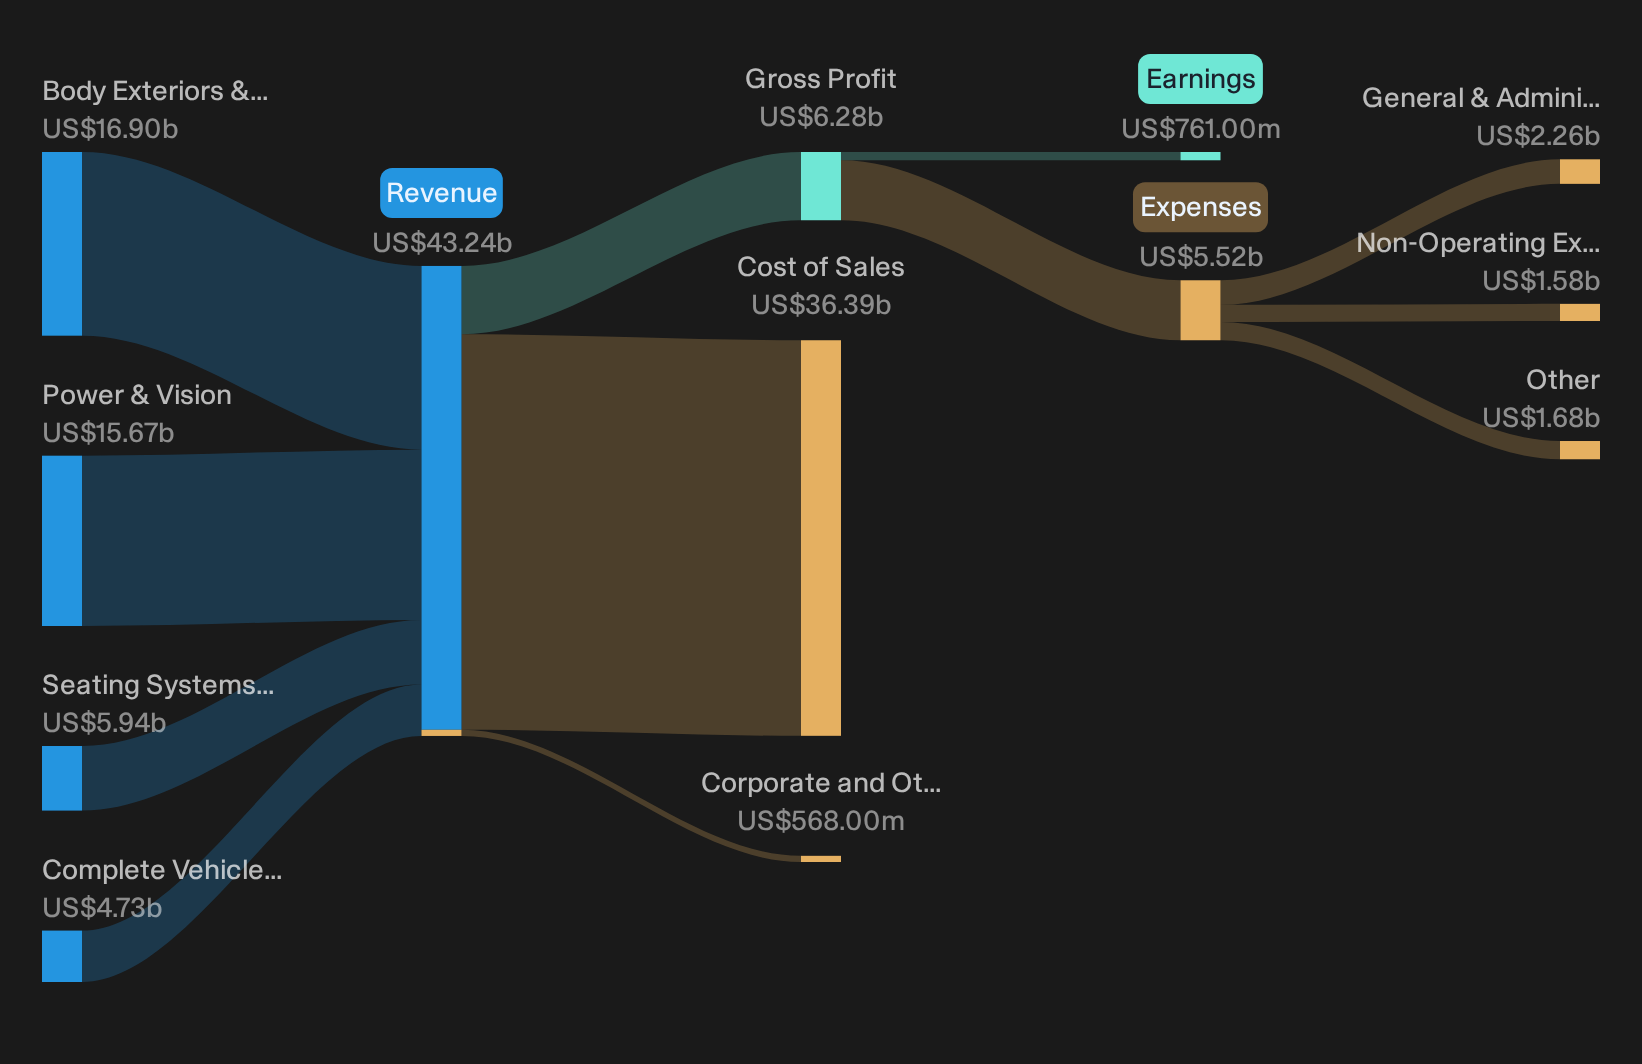
Magna generates US$16.9b from Body Exteriors & Structures, US$15.7b from Power & Vision, US$5.9b from Seating Systems, and US$4.7b from Complete Vehicles, and has a market value around CA$24.7b.
Magna International matters for a dividend screen like this because steady contracts across combustion, hybrid, and EV platforms can translate into recurring cash flows, which in turn support regular payouts when management keeps costs and capital spending under control.
"Magna International is focusing on operational excellence and restructuring actions, which are expected to result in meaningful margin expansion over the next two years. This is likely to positively impact net margins and earnings."
What really decides how comfortable you feel with that 3% yield is how one unresolved pressure on profitability and cash generation ultimately lands.
That unresolved pressure is exactly why the full narrative for Magna International examines whether margin expansion can separate Magna International's payout strength from auto cycle swings.
Canadian Tire Corporation (TSX:CTC.A)
Canadian Tire Corporation ties a 3%+ dividend yield to everyday shopping, financial products, and a real estate arm where CT REIT’s Canadian Tire anchored properties provide rental income that helps support regular payouts, in addition to the much larger retail and credit businesses.
Canadian Tire Corporation generates about CA$14.9b from Retail, CA$1.6b from Financial Services, and CA$618 million from CT REIT, and has a market value near CA$10.7b.
For a Dividend Powerhouses screen built around well covered, predictable payouts, Canadian Tire Corporation brings a blend of wide reach on store shelves, a credit card book tied to loyal shoppers, and a property trust that feeds rental income into the dividend story.
"The wider rollout of AI pricing and customer analytics tools, such as the platforms used to shape promotions and category occasions, is expected to influence assortment, promo intensity and regular pricing in ways that support gross margin and earnings quality."
What ultimately anchors that payout is whether one quiet shift in how profit is earned outpaces the rising pressure from leverage and thinning margins.
When that quiet shift in profit drivers matters to you, the full narrative for Canadian Tire Corporation shows where Canadian Tire Corporation’s earnings mix might be accelerating or masking risk.

Seeking Alternatives Beyond Dividend Powerhouses?
Fresh ideas move first. Breakout stories, quiet momentum, and sectors flying under the radar for now often get caught late. Scan them while it matters and get in early.
- Spot early strength in resilient businesses before momentum headlines hit by running the 8 resilient stocks with low risk scores that filter for staying power when conditions shift.
- Hunt for potential upside in under-followed operators by scanning the 10 high quality undiscovered gems that highlight quality fundamentals before they stop looking overlooked.
- Ride key infrastructure themes instead of chasing crowded trades by reviewing the 42 power grid technology and infrastructure stocks shaping how energy networks and grid technology are being upgraded worldwide.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com