
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Telefonaktiebolaget LM Ericsson (OM:ERIC B) Following Q3 Beat And Reorganization Still Looks Fully Valued
Telefonaktiebolaget LM Ericsson (OM:ERIC B) just released a busy Q3 2026 update, pairing better than expected earnings and organic sales growth with a wide ranging global reorganization aimed at sharpening its enterprise focus.
The recent Q3 announcement, global reorganization plans and SEK 8.1b buyback help explain why momentum in Telefonaktiebolaget LM Ericsson has picked up, with a 19.65% year to date share price return and a 138.22% three year total shareholder return pointing to building optimism around the longer term story.
Scan Ericsson’s Q3 re-rating against peers by checking which other telecom and 5G infrastructure stocks are showing similar momentum in the curated 55 AI infrastructure stocks today.
Telefonaktiebolaget LM Ericsson now pairs a global 5G footprint with a fresh restructuring and a buyback-fueled share price jump. The real tension for investors sits in the tag on that story. Does the current valuation still make sense?
Most Popular Narrative: 9% Overvalued
At a last close of SEK105.65 against a narrative fair value of SEK96.53, Telefonaktiebolaget LM Ericsson is priced above the most followed valuation view. This view leans heavily on margins, cash conversion and capital returns rather than blue sky 5G hopes.
The capital allocation framework that combines increased dividends, a share buyback program of up to SEK 15b and continued R&D spending, funded by free cash flow of SEK 26.8b in 2025 and a sizable net cash position, sets up future earnings per share and equity value outcomes that depend on how consistently Ericsson can convert margins into cash.
See why 30 investors see Telefonaktiebolaget LM Ericsson as 9% overvalued.
Result: Fair Value of SEK96.53 (OVERVALUED)
Still, the Ericsson story can break if operator spending stays cautious or if the loss making Enterprise unit drags group margins lower for longer.
Find out about the key risks to this Telefonaktiebolaget LM Ericsson narrative.
Another View: What Telefonaktiebolaget LM Ericsson’s P/E Is Really Pricing In
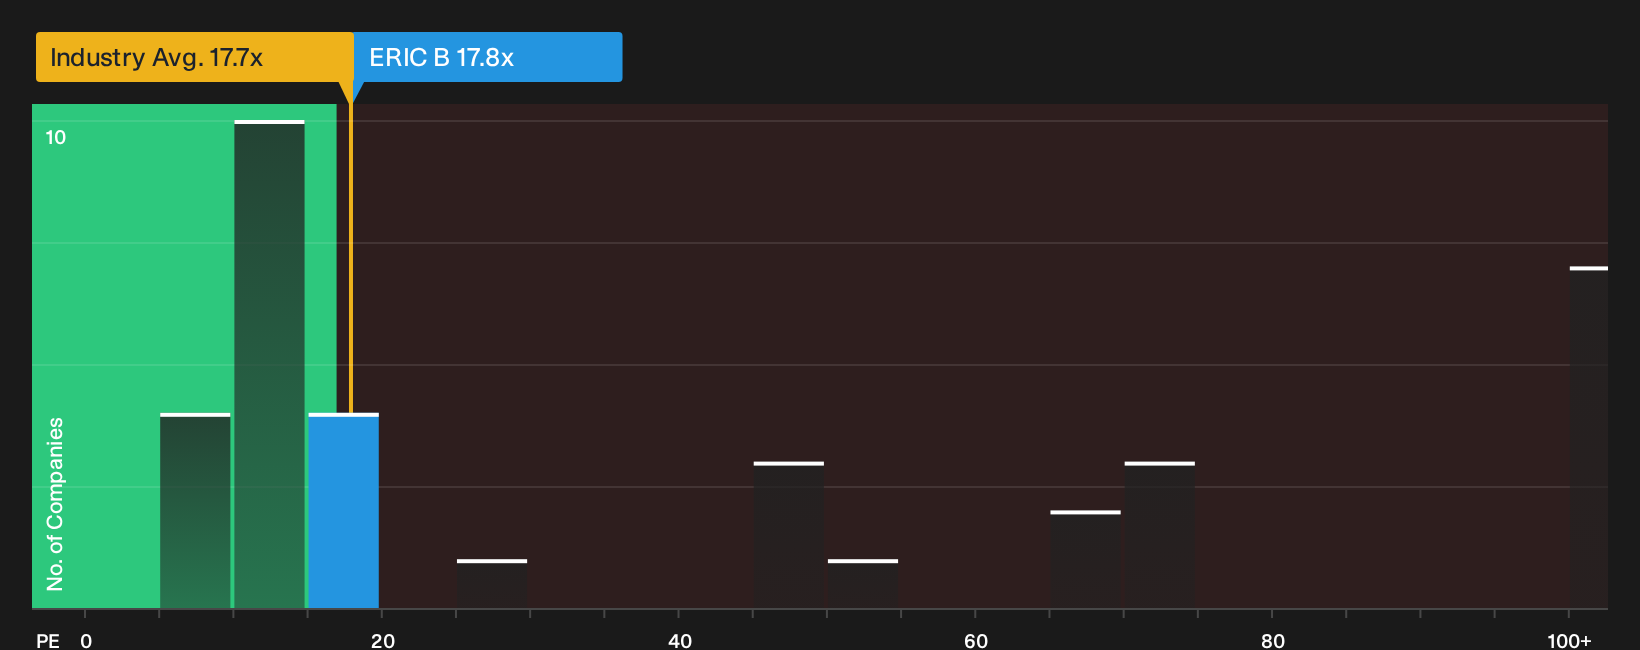
The user narrative tags Ericsson as 9% overvalued at SEK105.65. Yet on a simple P/E snapshot of 17.8x, the stock trades well below the peer average of 37x and beneath an estimated fair ratio of 23.6x. That gap points to a clear question for investors: Is the concern about execution and slower growth already baked into the price, or is the discount there for a reason?
To see how that trade off looks through a different lens, take a closer look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If sentiment on Telefonaktiebolaget LM Ericsson feels mixed, that is the point. The data shows both real concerns and meaningful positives. Take a few minutes to weigh both sides, then ground your own stance in the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Telefonaktiebolaget LM Ericsson?
If you only stop at Ericsson, you risk missing other compelling setups where quality, value and resilience come together in very different ways.
- Target robust cash generators by scanning a 189 high quality undervalued stocks that combine dependable fundamentals with prices that sit below their assessed worth.
- Secure your income stream by reviewing 215 dividend fortresses built around companies that pair higher yields with an emphasis on sustainability.
- Dial down portfolio stress by focusing on a 234 resilient stocks with low risk scores that highlights businesses with stronger balance sheets and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com