
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Vulcan Materials (VMC) Still Below Fair Value As Its Dividend Rises?
Vulcan Materials (VMC) put income back in focus after declaring a quarterly cash dividend of $0.52 per share, payable on November 24, 2026, to shareholders of record on November 9.
The dividend decision comes after a choppy stretch for Vulcan Materials, with the share price gaining 2.07% in the last session and 6.98% over 30 days but declining 8.19% across three months. The stock still shows a 44.79% five-year total shareholder return, which contrasts with the weaker 1-year total shareholder return of 12.12%.
Compare Vulcan Materials with other income-focused construction and infrastructure plays by scanning a curated group of 8 dividend fortresses that pair yield with scale.
After a sharp 30 day rebound but a weaker 1 year return, Vulcan Materials now offers a richer income stream and a higher share price. Investors may ask whether that mix still leaves enough potential upside to compensate for the risks buyers take here.
Most Popular Narrative: 17% Undervalued
On the latest numbers, Vulcan Materials closed at $257.63 against a widely followed fair value estimate of about $311 per share. This frames the new dividend in the context of a stock already seen as discounted by that narrative.
The company's footprint in growing Sunbelt metros continues to line up with a visible pipeline of large public and private projects, including a large volume of data centers and related power and LNG work, where about 60% of all large projects are within 50 miles of a Vulcan facility. This proximity can support future aggregates shipments and earnings as those projects move from award to steady production.
See why 13 investors see Vulcan Materials as 17% undervalued.
Result: Fair Value of $311 (UNDERVALUED)
Still, that undervalued story can crack if diesel driven cost pressure persists, or if weaker government spending and housing temper aggregates demand more than analysts currently assume.
Find out about the key risks to this Vulcan Materials narrative.
Another View: What Vulcan Materials' P/E Suggests
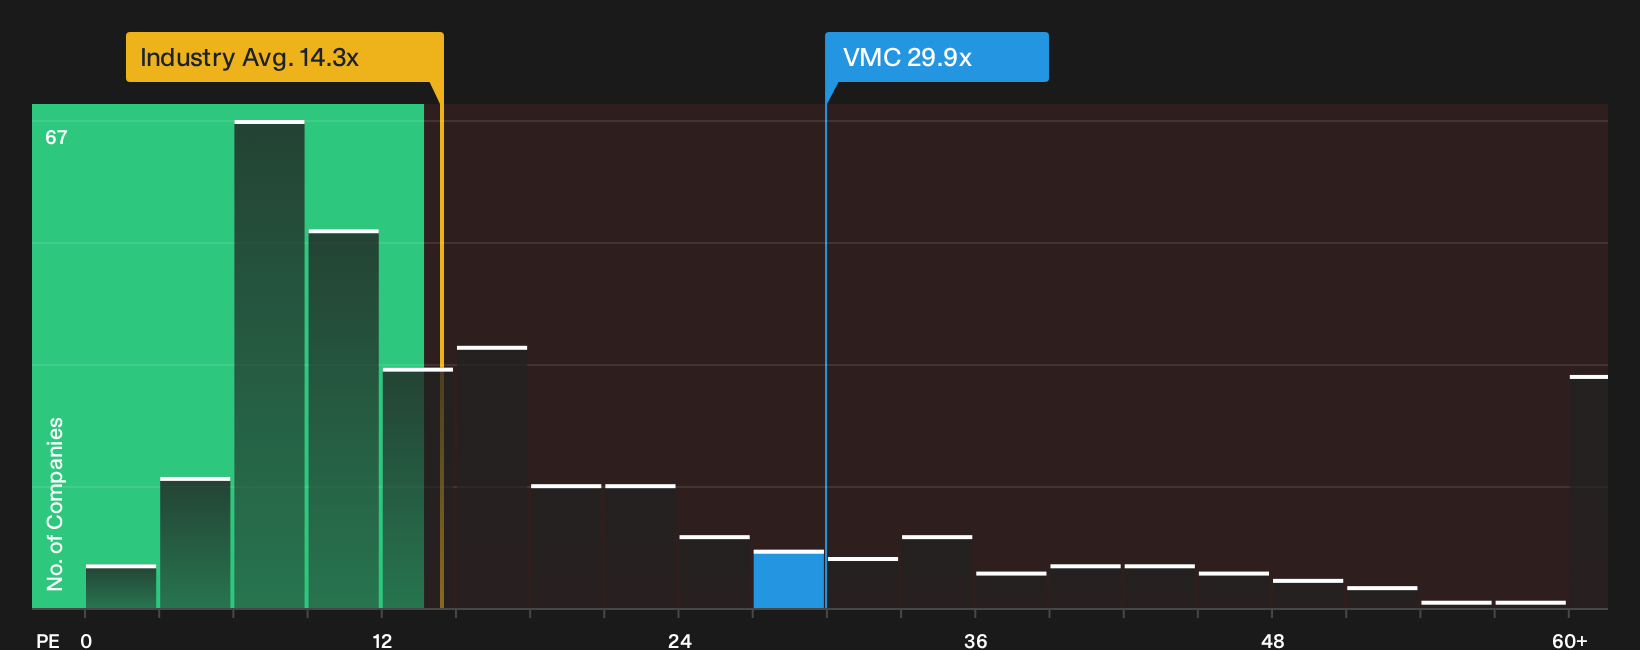
While the popular story frames Vulcan Materials as undervalued against a $311 fair value, the P/E ratio tells a tougher story. The stock trades at about 29.9x earnings, compared with roughly 14x for the global Basic Materials group and about 21.6x for peers, and a fair ratio closer to 19.9x.
That gap means investors are already paying a premium for VMC's earnings, even though the fair ratio points to a lower multiple the market could move toward over time. The key question is whether the earnings profile and growth outlook justify staying at the high end of the range, or whether that premium itself becomes a risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages so far, right, with Vulcan Materials showing both pressure points and bright spots in the story. Act while the data is fresh in your mind and weigh the 3 key rewards and 2 important warning signs.
Looking for more Vulcan Materials investment ideas?
Do not stop your research with Vulcan Materials. Broaden your watchlist now so you can spot opportunities faster and avoid reacting after prices have already moved.
- Target stronger value potential by scanning a curated pool of 33 high quality undervalued stocks that combine quality fundamentals with more modest pricing.
- Prioritise financial resilience and review a list of solid balance sheet and fundamentals (25 results) that can help steady your portfolio when conditions get choppy.
- Hunt for tomorrow's outperformance candidates by checking a focused list of 20 high quality undiscovered gems backed by solid underlying numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com