
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Park National (PRK) Following Fresh Undervaluation Talk Is Back On Investors’ Radar
Why fresh undervaluation talk is putting Park National back on investors’ radar
Recent analysis suggesting Park National (PRK) may trade below its estimated intrinsic value has pulled fresh attention to the bank, with investors weighing how sustainable earnings and returns on capital support that view.
Park National’s share price has eased over the past month, with a 30-day share price return of 2.57% and a 90-day share price return of 4.65% down from its recent levels. The stock holds a 15.77% year to date share price gain and a 3-year total shareholder return of 109.32%, which points to longer term momentum that now intersects with renewed undervaluation debate at the current US$178.65 level.
Compare Park National’s valuation story with a curated set of other potential value ideas in the banking space by scanning the 33 high quality undervalued stocks.
After a strong multi year run and a recent pause around US$178.65, investors are weighing a simple tension around Park National. Is most of the value already captured in the price, or does meaningful upside still sit in the valuation work?
Price-to-earnings of 17x for Park National: Is it justified?
Park National’s valuation conversation starts with a simple comparison. The stock trades on a P/E of 17x while the US Banks industry sits at 11.5x and peer averages sit around 14.2x, so the market is clearly paying a premium for this ticker.
The P/E ratio tells you how much investors are currently paying for each dollar of earnings. For a regional bank like Park National, that figure often reflects expectations around earnings stability, loan quality, and how smoothly management converts revenue into profits.
Earnings growth offers one clue. Profit has grown 3.4% per year over the past 5 years, with a faster 13.8% expansion over the last year, and earnings are forecast to grow 11.1% per year. That is growth, but the pace trails both the broader US market and the Banks industry, and current net profit margins of 31.3% are slightly lower than last year’s 31.5%. Combined, this suggests the higher multiple asks investors to pay up for consistency and high quality earnings rather than outsize expansion.
The premium looks even steeper when set against an estimated fair P/E of 12.5x. Compared with that reference point, Park National screens as expensive, and the gap points to a level the valuation could gradually move toward if optimism around its earnings profile cooled.
Explore the SWS fair ratio for Park National.
Result: Price-to-earnings of 17x (OVERVALUED)
Still, a 17x P/E and a value score of 2 could face pressure if annual net income growth of 11.13% or revenue trends slip from current levels.
Find out about the key risks to this Park National narrative.
Another view on Park National’s valuation
The P/E premium presents Park National as expensive, yet the SWS DCF model tells a very different story. On that cash flow view, the shares at $178.65 trade about 29.4% below an estimated fair value of $253.11, which presents the stock as undervalued. Which lens is more useful when earnings quality appears solid but growth is not rapid?
Look into how the SWS DCF model arrives at its fair value.
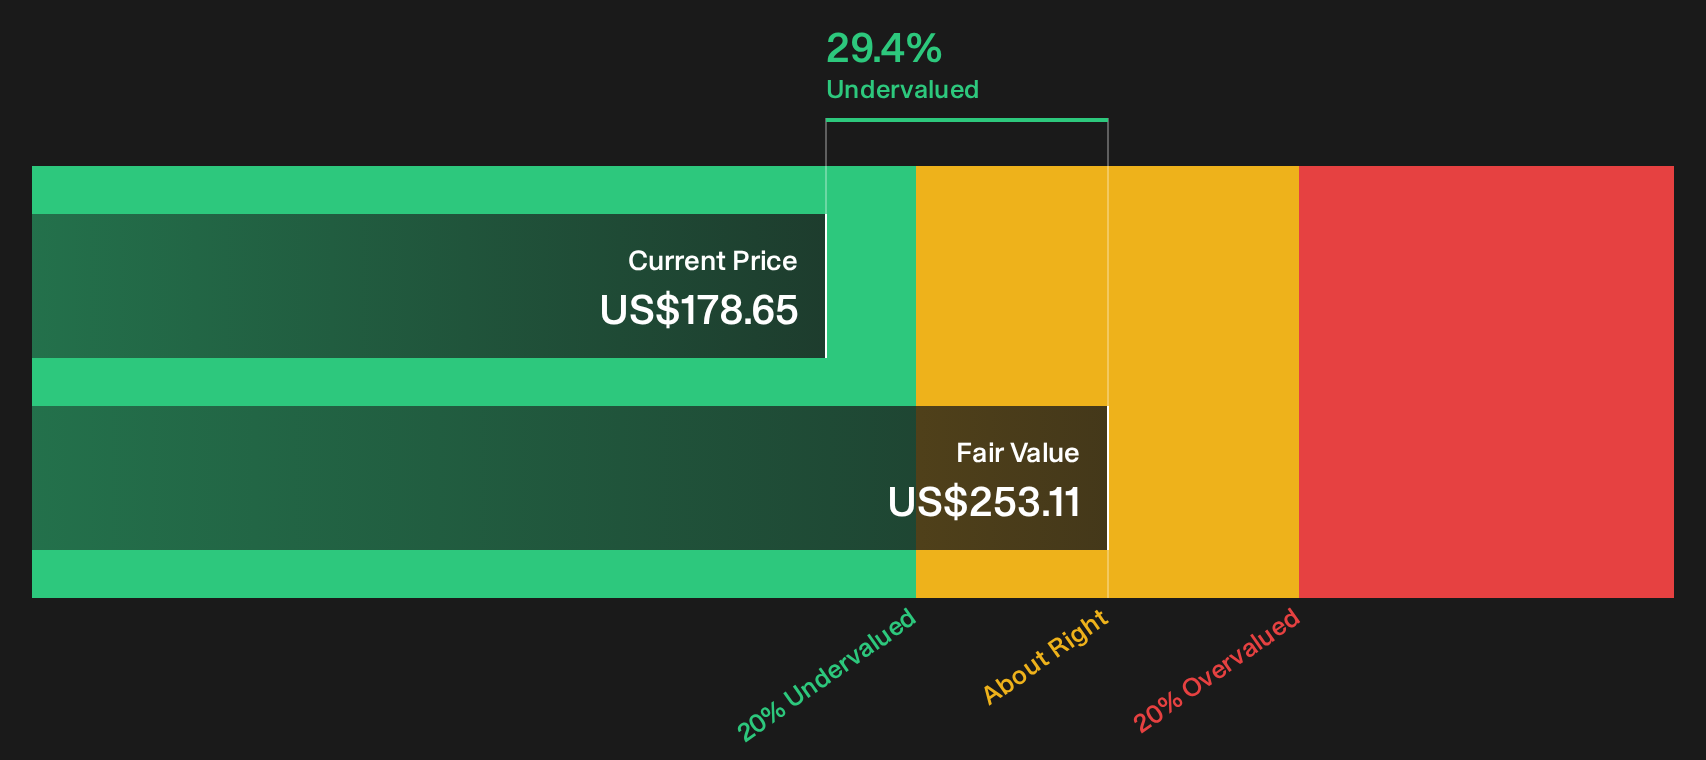
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Park National for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of premium multiples and discount signals around Park National leaves you on the fence, move quickly and inspect the underlying drivers yourself. Then compare those numbers with the 4 key rewards.
Looking for more Park National investment ideas?
If Park National has sharpened your thinking on value, do not stop here. Use focused screeners to surface other candidates that match your preferred mix of quality, risk, and income.
- Target potential mispricing by scanning a curated pool of quality companies that still look attractively valued through the 33 high quality undervalued stocks.
- Strengthen capital preservation by filtering for companies with balance sheets that can better handle stress using the list of solid balance sheet and fundamentals (25 results).
- Spot early-stage opportunities with robust fundamentals before the crowd pays attention by reviewing the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com