
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Nordic American Tankers (NAT) Could Be 13% Overvalued After A 155% TSR Run
Nordic American Tankers (NAT) has drawn fresh attention after recent trading left the share price at US$7.66. The tanker operator’s longer term return profile is sharply different from its weaker recent performance.
Over the past week the share price has retreated, with a 7 day share price return of down 9.6% and a 30 day share price return of down 7.2%. However, Nordic American Tankers still shows strong momentum in the bigger picture, with a 90 day share price return of 24.4% and a 1 year total shareholder return of 154.8% supported by dividends.
Scan beyond Nordic American Tankers and compare this recent surge with 33 high quality undervalued stocks, which pair healthier balance sheets with stronger valuation checks.
The share price has already traveled a long way, while near-term returns have cooled and analyst targets now sit slightly below the market. Does the current balance of risk and reward in Nordic American Tankers still justify fresh money?
Price-to-Earnings of 13.1x: Is it justified?
Nordic American Tankers trades on a P/E of 13.1x, which puts the recent US$7.66 share price on a lower earnings multiple than the broader US market but above the level suggested by several fair value checks.
The P/E ratio compares what investors are paying for each dollar of current earnings, and it is widely used for profitable shipping and energy businesses like Nordic American Tankers. A lower multiple can signal a more cautious view of future profits, while a higher figure often reflects optimism that current earnings can be sustained or improved.
Against direct peers, the picture looks supportive. The current 13.1x P/E is well below the peer average of 29.4x, which points to the market assigning a cheaper earnings tag to Nordic American Tankers than similar tanker operators. At the same time, the ratio is slightly higher than the US Oil and Gas industry average of 12.5x and well above the estimated fair P/E of 8.9x that the SWS model suggests the valuation could move toward. As a result, the current rating carries a clear premium to that fair ratio benchmark.
Explore the SWS fair ratio for Nordic American Tankers.
Result: Price-to-Earnings of 13.1x (OVERVALUED)
Still, the annual declines in revenue and net income, combined with a share price now above the average analyst target, could quickly challenge the bullish Nordic American Tankers story.
Find out about the key risks to this Nordic American Tankers narrative.
Another View: What The SWS DCF Model Says
Price multiples paint Nordic American Tankers as expensive relative to the SWS fair ratio, yet the story tightens when cash flows are modeled directly. Our DCF model points to a fair value of about $6.77 per share, below the current $7.66, which implies limited room for error if tanker earnings soften.
That kind of gap can matter when the cycle turns, especially for a business exposed to shipping rates and with forecasts pointing to declining revenue and profit. Look into how the SWS DCF model arrives at its fair value.
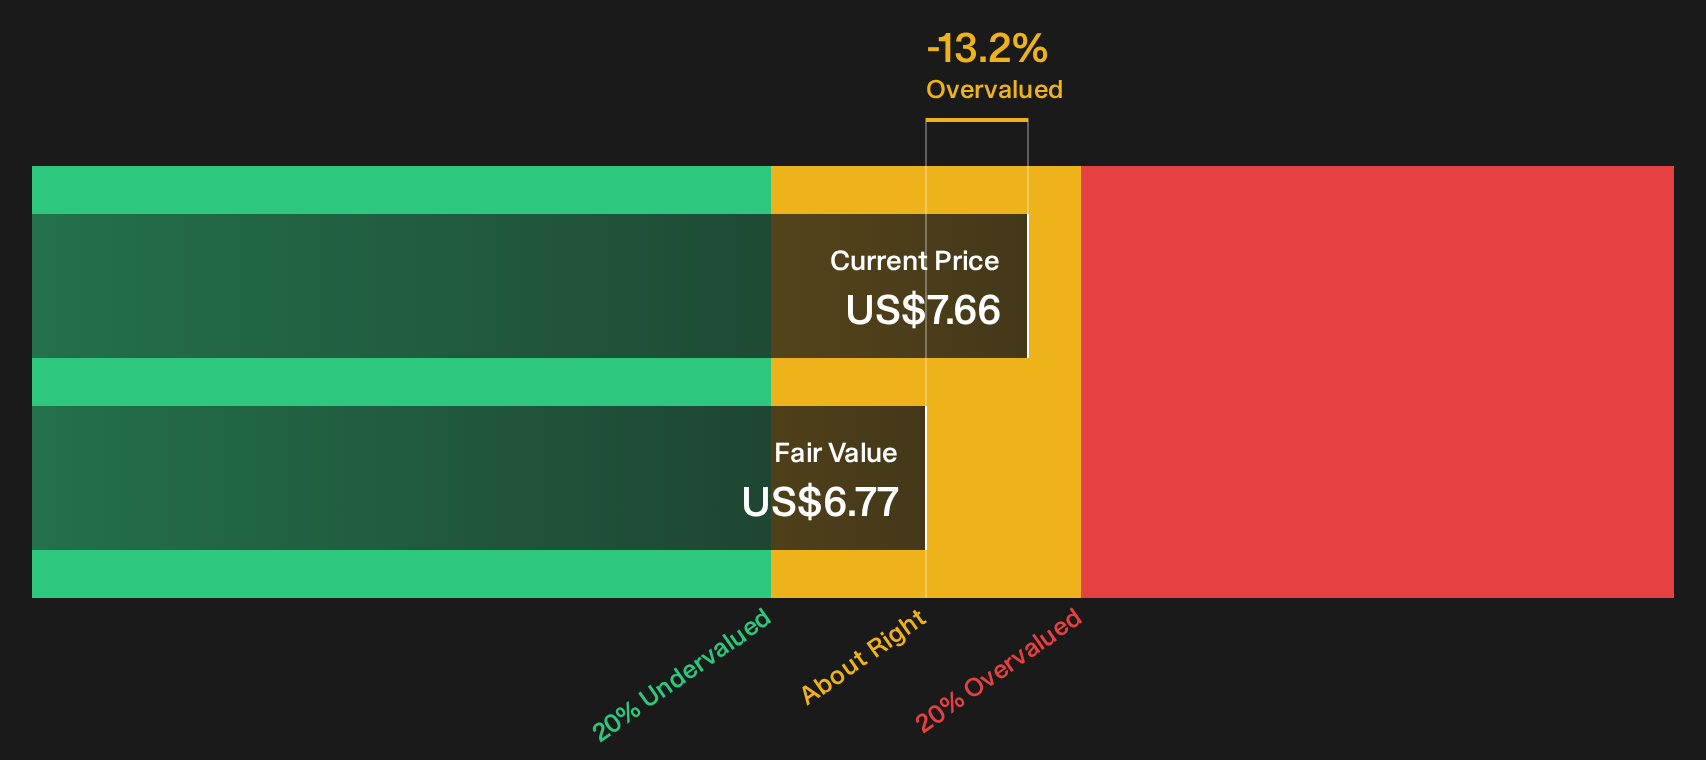
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nordic American Tankers for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Nordic American Tankers can make the picture feel murky, so move fast, review the underlying data, and weigh both sides using the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Nordic American Tankers?
Do not stop at Nordic American Tankers when there are tools built to help you quickly filter for quality, value and resilience across the market.
- Target durable compounding by scanning companies with reliable balance sheets and fundamentals using our list of solid balance sheet and fundamentals (25 results).
- Spot potential mispricings before the crowd by running through the 20 high quality undiscovered gems.
- Focus on stability and capital preservation by checking businesses that screen well in the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com