
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Avolta (SWX:AVOL) Wins Seattle Airport Contract, Is The Stock Still Undervalued?
Avolta (SWX:AVOL) is back in focus after subsidiary Hudson secured a new 20-year duty-free contract at Seattle-Tacoma International Airport, extending the retailer across multiple concourses at the busy US hub.
Recent trading has been choppy. Avolta’s share price is at CHF44.2 after a 5.0% gain over the past week and a 5.6% 1 month share price return. However, the 90 day move is down 6.2%. At the same time, the 3 year total shareholder return of 54.7% and 1 year total shareholder return of 8.8% point to longer term momentum that this Seattle contract could help investors focus on again.
Scan beyond Avolta and this Seattle win by reviewing 614 high quality undiscovered gems that could be building similar long-term contracts away from the market spotlight.
Avolta now trades around CHF44.2 after the Seattle contract bump, so the puzzle for investors is whether that recent strength still leaves enough potential to justify the risk once the numbers are evaluated.
Most Popular Narrative: 15% Undervalued
Avolta’s widely followed valuation narrative points to a fair value of CHF51.94 versus the last close at CHF44.2, so the Seattle contract arrives on top of an existing gap that analysts have already tried to frame with detailed growth and risk assumptions.
Expansion into high-growth markets, particularly Asia-Pacific and the Middle East, is expected to increase Avolta's exposure to rising air travel volumes and international passenger flows, thus supporting sustained revenue growth and diversifying earnings streams.
The strong consumer shift toward premium, experiential, and localized travel retail (as seen in high-margin products, flexible "sense of place" stores, and hybrid F&B/retail formats) is anticipated to drive higher average transaction value and support margin expansion.
See why 10 investors see Avolta as 15% undervalued.
Result: Fair Value of CHF51.94 (UNDERVALUED)
Still, this upbeat Avolta story can unravel if geopolitical shocks disrupt passenger flows again, or if rising competition for key airport concessions squeezes margins harder than analysts expect.
Find out about the key risks to this Avolta narrative.
Another View: Avolta Looks Expensive On Earnings
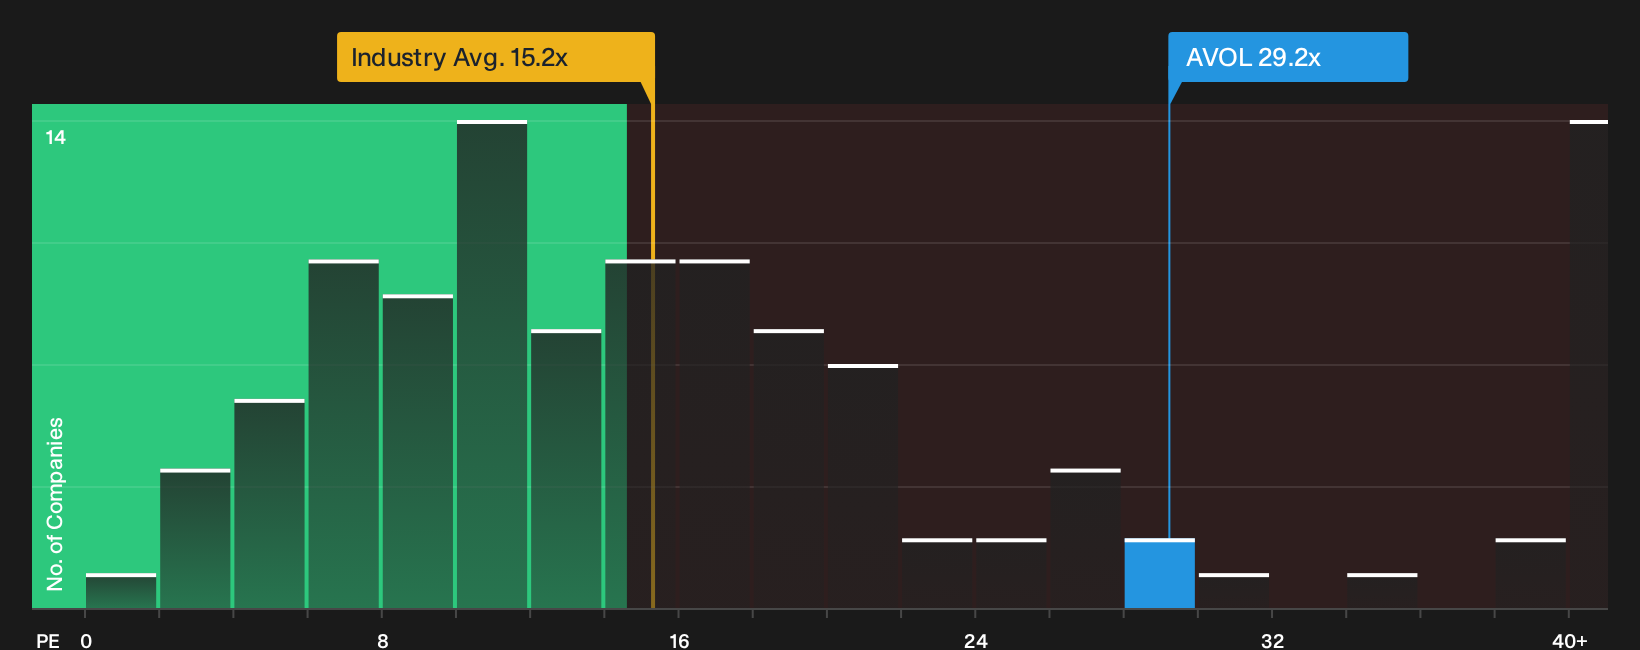
A second lens on Avolta comes from its P/E. The shares trade on about 29.2x earnings, while the European Specialty Retail group sits near 15.2x and close peers around 17x. That is a steep premium. The question is whether current execution justifies paying almost double.
This richer earnings multiple carries valuation risk if growth or margins soften, so it helps to stress test your own expectations against the detailed ratio work in our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Avolta for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 189 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of enthusiasm and caution around Avolta leaves you undecided, consider moving quickly. Stress test the data yourself, then weigh 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Avolta?
Do not stop with one contract story. Use the Simply Wall St screener to line up fresh opportunities before the crowd catches on and prices adjust.
- Target potential mispricings by scanning a 189 high quality undervalued stocks that already combine stronger fundamentals with more modest expectations.
- Strengthen your downside protection by shortlisting a 234 resilient stocks with low risk scores that score well on resilience and capital preservation measures.
- Build a core watchlist around balance sheet resilience by reviewing a list of solid balance sheet and fundamentals (204 results) that merit a closer look when markets turn volatile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com