
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is IntegraFin Holdings (LSE:IHP) Undervalued As Results And Trading Update Raise New Questions?
IntegraFin Holdings (LSE:IHP) drew fresh attention after releasing its latest results and trading update. The share price moved lower while financial sector earnings were in focus across the market.
Over the past year, IntegraFin Holdings has delivered a 9.12% total shareholder return, helped by a 6.28% year to date share price gain. More recent momentum has softened, with the 90 day share price return declining 4.61% as investors reassess risk and growth expectations after the latest update.
Scan how IntegraFin Holdings compares with other financials reacting to earnings season shocks by running the 7 high quality undervalued stocks for ideas that combine quality with potential mispricing.
IntegraFin Holdings now sits between two stories. Recent gains and the latest pullback are on the table already, so how much of the upside case still belongs to new buyers rather than early entrants?
Most Popular Narrative: 17% Undervalued
The prevailing narrative values IntegraFin Holdings at £4.48 per share versus a last close of £3.73. This puts the spotlight firmly on what is driving that gap rather than on short term price swings.
Ongoing digitalization and platform enhancements, including straight through processing and improved API integration, are expected to further improve efficiency and service quality, leading to potential revenue growth and higher profit margins. The group's unique advantage of using proprietary technology allows quick adaptation to regulatory and legislative changes, potentially strengthening its competitive edge and aiding in client and adviser retention, boosting FUD and revenue growth.
See why 6 investors see IntegraFin Holdings as 17% undervalued.
Result: Fair Value of £4.48 (UNDERVALUED)
Still, the IntegraFin Holdings story can change quickly if planned price cuts weigh on revenue, or if higher admin costs squeeze margins more than expected.
Find out about the key risks to this IntegraFin Holdings narrative.
Another View: IntegraFin Holdings Through Its P/E Ratio
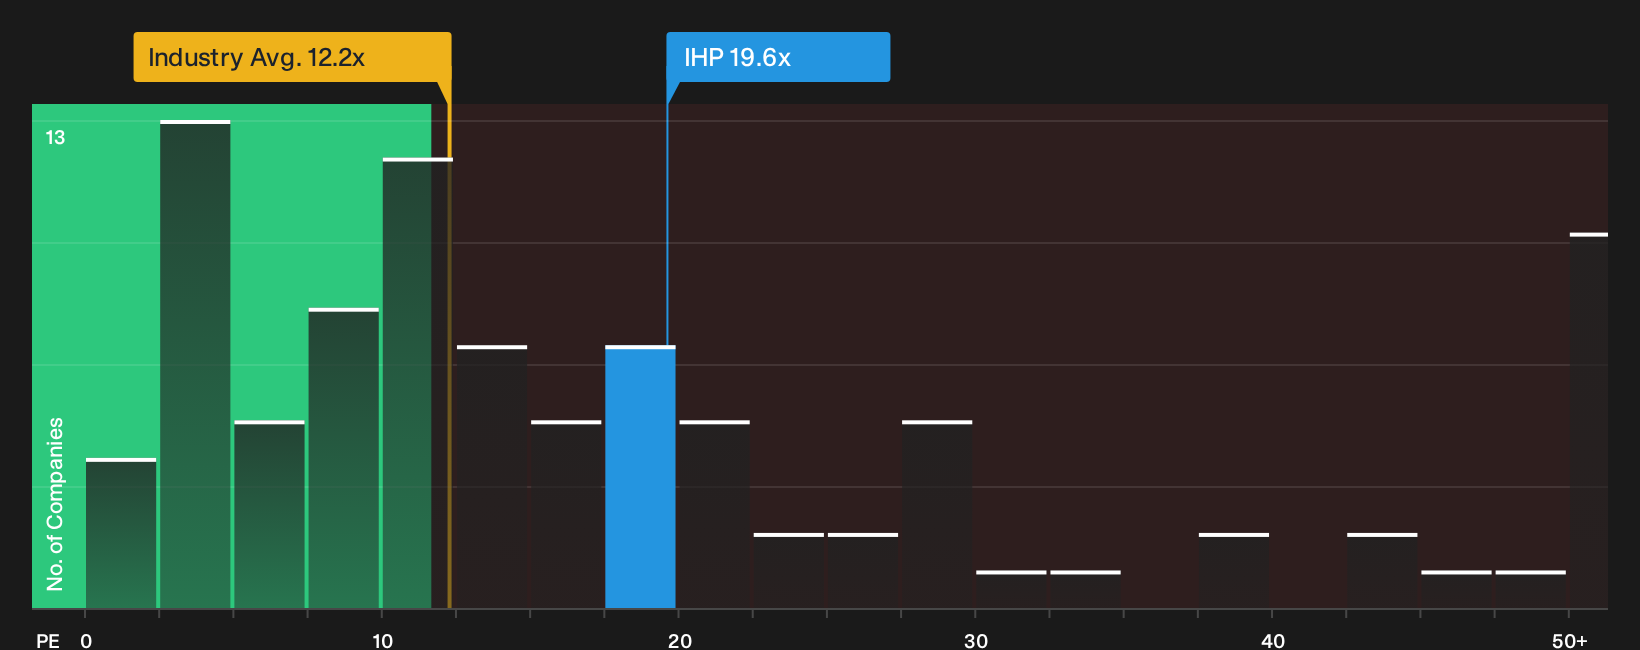
The first story casts IntegraFin Holdings as undervalued, yet the current P/E of 19.6x tells a less relaxed story. That multiple is above the UK Capital Markets sector on 12.2x and above a fair ratio of 13x, even though it sits just below close peers at 20.1x.
Paying more than the wider industry and above the fair ratio means less room for error if forecasts disappoint. At the same time, trading near peer levels suggests the market already prices in much of the quality case. The key question is whether you see that premium as justified or as your margin of risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the mixed messages around IntegraFin Holdings and its recent valuation story? Act while the data is fresh by weighing both the upside and the concerns through the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond IntegraFin Holdings?
Use the Simply Wall St screener to widen your opportunity set beyond IntegraFin Holdings and make sure you are not leaving potential ideas on the table.
- Target dependable cash generators by reviewing companies with strong payouts and resilience through the 2 dividend fortresses.
- Hunt for mispriced quality by scanning for financially healthy businesses that appear cheap on key metrics using the 7 high quality undervalued stocks.
- Prioritise capital protection by focusing on resilient companies with measured risk profiles through the 4 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com