
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Clean Harbors (CLH) Funds Acquisitions With $600 Million Notes, Is The Stock Fully Valued?
Clean Harbors (CLH) has raised US$600 million through 6.250% senior notes due 2034, using most of the cash to fund its EnviroServe and ES&H environmental services acquisitions.
Clean Harbors shares trade at US$320.06, and the 31.47% year to date share price return sits alongside a 34.93% 1 year total shareholder return and 178.85% 5 year total shareholder return, indicating momentum that has been building rather than fading.
Compare Clean Harbors' acquisition driven momentum with a hand picked 20 high quality undiscovered gems that also pair solid fundamentals with under the radar growth stories.
Clean Harbors has already rewarded investors with strong multi year returns and a sharp move this year. The key question now is whether the current price still offers meaningful upside, or if most of the gain is already in the rearview mirror.
Most Popular Narrative: 9% Undervalued
The narrative fair value for Clean Harbors sits at $350.00 against a last close of $320.06, which implies some remaining upside based on that framework and emphasizes the quality of its infrastructure moat.
The company benefits from several long-term growth drivers, including industrial expansion, stricter environmental regulations, PFAS remediation, limited disposal capacity and strategic acquisitions.
While parts of the business remain economically sensitive and the company is certainly not recession-proof, its essential services, recurring customer relationships and regulatory importance make it considerably more resilient than many traditional industrial companies.
See why 2 investors see Clean Harbors as 9% undervalued.
Result: Fair Value of $350.00 (UNDERVALUED)
Still, Clean Harbors’ story can be tested if environmental rules soften or if acquisition integration stumbles and erodes the moat that investors are paying for.
Find out about the key risks to this Clean Harbors narrative.
Another View: Clean Harbors Looks Pricey On Earnings
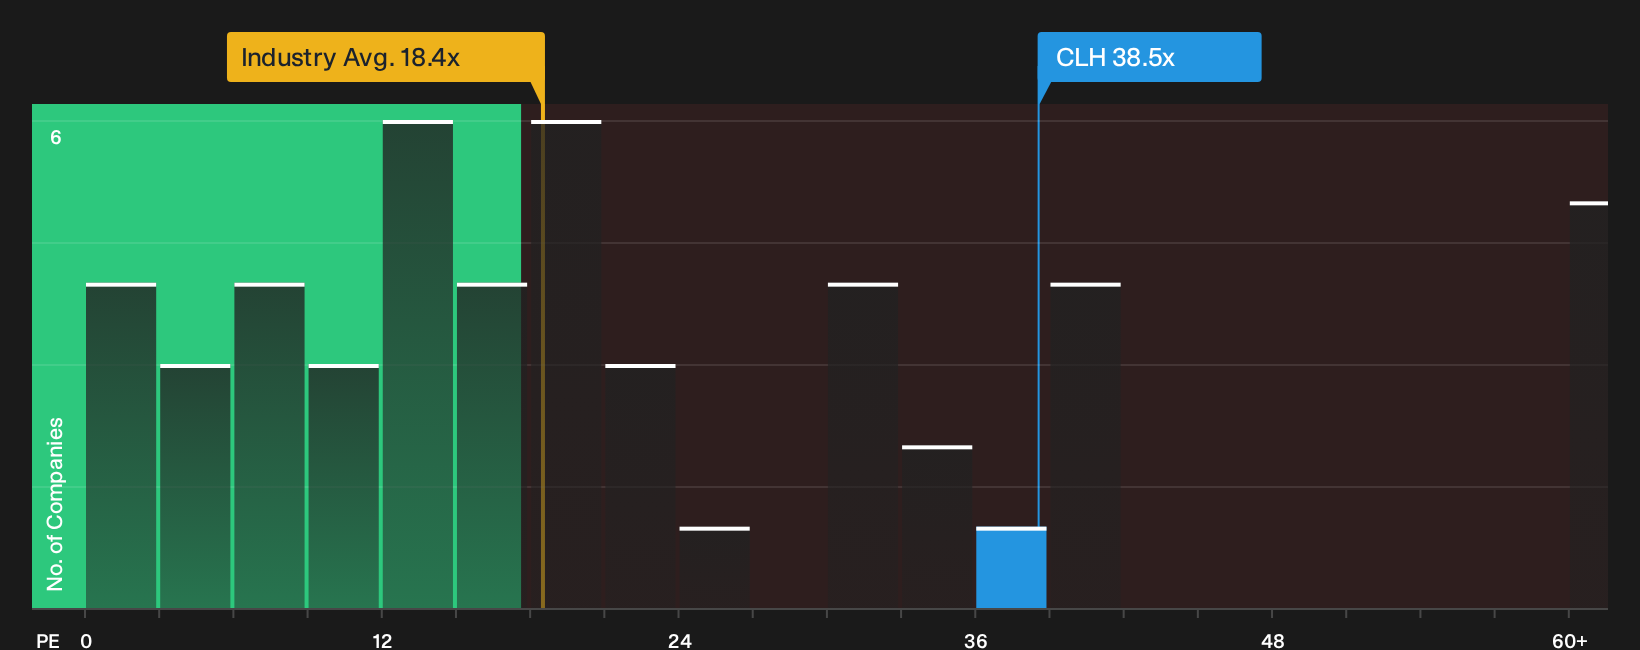
The narrative fair value points to upside, yet the simple earnings multiple tells a very different story. Clean Harbors trades on a P/E of 38.5x, against 18.4x for the US Commercial Services industry and 28.9x for peers, while the fair ratio sits at 21.2x. That gap suggests investors are paying a clear premium. Is that premium a cushion for quality or a source of downside risk if sentiment cools?
To see how this lofty earnings multiple fits into a fuller valuation picture, including how the market could move toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Confident about the story so far, or still on the fence about Clean Harbors? Take a closer look at both sides of the ledger with 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Clean Harbors?
Do not stop with Clean Harbors. Broaden your watchlist using focused screeners that surface quality, yield and resilience so you are not relying on a single story.
- Target potential mispricing by scanning a curated 33 high quality undervalued stocks that blend healthy balance sheets with attractive valuations.
- Strengthen your income stream by reviewing a hand picked 8 dividend fortresses that combine higher yields with business durability.
- Dial down portfolio shocks by filtering for 32 resilient stocks with low risk scores that show steadier fundamentals and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com