
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Infrastructure Shift At Fifth Third Bancorp Stock Has Changed Its Investment Story
- Fifth Third Bancorp’s wealth arm, Fifth Third Wealth Advisors, has shifted ultra-high-net-worth portfolios toward global infrastructure and real assets, emphasizing projects in transportation, utilities and digital networks.
- This tilt toward capital intensive infrastructure links client demand directly to themes such as digital transformation and supply chain redesign, which are closely related to Fifth Third Bancorp’s broader commercial and payments businesses.
- We will look at how Fifth Third Bancorp's investment narrative is shaped by this new tilt toward global infrastructure and real assets.
Fifth Third Bancorp Investment Narrative Recap
To own Fifth Third Bancorp, you need to believe it can turn a larger commercial footprint, deposit rich platforms and tech spending into durable earnings without eroding returns through higher funding costs or integration issues. The key near term swing factor is how quickly Comerica systems and teams settle, while deposit pricing pressure and competitive markets remain manageable.
The Darren King appointment looks important but does not change the near term thesis on its own. Execution risk still centers on keeping digital services reliable after the Comerica conversion and on offsetting any solar related fee pressure. If integration noise stays contained, investors are likely to refocus on efficiency, credit quality and deposit growth.
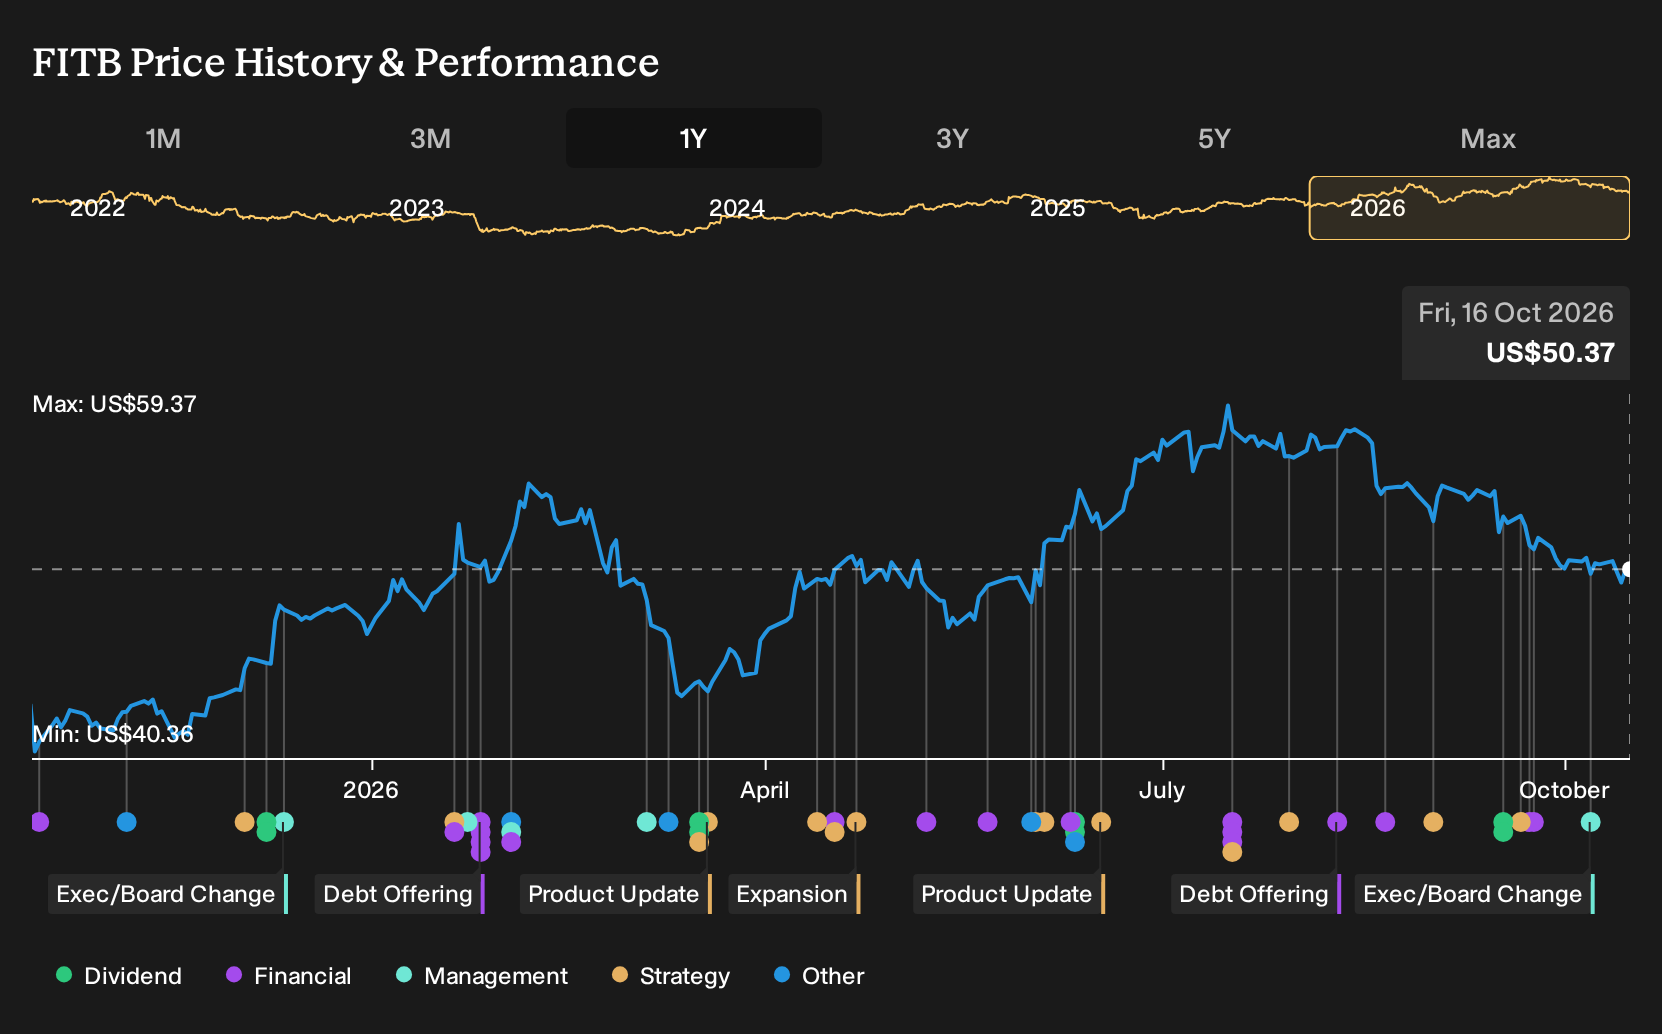
The most relevant development is Darren King being confirmed as head of the Commercial Bank, now including Regional Banking. That places a single leader over a business that has grown materially after Comerica and sits at the center of Fifth Third Bancorp’s lending, treasury, payments and wealth cross sell ambitions.
This matters for potential catalysts because a key upside case depends on capturing revenue and expense synergies from Comerica while keeping service issues and customer churn in check. A seasoned executive with broad prior banking roles could help align middle market coverage, specialty sectors such as Innovation Banking and treasury services with the technology and payments investments already underway.
Fifth Third Bancorp's narrative projects US$16.4b revenue and US$4.3b earnings by 2029. This aligns with analysts currently expecting 17.6% yearly revenue growth and an earnings increase of about US$2.1b from US$2.2b today.
Uncover why Fifth Third Bancorp's fair value indicates a 25% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community span roughly US$61.7 to US$96.9, so retail opinions on Fifth Third Bancorp already cover a wide band before Darren King’s appointment and the wealth arm’s infrastructure tilt are even factored in. Use that spread as a prompt to compare several alternative angles on future execution, deposit costs and tech spending discipline.
Explore 3 other Fifth Third Bancorp fair value estimates, including one that suggests it could be worth just $61.71!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Fifth Third Bancorp research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Fifth Third Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fifth Third Bancorp's overall financial health at a glance.
Looking for more investment ideas beyond Fifth Third Bancorp?
Once you have a view on Fifth Third Bancorp, it can help to compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you quickly scan the market using the same kind of fundamental filters used throughout this analysis.
- If capital preservation sits at the top of your list, start with a group of 32 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- For investors hunting for quality at a reasonable price, filter the market through a curated pool of 33 high quality undervalued stocks that pair solid fundamentals with appealing valuations.
- If income is your priority, focus your search on a hand picked set of 8 dividend fortresses that combine higher yields with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com