
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Toyota Motor (TSE:7203) Could Be 45% Overvalued As EV Manufacturing Plans Advance
Toyota Motor stock: buyback completion and new EV manufacturing push
Toyota Motor (TSE:7203) has just wrapped up a sizeable share repurchase and is preparing to retool its electric vehicle production with in-house gigacasting equipment at a planned Lexus plant in China.
The buyback update provides a fresh data point on how management allocates capital today. In addition, the gigacasting plan highlights how the automaker intends to build and price its next generation of EVs.
Recent trading has started to firm up. Toyota Motor’s 1-day share price return of 2.15% and 7-day share price return of 6.30% contrast with a year to date share price decline of 8.97%. At the same time, the 1-year total shareholder return of 8.86% and 5-year total shareholder return of 80.63% indicate a stronger longer term record despite periods of softer momentum.
The completed ¥195.0b buyback, the planned gigacasting rollout in China, and Toyota’s regulatory push in Europe all arrive as the stock resets from that weaker year to date share price performance. This can signal that investors are reassessing both growth potential and execution risks around the electric and zero emission transition story.
See how Toyota Motor compares with other automakers repositioning for EV efficiency and capital returns by running a focused screen on list of solid balance sheet and fundamentals (22 results)
Recent gains, a completed ¥195.0b buyback, and Toyota Motor’s EV manufacturing reset now meet a weaker year to date share price record. Does that mix still leave more upside potential than downside risk at today’s valuation?
Most Popular Narrative: 45% Overvalued
Toyota Motor last closed at ¥3,094, while the most followed narrative on the stock pins fair value closer to ¥2,137. That gap frames the current debate over whether recent buybacks and EV investments justify the price investors are paying today.
Today, Toyota retains its title as the world's largest automaker by sales volume. Its position is defined by several key aspects:
Leadership in Hybrids: The company controls over 40% of the global hybrid market, which remains the most sought-after transitional transport type in 2026.
See why 6 investors see Toyota Motor as 45% overvalued.
Result: Fair Value of ¥2,137.79 (OVERVALUED)
Still, the Toyota Motor narrative can crack if solid state battery progress stalls or if China-focused EV plants face regulatory or demand setbacks.
Find out about the key risks to this Toyota Motor narrative.
Another View: Toyota Motor valuation through earnings multiples
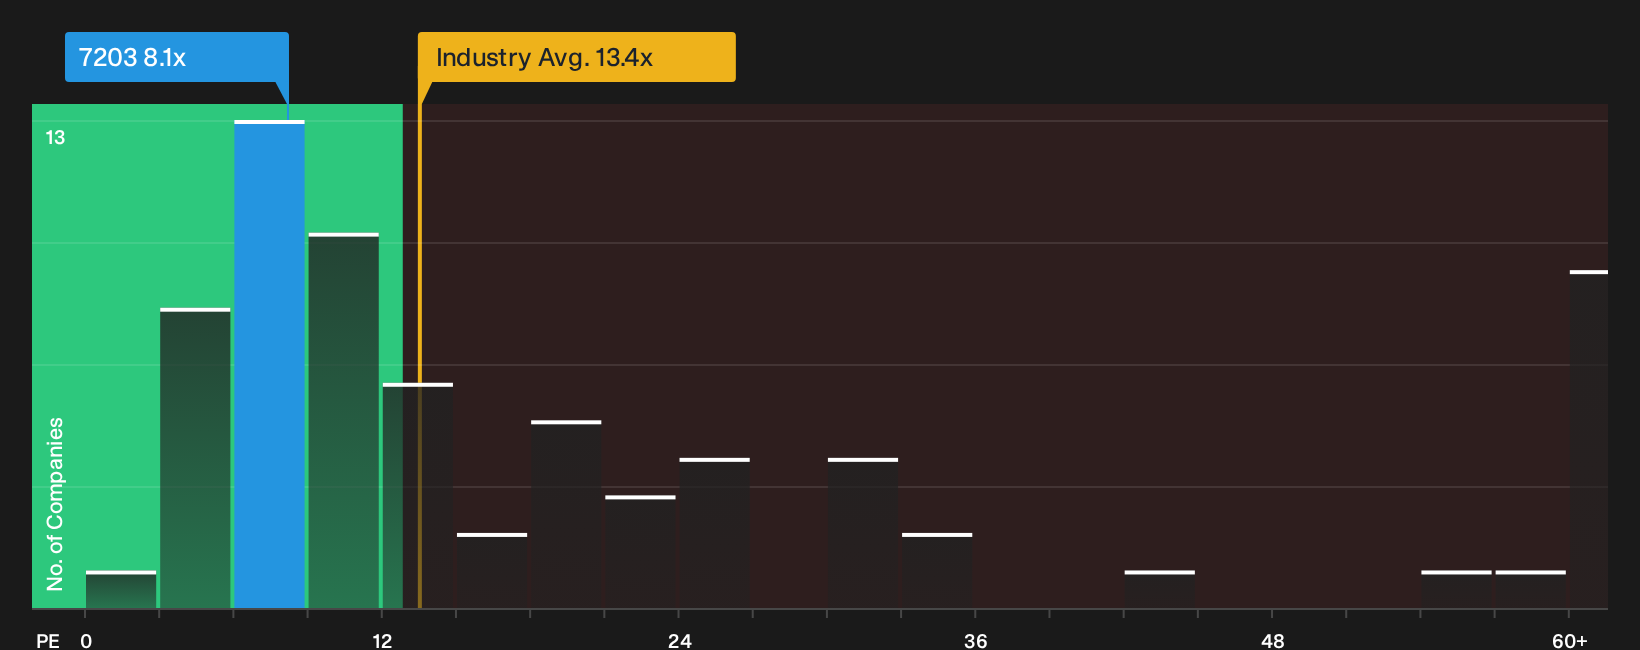
The narrative fair value of ¥2,137 sits well below Toyota Motor’s last close at ¥3,094. Yet on simple earnings metrics, the picture looks very different. The stock trades on a P/E of 8.1x, compared with 11.6x for peers and 13.4x for the wider Asian auto sector.
A fair ratio of 16.1x suggests the P/E could move closer to where similar businesses trade if sentiment or growth expectations shift. That gap cuts both ways. It can cushion downside if profit holds up, but it can also compress if investors decide they were paying too much for stability. Which signal do you trust more at today's price?
For a closer look at how these P/E gaps stack up against peers and the fair ratio, and what that might mean for valuation risk, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this combination of buybacks, EV plans and valuation signals seems confusing, do not stay undecided. Review the complete picture of risks and potential upside with 4 key rewards and 2 important warning signs
Looking for more Toyota Motor investment ideas?
You have seen how Toyota Motor is being weighed on valuation and EV plans. Now widen your opportunity set so you are not relying on a single story.
- Target income resilience by reviewing steady payers screened as 29 dividend fortresses.
- Hunt for mispriced quality by scanning companies flagged as 13 high quality undervalued stocks.
- Strengthen capital protection by focusing on businesses filtered as 23 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com