
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is RUM Group (RUM) Undervalued As Its AI Data Center Pivot Draws Buy Ratings?
RUM Group (RUM) is under fresh scrutiny after analysts highlighted its pivot toward AI data centers and services, anchored by a reported six year contract with Anthropic that reshapes the business focus.
Despite the AI contract headlines, RUM Group’s recent trading has been rough, with the share price falling 37.4% over the past month and 18.3% over the last week. This adds to a 19.97% decline in 1-year total shareholder return, even though 3-year total shareholder return is still positive at 9%, while the longer-term 5-year total shareholder return is down 41.64%. This performance suggests that short-term momentum has weakened, while the longer record remains mixed around shifting expectations for the business transformation.
Stack your AI thesis on RUM Group against a curated field of peers by scanning the 38 AI small caps that are already building real businesses around similar themes.
RUM Group has fallen hard while analyst fair value estimates cluster far above the current US$5.69 share price. Is this a genuine discount, or a spread that valuation work struggles to justify?
Most Popular Narrative: 76% Undervalued
RUM Group’s most followed valuation story pins fair value at $23.50 against the last close at $5.69, so the gap only makes sense if the AI infrastructure and data center pivot turns the current loss-making profile into the earnings path analysts are modeling.
The upcoming launch of Rumble Wallet, with integrated crypto tipping and international payments, is expected to increase global user acquisition and drive engagement by tapping new markets where decentralized, creator-driven monetization is highly valued. This is anticipated to support top-line revenue growth and expand the platform's total addressable market. Expanding commercial partnerships (for example, with Tether, Cumulus Media, leading AI players, and MoonPay) creates diversified revenue streams and unlocks new ad inventory and creator monetization opportunities. This may support both revenue and ARPU while reducing reliance on a niche user base.
See why 23 investors see RUM Group as 76% undervalued.
Result: Fair Value of $23.50 (UNDERVALUED)
Still, the bullish AI story around RUM Group collides with real pressure points, including reliance on a single US$13.7b Anthropic deal and rising dilution risk.
Find out about the key risks to this RUM Group narrative.
Another View: RUM Group Looks Expensive On Sales
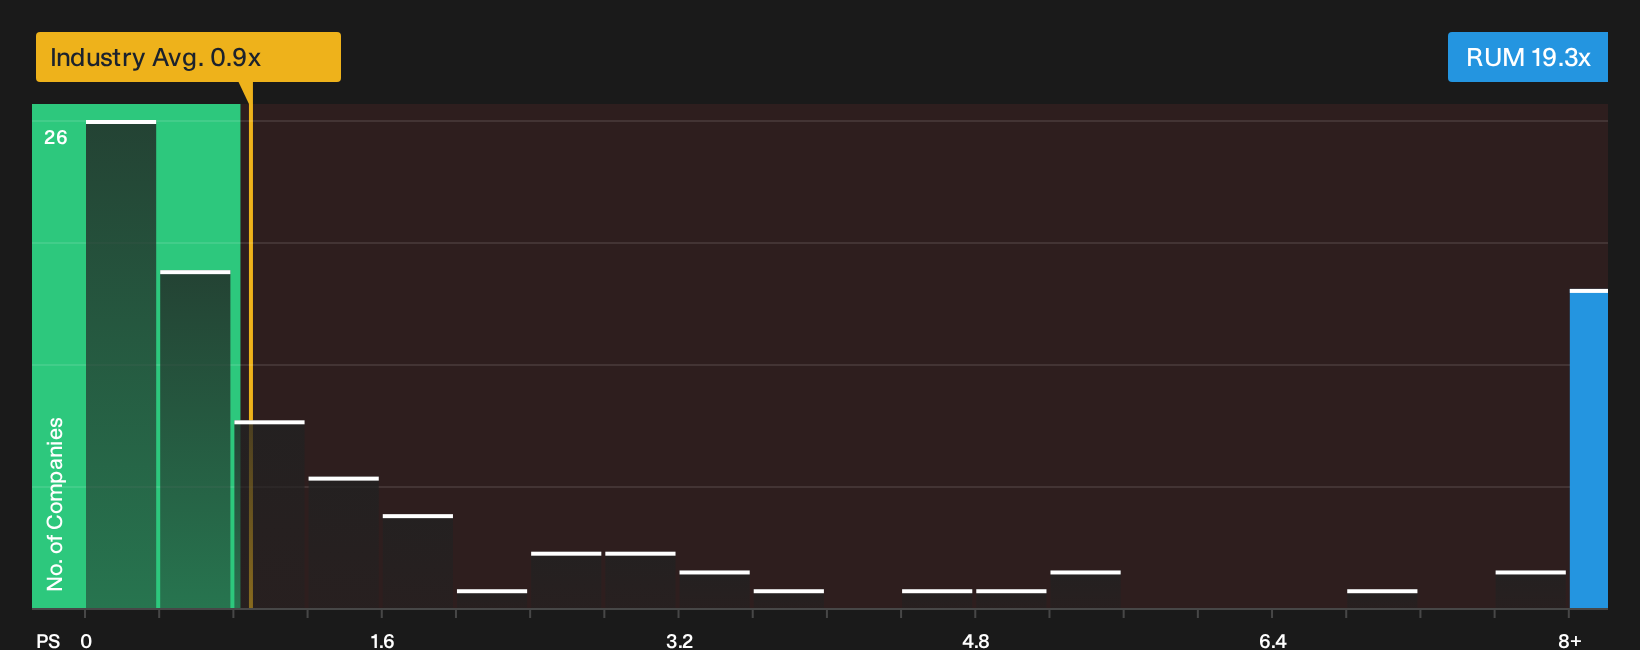
Flip the lens from analyst fair value to simple sales math and RUM Group screens very differently. The stock trades on a P/S ratio of 19.3x. The broader US Interactive Media and Services group is at 0.9x, while the peer average is 2.9x and the fair ratio for RUM Group sits at 7.9x. That is a wide gap that points to real valuation risk if lofty expectations for AI contracts, cloud usage and revenue growth do not hold up.
To see how this pricing stacks up against the underlying numbers, and how much of that premium rests on future execution, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around RUM Group’s AI push and current valuation make this a stock you need to inspect firsthand rather than rely on headlines. Take a few minutes to weigh the competing signals in the data, then ground your own view in the balance between 1 key reward and 4 important warning signs.
Looking for more investment ideas beyond RUM Group?
If RUM Group has your attention, do not stop here. Broaden your watchlist now so you are not relying on a single story.
- Press your edge in smaller, high-upside opportunities by scanning 14 elite penny stocks with strong financials that already pair tiny market caps with meaningful business traction.
- Target quality at a discount by checking out the 33 high quality undervalued stocks that combine solid fundamentals with prices that still lag underlying performance.
- Dial back risk while staying invested by reviewing the 32 resilient stocks with low risk scores that carry stronger balance sheets and more resilient profiles when conditions change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com