
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
NOV (NOV) Backlog And Oil Demand Story Leaves Room For An Undervalued View
Industry backdrop and NOV’s current setup
Robust oil prices are prompting more exploration and production work, putting NOV (NOV) in focus as demand strengthens for drilling and production equipment alongside its backlog and cost reduction program.
Recent trading tells a mixed story. NOV’s share price has eased over the past month and quarter; however, the year to date share price return of 15.36% alongside a 1 year total shareholder return of 52.92% suggests momentum has been stronger over a longer stretch as investors respond to improving equipment demand, the company’s backlog and cost work.
Scan beyond NOV and compare it with hand-picked equipment and services peers by running the 33 high quality undervalued stocks that blend stronger cash flows with sturdier balance sheets.
Bulls point to NOV’s backlog and cost work as underappreciated, while bears see a mid teens share price move this year as generous. Which side does the current valuation actually support?
Most Popular Narrative: 15% Undervalued
NOV last closed at $18.93 while the most followed fair value estimate sits at $22.18, which puts the focus firmly on whether its existing backlog and margin structure can support that gap.
Deepwater projects that use floating production systems and subsea kit continue to build multi year order books for NOV, with record EBITDA margins in Energy Equipment, a book to bill of 135% and a 28% backlog rise in subsea flexible pipe, and an approved US$200 million Brazil plant expansion. Together these factors point to additional revenue and earnings as this backlog is worked down.
See why 15 investors see NOV as 15% undervalued.
Result: Fair Value of $22.18 (UNDERVALUED)
Still, a sharp jump in tariffs and freight costs, or renewed operational disruption in regions like the Middle East, could quickly challenge the NOV undervaluation case.
Find out about the key risks to this NOV narrative.
Another view on NOV’s valuation
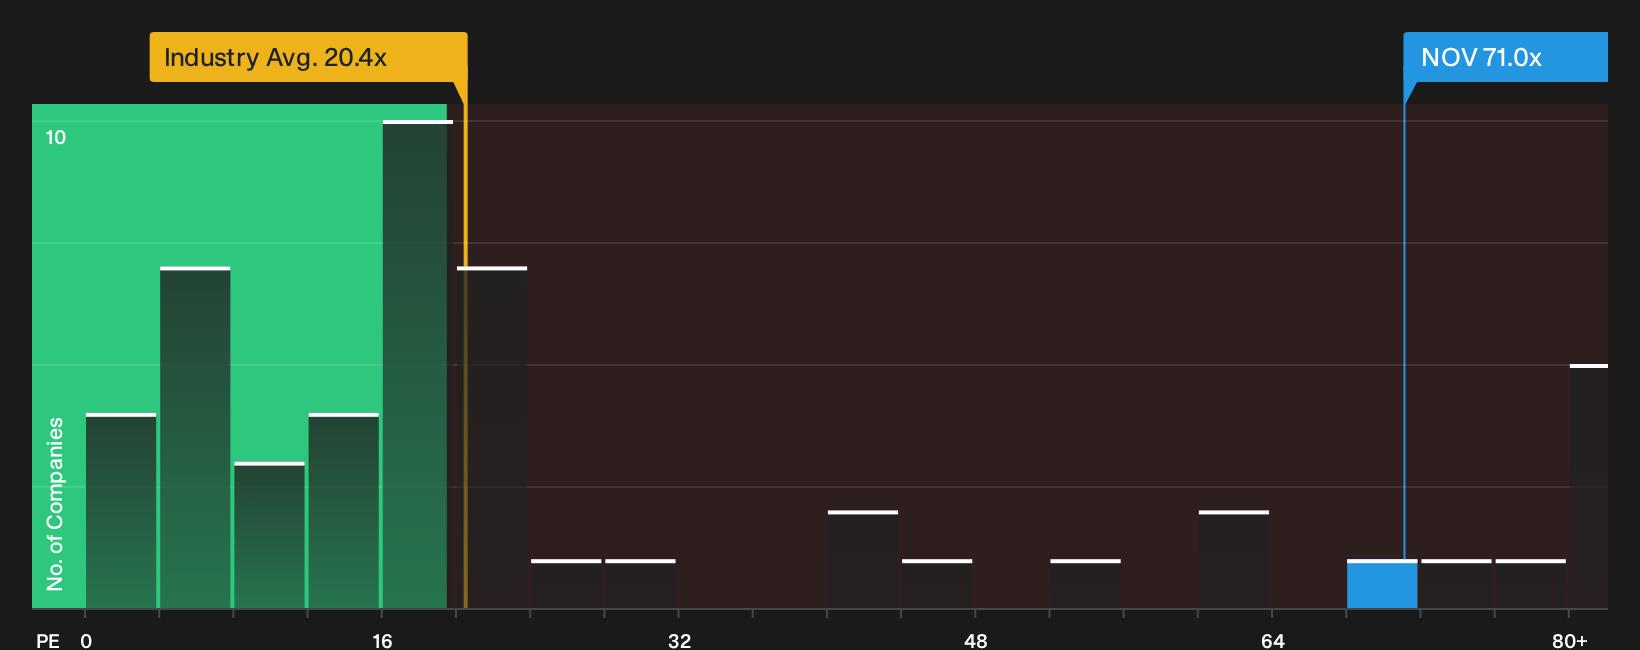
On earnings multiples, NOV looks far less forgiving. The stock trades on a P/E of 71x compared with about 20x for the US Energy Services group and a fair ratio estimate of 25.5x, which signals meaningful valuation risk if returns do not catch up to expectations.
That gap between today’s rich multiple and the fair ratio is wide enough that investors need to decide whether NOV’s backlog, margin work and earnings outlook justify paying such a premium, or whether patience is better spent on opportunities priced closer to that 25.5x level.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this NOV story points in different directions. Move quickly from reading to testing the numbers yourself, then weigh up the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond NOV?
If NOV’s setup has you thinking harder about price, quality and risk, do not stop here. Broader idea hunting can sharpen your next move.
- Target steadier potential by scanning companies with stronger balance sheets and fundamentals using the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities by reviewing the 33 high quality undervalued stocks that combine resilient cash generation with supportive financial strength.
- Stack your watchlist with fresh possibilities by checking the 20 high quality undiscovered gems that pair solid fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com