
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Valuation Reset Require Action From SEB (ENXTPA:SK) Investors?
- SEB has attracted fresh scrutiny after a strong one year rebound in operations, with current earnings and profitability now being weighed against a weaker five year track record.
- The key talking point is SEB's P/E ratio, which some analysts see as low relative to its earnings, risk profile and business size.
- We will now look at how SEB's investment narrative might shift as markets reassess its P/E against the current earnings base.
Compare SEB's valuation reset with other potential rebound stories by scanning a curated list of 189 high quality undervalued stocks that share solid earnings support and compressed P/E multiples.
SEB Investment Narrative Recap
To own SEB you need to believe the Rebound plan can translate the current earnings recovery into cleaner, repeatable profitability. The short term swing factor is execution on the €200m cost saving target and SKU simplification, which management aims to complete by early 2027. Recent P/E discussion does not change that core operational test.
The biggest near term risk still comes from external cost and trade pressures. Tariff uncertainty in North America and higher Iran related input and transport costs, estimated at about €30m in the second half of 2026, could offset efficiency gains and slow any margin and free cash flow improvement.
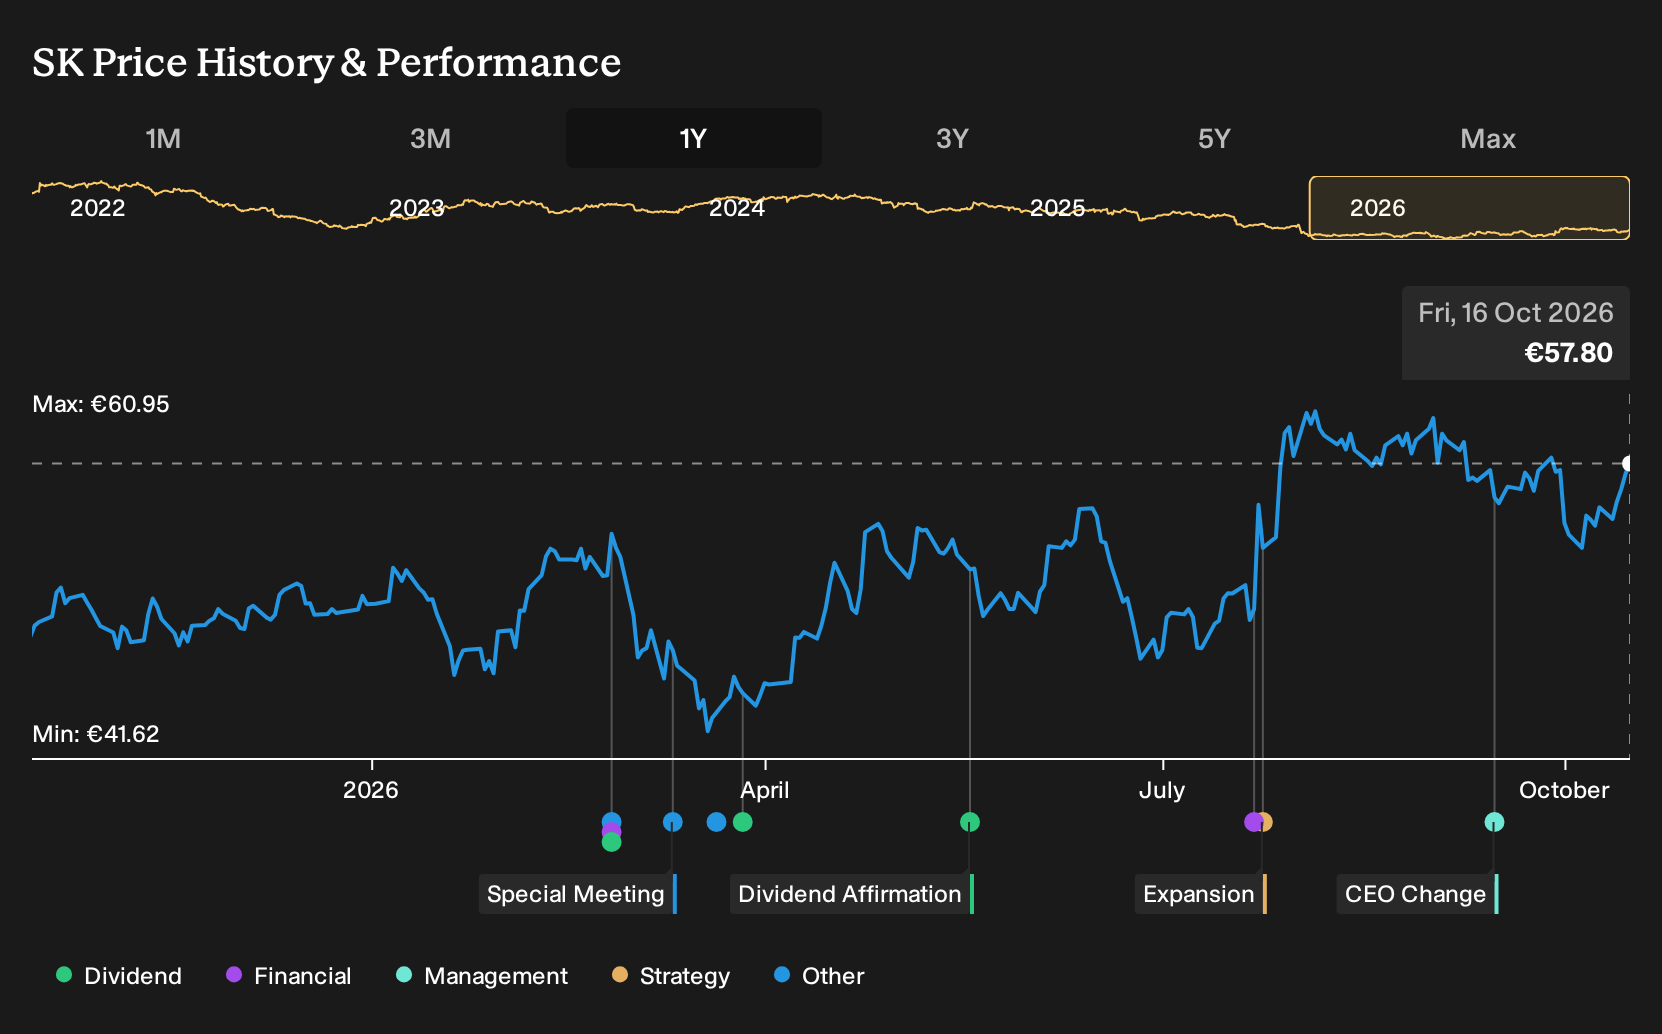
The clearest announcement tied to this P/E debate is the Rebound plan itself, including around €185m of restructuring provisions and a reported net loss of €124m in the first half of 2026 despite underlying profit. That accounting hit feeds straight into trailing earnings and, in turn, headline valuation multiples.
For you as an investor, the question is whether those one off items are a temporary clean up or a sign that savings are harder to capture. Progress toward the €200m recurring savings, together with tariff reimbursements of about €15m already booked, will shape how confidently the market treats SEB's current earnings base.
SEB's analyst narrative points to forecast revenue of €9.1 billion and earnings of €480.6 million by 2029. This implies 3.7% yearly revenue growth and an earnings increase of about 4x from the current €119.7 million base.
Uncover why SEB's fair value indicates a 28% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The lowest analysts focus on Professional Coffee as the real swing factor for SEB. They worry that its big fixed cost base and an earlier 10% like-for-like sales drop in Professional could drag on earnings, even though their January 2026 estimates still pencilled in about €9.2b revenue and €509.9m earnings by 2029. Those figures sat below today’s more upbeat consensus tone. Use that gap as a prompt to compare several views and decide which story you find more convincing, especially now that fresh news may push both narratives to shift.
Explore another SEB fair value estimate, including one that suggests it could be worth just €73.95.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your SEB research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for SEB. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate SEB's overall financial health at a glance.
Looking for more investment ideas beyond SEB?
If SEB has sharpened your focus on valuation and earnings quality, it can help to line it up against other opportunities that share some of the same traits. The Simply Wall St Screener lets you quickly filter for companies that match the type of balance sheet strength, income profile, or downside protection you want to see next to SEB in your watchlist.
- For investors who care most about resilient businesses with fewer red flags, start with 234 resilient stocks with low risk scores that historically show steadier risk profiles and may complement a position in SEB.
- If you are hunting for underappreciated opportunities, scan 614 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
- When cash flow resilience and financial strength matter more than headline growth, focus on the list of solid balance sheet and fundamentals (204 results) to see which companies combine prudent leverage with robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com