
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Tele2 Stock Debate Turns On Cost Cuts And Valuation
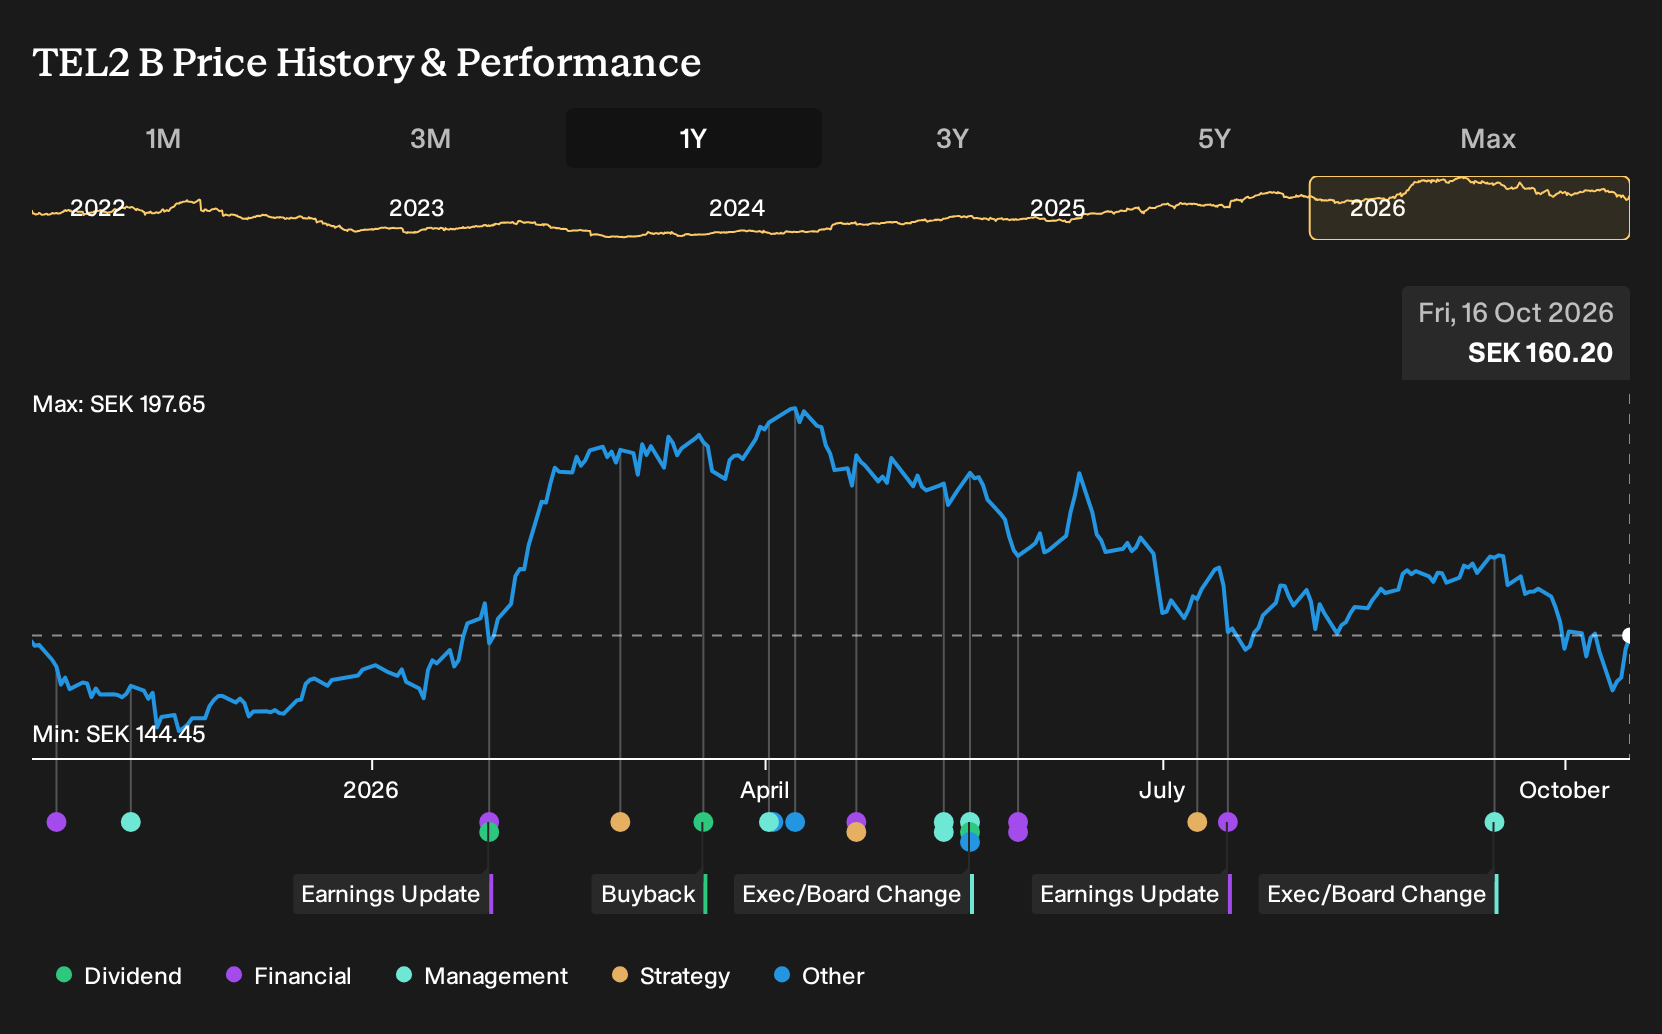
- Recent discussion around Tele2 highlights a multi year share price run, alongside a P/E ratio below the wireless telecom industry average.
- The debate now centers on whether Tele2's cost cutting and transformation program still offers meaningful upside, or is already fully reflected in expectations.
- We will now look at how this debate over Tele2's valuation and cost transformation might reshape the broader investment narrative.
Stress test your Tele2 thesis against a wider peer set by scanning our hand picked 189 high quality undervalued stocks that also combine cost discipline with current earnings-based value signals.
Tele2 Investment Narrative Recap
To own Tele2, you need to believe the core connectivity business in Sweden and the Baltics can keep modest revenue momentum while the cost transformation does not unwind. In the short term, an important swing factor is whether current profitability, helped by aggressive cost cuts and some one off effects, can hold as commercial and 5G spending steps up again.
The biggest operational risk right now is that competitive and regulatory pressure in Swedish broadband keeps squeezing ARPU while most easy cost savings are already taken. The recent discussion around Tele2’s valuation looks important for expectations, but it does not materially change these underlying business drivers.
The most relevant backdrop to this debate is the prior disclosure that earnings growth over the past year reached 143.5%, helped by a SEK 4.7b one off gain that lifted reported profit and pushed net margin to 33.6%. That profile, combined with a P/E of 11x against higher peer multiples, is what frames the current value discussion.
For catalysts, the key question is how Tele2 executes from here as those temporary benefits fade and higher network and commercial costs come through. Investors will likely focus on whether modest forecast revenue growth of about 1.9% a year and the existing cost program are enough to offset rising spend and support the present earnings base.
Tele2's analyst script projects SEK 31.8b in revenue and SEK 6.1b in earnings by 2029, based on 1.8% yearly revenue growth and an earnings decrease of SEK 4b from SEK 10.1b today.
Discover how Tele2's fair value indicates a 10% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view on Tele2 leans heavily on Baltic cash generation as a positive catalyst. The most optimistic analysts were pencilling in SEK 32.6b of revenue and SEK 5.7b of earnings by 2029, supported by Baltic EBITDAaL and IoT growth. Those projections came before this news, so your own take may shift as the story evolves.
Explore 4 other Tele2 fair value estimates, including one that suggests potential upside of up to 146% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Tele2 research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Tele2. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tele2's overall financial health at a glance.
Looking For More Ideas Beyond Tele2?
If the Tele2 story has sharpened your thinking, you can apply the same approach across the rest of the market with the Simply Wall St Screener. You can filter for quality, value, income or resilience so you are not relying on a single stock to support your thesis.
- For investors who want income as well as potential capital growth, review companies in the 216 dividend fortresses that may help anchor a yield focused portfolio.
- If capital preservation is a high priority, start with the 234 resilient stocks with low risk scores and work through businesses with more resilient profiles.
- When you want to widen your watchlist with under followed ideas, scan the 614 high quality undiscovered gems that combine stronger fundamentals with less market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com