
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How TIME Honors And MiniMed Separation At Medtronic (MDT) Have Changed Its Investment Story
- Medtronic reported new clinical evidence for its Altaviva tibial neuromodulation device and outlined long term real world follow up plans, while also seeing its Stealth AXiS surgical system and Corsano wearable named to TIME’s Best Inventions of 2026 and completing the MiniMed separation.
- The MiniMed spin out removes a lower margin, higher R&D diabetes franchise from Medtronic’s portfolio, which may sharpen focus on implantable therapies, robotics and continuous monitoring platforms highlighted by the TIME recognition.
- The focus now turns to how Medtronic’s refreshed portfolio after the MiniMed separation could reshape the broader investment narrative for the business.
Look beyond Medtronic and compare its medical device focus with a hand picked group of 33 healthcare AI stocks that are riding the shift toward data driven care and connected monitoring.
Medtronic Investment Narrative Recap
To own Medtronic, you need to believe the refocused portfolio after the MiniMed separation can lean on chronic disease therapies, robotics and connected monitoring to support revenue and margin resilience. The near term watchpoint is how quickly higher R&D and capital deployed into areas like neuromodulation and surgical systems translate into procedure growth and better mix.
The biggest operational risk still sits in uneven performance across franchises and ongoing mix pressure from lower margin units such as Cardiac Ablation Solutions. Recent Altaviva and TIME product recognition are directionally helpful for the story, but do not yet change the key near term question around portfolio consistency and gross margin quality.
The Altaviva tibial neuromodulation update is the clearest operational tell in this set of announcements. Two year TITAN 2 data with sustained reductions in nocturia and a five year ENDURANCE real world study plan point to Medtronic leaning harder into pelvic health as a long lived therapy platform, rather than a one off launch.
For catalysts, that matters because Altaviva fits the push into implantable, long duration devices that can support procedure volume and follow up revenue without the MiniMed drag. Execution risk remains real, from trial follow through to reimbursement and physician adoption, but solid clinical and usability attributes such as MRI compatibility and local anesthesia implantation give Medtronic more to work with operationally.
Medtronic's narrative projects US$42.8b revenue and US$7.1b earnings by 2029. This assumes 4.4% yearly revenue growth and an earnings increase of about US$1.9b from US$5.2b today.
Uncover why Medtronic's fair value indicates an 11% potential upside to its current price that could narrow quickly.
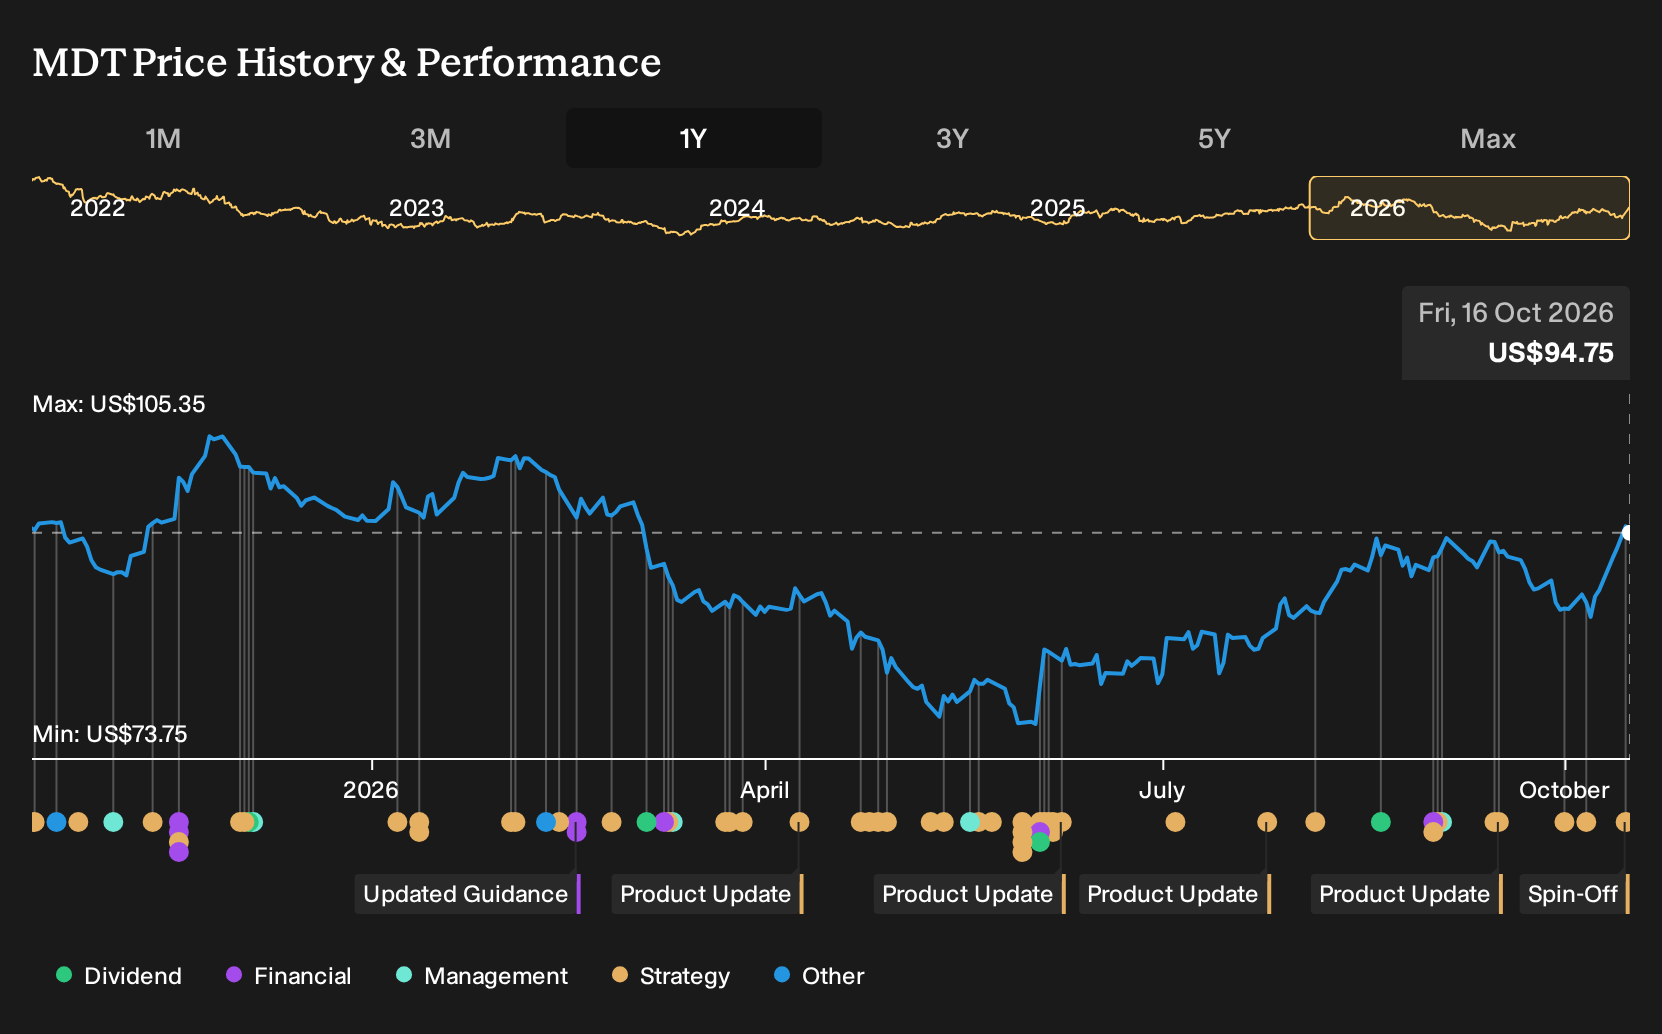
Exploring Other Perspectives
Some of the most optimistic analysts were already counting on Medtronic’s high growth platforms as a single powerful catalyst, with revenue reaching about US$44.1b and earnings of US$7.1b by 2029 before this Altaviva news. You can treat this fresh data as a reason to revisit those assumptions and compare several viewpoints for yourself.
Explore 8 other Medtronic fair value estimates, including one that suggests as much as 22% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Medtronic research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Medtronic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Medtronic's overall financial health at a glance.
Looking For More Ideas Beyond Medtronic?
Once you have a view on Medtronic, it often helps to zoom out and line it up against a broader watchlist. The Simply Wall St Screener can help you quickly sort through hundreds of companies and focus on the few that actually match your style and risk tolerance.
- If capital preservation comes first for you, start with 32 resilient stocks with low risk scores that pair steadier risk profiles with more predictable business models.
- For investors hunting for value, filter for 33 high quality undervalued stocks where solid fundamentals and current pricing look out of sync.
- If you want balance sheet strength front and centre, scan the list of solid balance sheet and fundamentals (25 results) and build a shortlist of financially robust companies.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com