
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Is Drawing Attention To GLP J-REIT (TSE:3281)?
Buyback, earnings and balance sheet moves put GLP J-REIT in focus
GLP J-REIT (TSE:3281) has put capital allocation front and center after its board approved a buyback of up to 77,000 units, alongside fresh earnings, dividend guidance and refinancing decisions.
All of this is landing after a softer run for GLP J-REIT’s units, with the share price down 12.9% year to date and the 90 day share price return declining 8.73%. Even though the 3 year total shareholder return of 14.26% still points to a better longer run outcome than the recent loss making 1 year total shareholder return of 0.87% and 5 year total shareholder return of 12.13%, recent buyback, refinancing moves and distribution guidance are being read through the lens of fading momentum and a reassessment of risk around cash flows.
Compare GLP J-REIT’s balance sheet moves with other income-focused plays by scanning our hand picked 29 dividend fortresses for ideas with sizeable yields and robust fundamentals.
GLP J-REIT is leaning on buybacks, refinancing and distribution guidance to show confidence in a logistics-heavy portfolio. The harder question is whether today’s unit price already reflects that strength or still leaves a margin of safety.
Preferred P/E of 20.2x for GLP J-REIT: Is it justified?
Valuation for GLP J-REIT currently leans on a P/E of 20.2x against a last close of ¥129,600, while several checks flag the units as expensive versus both peers and an estimated fair range.
The P/E ratio compares what investors are paying for each unit of current profit. For a real estate trust like GLP J-REIT, it gives a quick read on how the market prices its earnings stream relative to similar listed REITs focused on logistics assets.
Here, that 20.2x P/E is described as expensive compared to the Asian Industrial REITs average of 15.7x, and also as rich versus peers at 19.4x. Analysts describe a fair P/E of around 20x, so current pricing slightly exceeds that level. This suggests the market is assigning a premium multiple that may be hard to reconcile with slower forecast earnings growth and a low 6.9% return on equity.
Explore the SWS fair ratio for GLP J-REIT.
Result: Price-to-Earnings of 20.2x (OVERVALUED)
Still, GLP J-REIT faces pressure if logistics demand softens or refinancing costs rise. This could challenge payout expectations and sentiment around the unit price.
Find out about the key risks to this GLP J-REIT narrative.
Another view on GLP J-REIT's value
The SWS DCF model points in a different direction for GLP J-REIT. At ¥129,600, the units are trading above an estimated future cash flow value of ¥93,441.03, which frames the trust as overvalued on this metric and raises a simple question: Is the earnings multiple or the cash flow picture closer to reality for you?
Look into how the SWS DCF model arrives at its fair value.
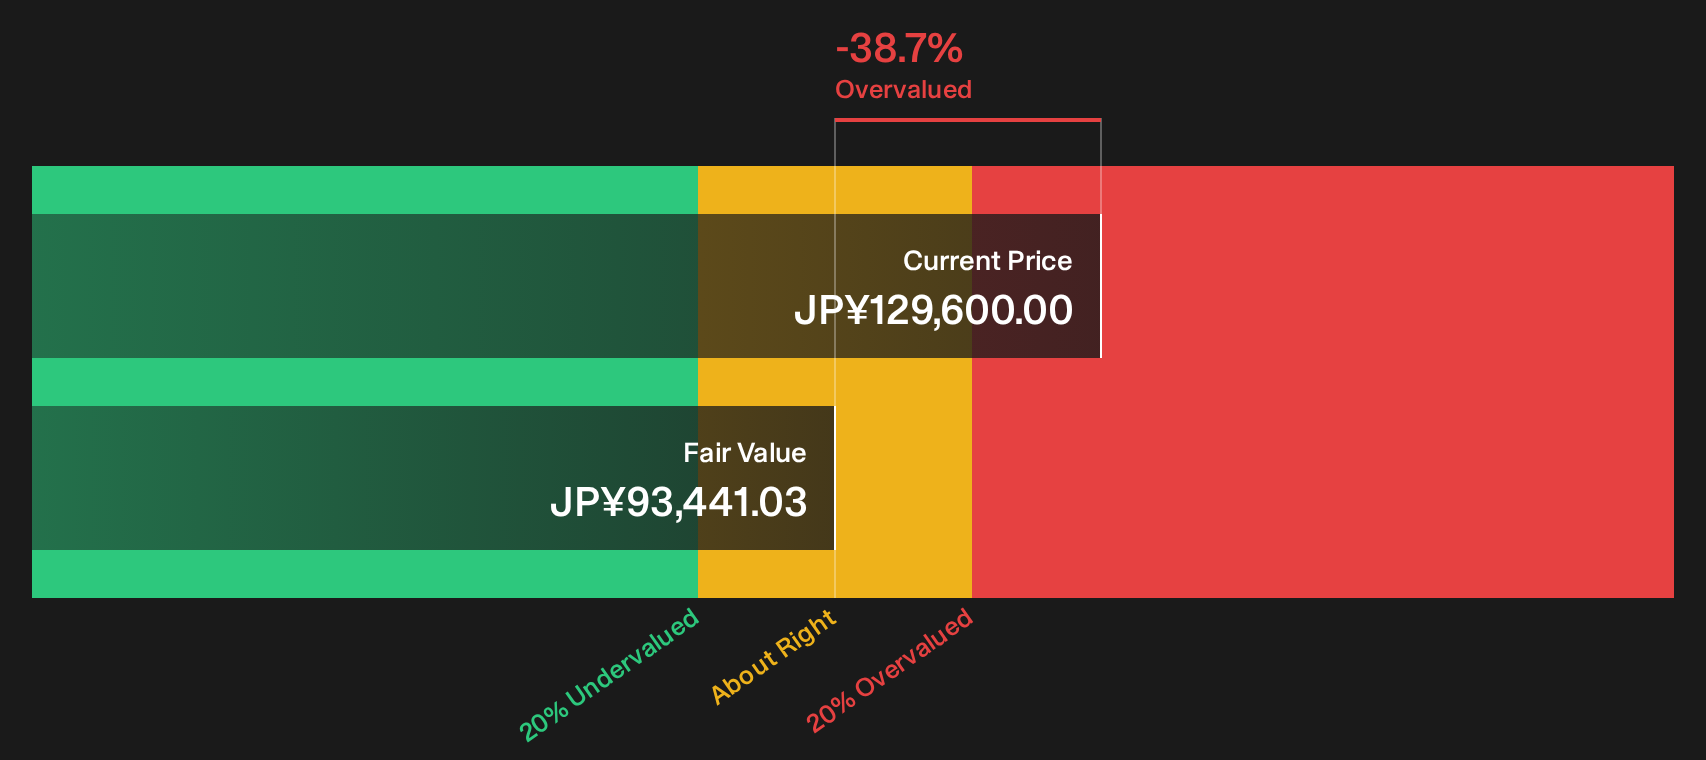
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out GLP J-REIT for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on GLP J-REIT? If this mix of premiums, buybacks, risks and rewards has you on the fence, move quickly and dig into the full picture through our 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond GLP J-REIT?
Do not stop at GLP J-REIT. Use the Simply Wall Street Screener to compare fresh opportunities side by side and avoid missing out on stronger setups.
- Target stronger income potential by scanning a curated 29 dividend fortresses that balances higher yields with financial resilience.
- Hunt for mispriced quality through a focused 13 high quality undervalued stocks that filters for robust balance sheets and solid cash generation.
- Spot future leaders early with a 73 high quality undiscovered gems that surfaces under-followed businesses backed by healthy fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com