
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
BIPROGY (TSE:8056) Jumped, So What Is Behind The Move?
Recent share performance and business profile
BIPROGY (TSE:8056) has drawn attention after a recent move in its share price, with the stock closing at ¥5,062. Investors are weighing that level against the group’s broader return record.
Recent trading tells a mixed story. BIPROGY has enjoyed a 1-day share price return of 3.56% and an 8.56% gain over 90 days. However, the year-to-date share price return is down 6.09%, while the 1-year total shareholder return has declined 10.82%. Longer term 3-year and 5-year total shareholder returns of 48.63% and 82.79% point to a much stronger historic payoff for patient holders.
Scan beyond BIPROGY and track similarly resilient performers with strong recent momentum using our hand picked 13 high quality undervalued stocks as a starting universe.
BIPROGY has bounced in the short term but is still working off a weaker year for shareholders. Investors may be considering whether that recent lift justifies buying now or whether patience for a cheaper entry makes more sense as valuation comes into focus.
Preferred P/E multiple of 16.4x: Is it justified?
Valuation for BIPROGY currently leans on a P/E lens, with the stock trading on a 16.4x earnings multiple at a share price of ¥5,062. That level comes in below both its industry and peer benchmarks, which puts the focus squarely on whether the market is underestimating the company’s earnings power.
The P/E ratio compares what investors pay for each unit of current profit. For a software and IT services group like BIPROGY, this metric often reflects how confident the market is about the durability of cash flows from long dated service contracts, outsourcing revenue, and recurring support work.
Here, the numbers lean supportive. The business is described as good value on a P/E of 16.4x compared to the estimated fair P/E of 21.9x, and also looks cheap relative to both the JP IT industry average of 16.5x and a peer average of 25.5x. That spread suggests the market is assigning a discount that could narrow if earnings quality and growth rates remain consistent with recent history.
Explore the SWS fair ratio for BIPROGY.
Result: Price-to-earnings of 16.4x (UNDERVALUED)
Still, BIPROGY’s heavy reliance on the Japanese market and exposure to slower growing hardware segments could limit how far any valuation re rating goes.
Find out about the key risks to this BIPROGY narrative.
Another view on BIPROGY’s value
The P/E workup points to BIPROGY looking inexpensive, yet a different lens tells a similar story. Our DCF model values the shares at about ¥5,339.85, compared with the current ¥5,062 price. That implies the stock trades roughly 5% below this cash flow based estimate. Does that gap reflect caution or opportunity in your portfolio?
For readers who want to see how this cash flow based result is built line by line, Look into how the SWS DCF model arrives at its fair value.
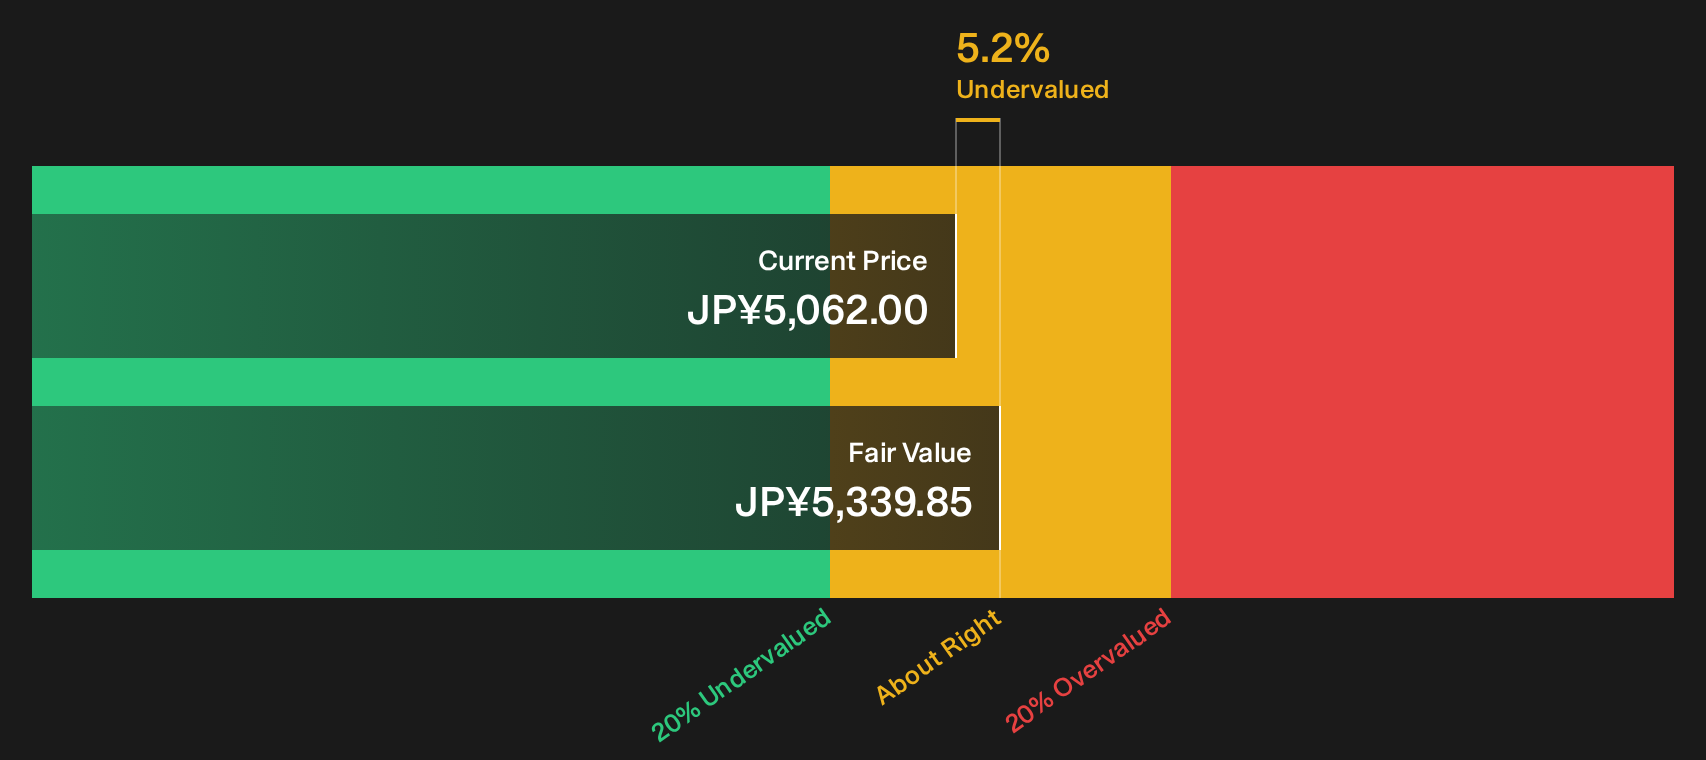
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out BIPROGY for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on value and momentum can pull investors in opposite directions, so it is important to look beyond the headline numbers and test whether BIPROGY truly fits your goals. To weigh both sides of the story in one place, review the 4 key rewards and 1 important warning sign.
Looking for more BIPROGY sized investment ideas?
If BIPROGY has you rethinking where value and quality intersect, it can pay to widen your watchlist with a few focused stock shortlists.
- Target potential mispricing by scanning for companies that pair solid fundamentals with discounted valuations using the 13 high quality undervalued stocks.
- Strengthen your defense by reviewing businesses with cleaner finances and sturdier balance sheets inside the list of solid balance sheet and fundamentals (22 results).
- Get ahead of the crowd by tracking underfollowed opportunities that still show strong quality markers through the 73 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com