
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Comstock Resources (CRK) Stock May Be Richly Priced On Gas Price Weakness
Comstock Resources has given long term holders a 51.3% return over the past 5 years, yet the stock is down sharply this year and that split performance raises a clear question about whether its current US$14.00 share price is still aligned with what the business earns. With energy headlines focused on fuel markets and refining, investors now have to ask whether Comstock Resources' earnings can carry the weight of today's valuation.
- A 51.3% gain over 5 years puts real money on the line for anyone judging whether the recent share price level is still supported by the company's earnings power.
- Recent sector news points to natural gas producers facing weaker pricing, which can affect how reliably Comstock Resources converts production into profit and therefore how much investors may be willing to pay for each dollar of earnings.
- Your read on Comstock Resources is one view; the desks covering it have another. See what analysts think Comstock Resources's shares could be worth.
The stock's next move may depend on whether Comstock Resources' current price can be squared with what its earnings justify today.
To pressure test whether Comstock Resources' earnings still justify that US$14.00 tag, it can help to line it up against other 33 high quality undervalued stocks
Is Comstock Resources Getting Expensive on Earnings?
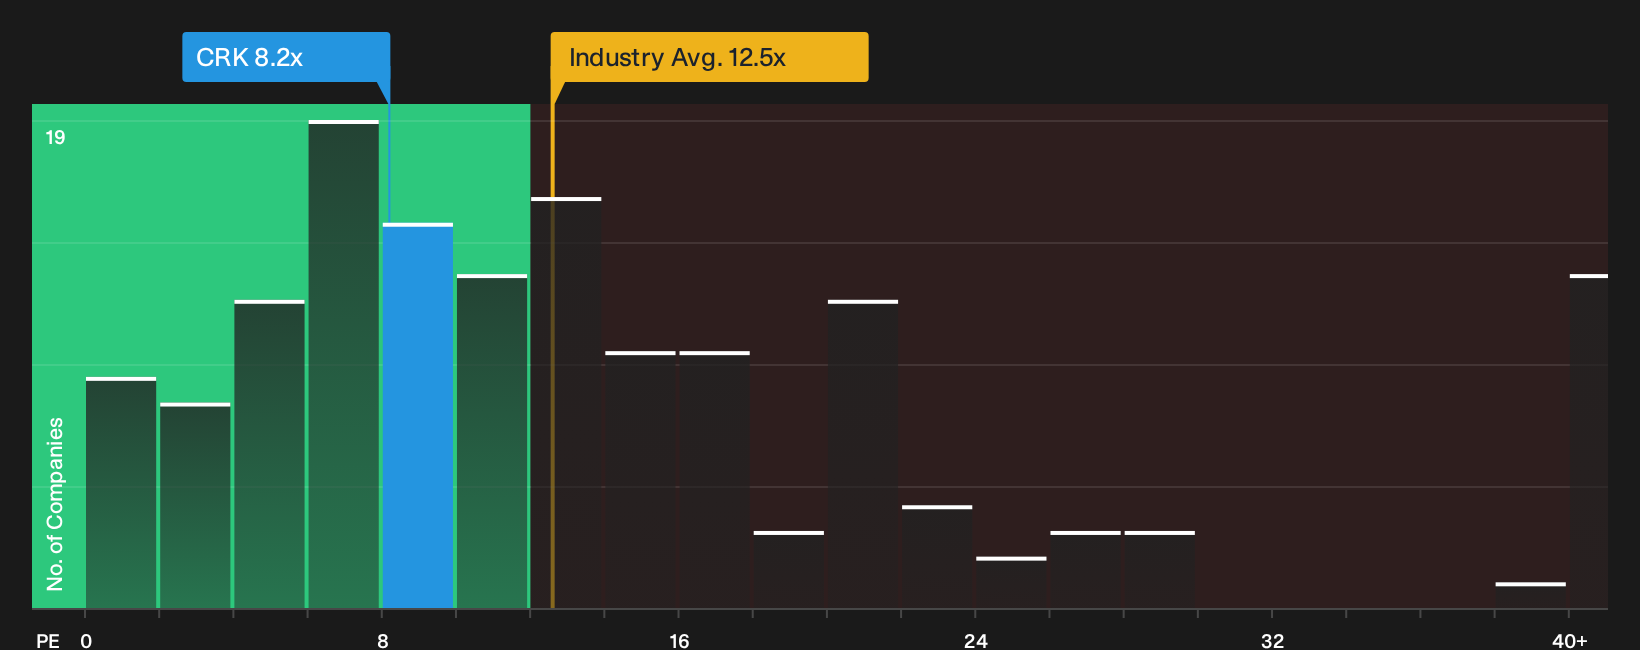
The P/E ratio suits Comstock Resources because earnings remain the main yardstick investors use for producers in the Oil and Gas industry. At roughly 8.2x earnings, Comstock Resources trades below the wider sector, where the average Oil and Gas stock changes hands around 12.5x, and also below the peer group on about 9.6x. That gap suggests the market is applying a more cautious label to each dollar of profit at Comstock than to comparable producers.
Despite natural gas focused operators lagging oil heavy peers while refiners benefited from tighter fuel markets in 2026, the current 8.2x multiple still comes out higher than what a more tailored fair P/E would imply once factors such as growth profile, margins and risk are fed into the model. The stock therefore prices in a richer earnings tag than that framework supports, even as it screens cheaper than the broad industry pack. Explore the numbers behind Comstock Resources's P/E valuation.
The Comstock Resources Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Comstock Resources step in where the P/E debate leaves off and spell out which paths for future growth, profitability and earnings would need to unfold for the current valuation to look meaningfully too high or too low. Each scenario anchors its number to a specific view on where Comstock Resources' growth, margins and risks go next, giving you something concrete to compare against as fresh information comes through.
Community views on Comstock Resources are split between investors who see Haynesville growth as underappreciated and others who think gas risk and costs are already fully reflected.
Bull case: 8% undervalued
"The recently announced strategic collaboration with NextEra Energy for potential gas-fired power and data center projects near Western Haynesville leverages proximity to major demand centers..."
Discover why this Narrative puts Comstock Resources at 8% undervalued.
Bear case: 8% overvalued
"Rapid acceleration of global renewable energy adoption and electrification is poised to erode long-term natural gas demand, which will place sustained downward pressure on Comstock's core revenues..."
Explore why this Narrative puts Comstock Resources at 8% overvalued.
One more angle on Comstock Resources that could change how you see it
The next question is who is steering Comstock Resources and how their pay lines up with your interests, because the people making the calls matter as much as the numbers. See who runs Comstock Resources and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com