
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Headquarters Move Require Action From UBS (SWX:UBSG) Investors?
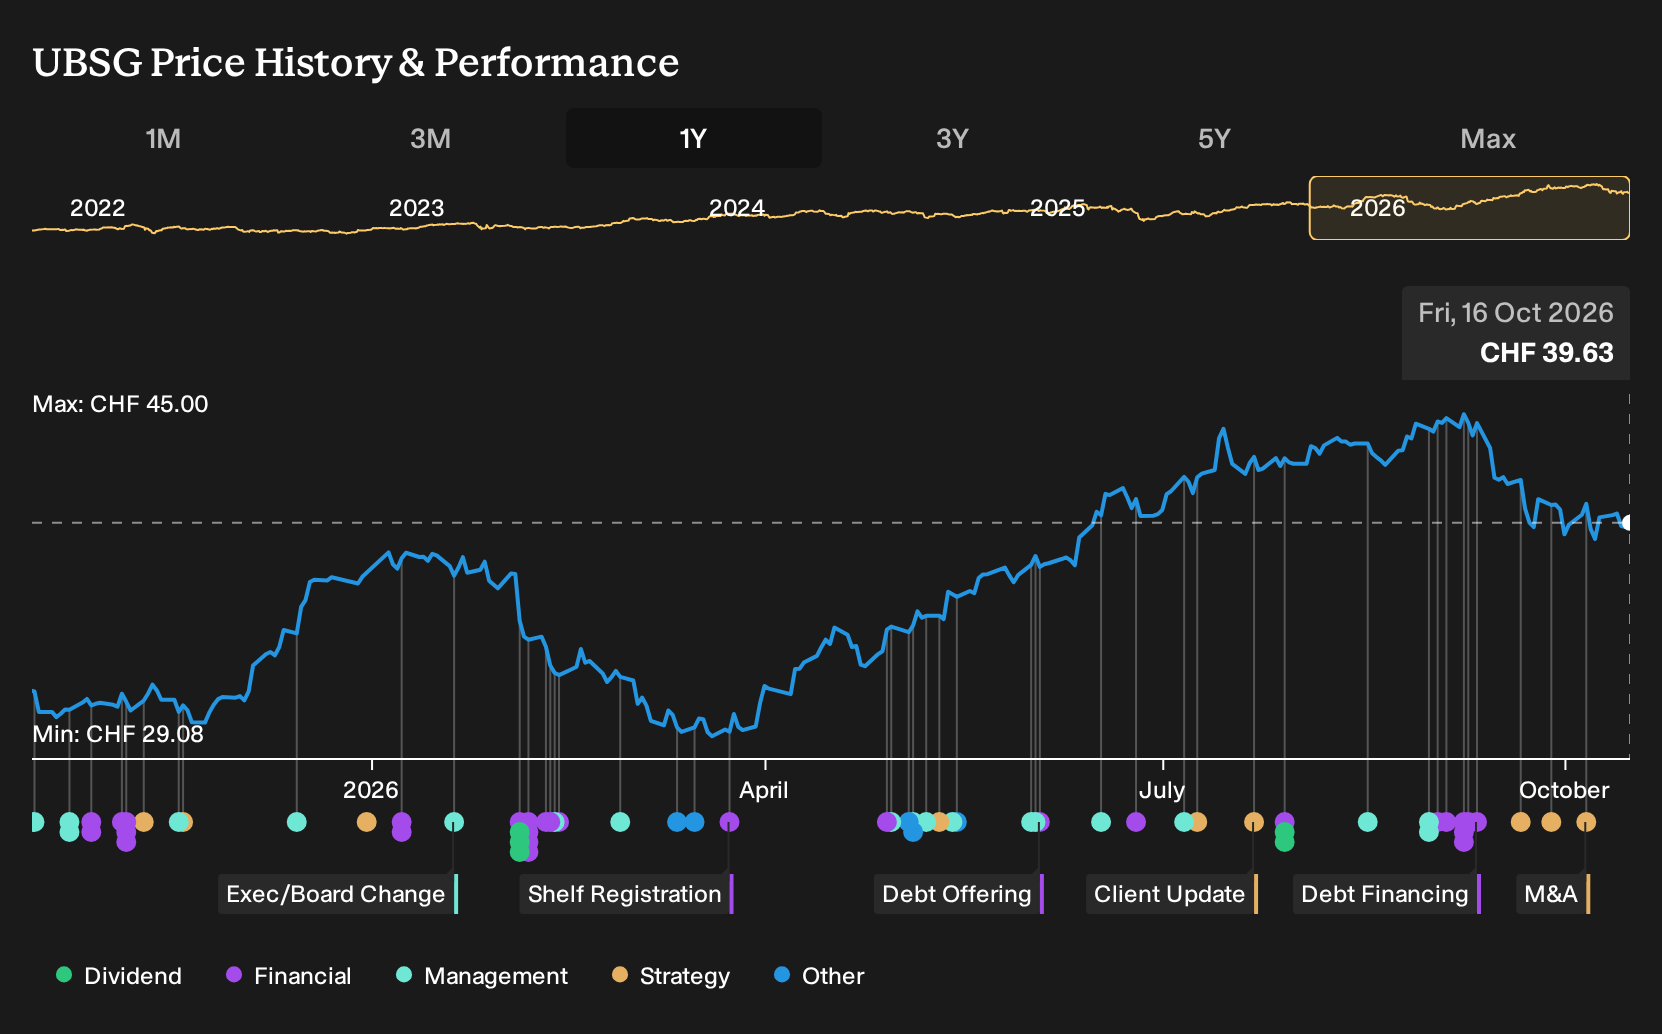
- UBS Group recently confirmed it plans to move its headquarters out of Switzerland after Swiss authorities pushed for tougher regulatory capital rules that the bank views as onerous.
- This potential relocation highlights how regulatory capital demands can reshape UBS Group’s cost base, risk booking, and long term balance sheet commitments.
- We will look at how UBS Group’s investment narrative is affected by this potential headquarter move driven by Swiss capital pressure.
Compare how UBS Group responds to regulatory pressure with a curated set of banks and financials facing similar capital demands through the 234 resilient stocks with low risk scores for steadier balance sheets.
UBS Group Investment Narrative Recap
To own UBS Group, you need to believe the larger wealth management and universal banking model can absorb higher regulatory friction while still turning its scale, fee income, and Credit Suisse integration into steadier earnings. The core near term upside story is about converting those cost synergies and digital investments into more efficient operations and stronger profitability.
The planned headquarters move looks material mainly as a capital and regulation story, not as a shift in client demand. It could influence how much surplus equity UBS Group can put toward growth or buybacks. That ties directly into the biggest current risk, that rising capital requirements and compliance costs eat into returns faster than integration benefits show up.
The most relevant recent update is the strong Q2 2026 print, where UBS Group reported higher revenue and profit margins. That result gave investors tangible evidence that Credit Suisse integration and prior cost work are feeding through into the income statement, even as one off items and legacy issues still shape reported numbers.
Seen against the headquarters decision, those Q2 figures become a reference point for execution risk. The key question for you is whether UBS Group can keep margins resilient while juggling extra regulatory capital, multi year integration tasks, and higher compliance spend, or whether those headwinds blunt the earnings trajectory that recent quarters have begun to outline.
UBS Group's current analyst narrative points to US$56.7b in revenue and US$15.0b in earnings by 2029, based on 2.2% yearly revenue growth and an earnings increase of US$5.5b from US$9.5b today.
Uncover why UBS Group's fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest UBS Group forecasts focus on a different risk. You see capital pressure as the headline today, while they worry more about earnings power stalling. Before this news, the bearish group was pencilling in about US$54.0b of revenue and US$14.3b of earnings for 2029. Those expectations could shift quickly, so compare both stories and decide which seems closer to your view.
Explore 4 other UBS Group fair value estimates, including one that suggests as much as 14% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your independent thinking and analysis.
- A great starting point for your UBS Group research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for UBS Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UBS Group's overall financial health at a glance.
Looking for more investment ideas beyond UBS Group?
Once you have formed a view on UBS Group, it can help to set it alongside peers that match your risk appetite, income needs, and balance sheet preferences.
- For investors who want potential upside without taking on excessive financial stress, compare UBS Group with a 234 resilient stocks with low risk scores that screen well on resilience and capital strength.
- If you are hunting for quality at a sensible price, line up UBS Group against a 191 high quality undervalued stocks that pair solid fundamentals with more modest expectations.
- For readers who care most about dependable cash returns, weigh UBS Group against a field of 216 dividend fortresses that focus on income alongside balance sheet support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com