
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Novavax (NVAX) Expensive Or Cheap As Investors Reassess Vaccine Risk?
Novavax (NVAX) dropped 12.7% on 16 October as rising Treasury yields pulled money toward safer assets and away from growth-oriented healthcare stocks, leaving investors reassessing risk in early-stage vaccine developers.
The sharp one day decline sits against a very different backdrop over the past few months, with Novavax posting a 90 day share price return of 42.89% and a year to date share price gain of 57.92%. At the same time, the 1 year total shareholder return of 39.01% and the 5 year total shareholder return that declined 91.63% highlight how recent momentum contrasts with a much tougher longer term experience for investors.
Scan for other healthcare stocks that are holding up better under higher yields by checking our curated list of 32 resilient stocks with low risk scores, which aims to limit downside when volatility spikes.
Bulls point to Novavax’s recent rebound and the gap to analyst targets, while bears focus on losses and a brutal 5 year record. Which story does the current valuation really support next?
Most Popular Narrative: 61% Overvalued
Against the last close at $11.26, the most followed narrative pegs Novavax fair value at $7.00 using a 7.44% discount rate, which frames recent volatility as a potential mismatch between price and fundamentals.
Heavy historical dependence on a narrow product portfolio, primarily COVID-19 and flu vaccines, magnifies Novavax's vulnerability to rapid market saturation, declining demand post-pandemic, and competitive displacement. This increases the likelihood of sharp revenue contraction once near-term milestone payments and royalties subside. Major industry players with deeper resources are accelerating both commercial execution and innovation in next-generation vaccine platforms, intensifying pricing pressure and competitive threats against Novavax. This will likely erode market share and prevent sustainable improvement in revenues or operating margins.
See why 1 investors see Novavax as 61% overvalued.
Result: Fair Value of $7.00 (OVERVALUED)
Still, two things could upend that bearish Novavax story: richer Matrix M licensing deals and stronger than expected revenue from the Sanofi partnership.
Find out about the key risks to this Novavax narrative.
Another View: Market Pricing Versus Fundamentals For Novavax
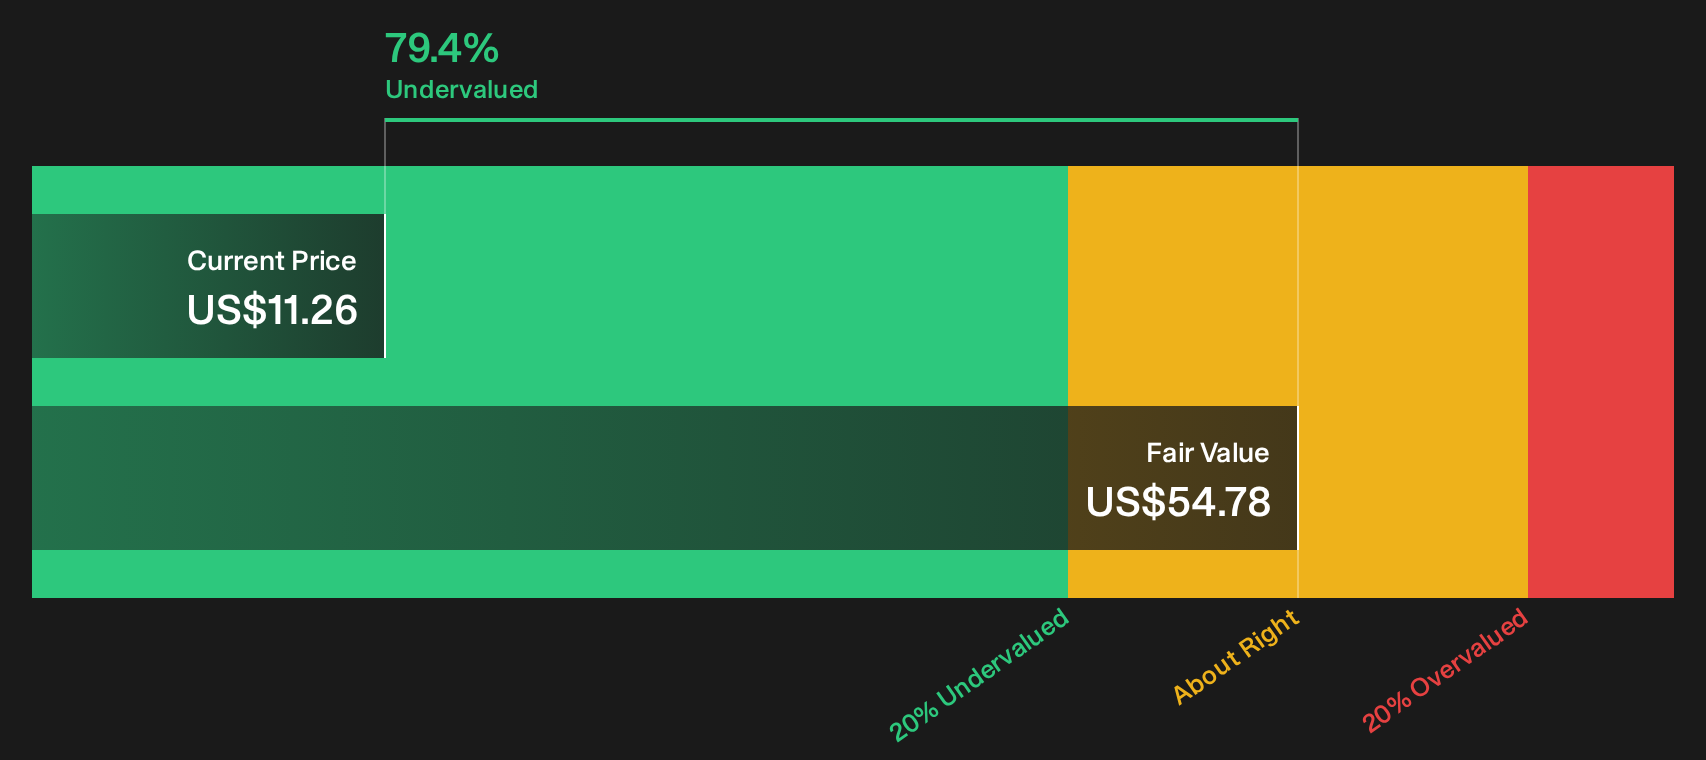
The popular narrative calls Novavax overvalued at a fair value of $7.00, yet the market is pricing the stock far below the SWS DCF model output of $54.78 based on future cash flows. That gap presents DCF as a more optimistic signal and raises the question of which measure investors might rely on more.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment on Novavax is split, with sharp past declines set against recent strength. Move quickly to review both sides of the story and weigh the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Novavax?
If Novavax has your attention but you want a wider playbook, consider using this pullback to line up fresh ideas before the next wave of money moves.
- Target resilience by scanning a curated pool of companies with stronger downside protection using the 32 resilient stocks with low risk scores.
- Hunt for quality at a discount by checking the 20 high quality undiscovered gems that combine solid fundamentals with less crowded investor attention.
- Stack potential returns with income by reviewing the 8 dividend fortresses that aim to pair higher yields with balance sheet strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com