
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Amadeus (BME:AMS) AI Risk Valuation Debate
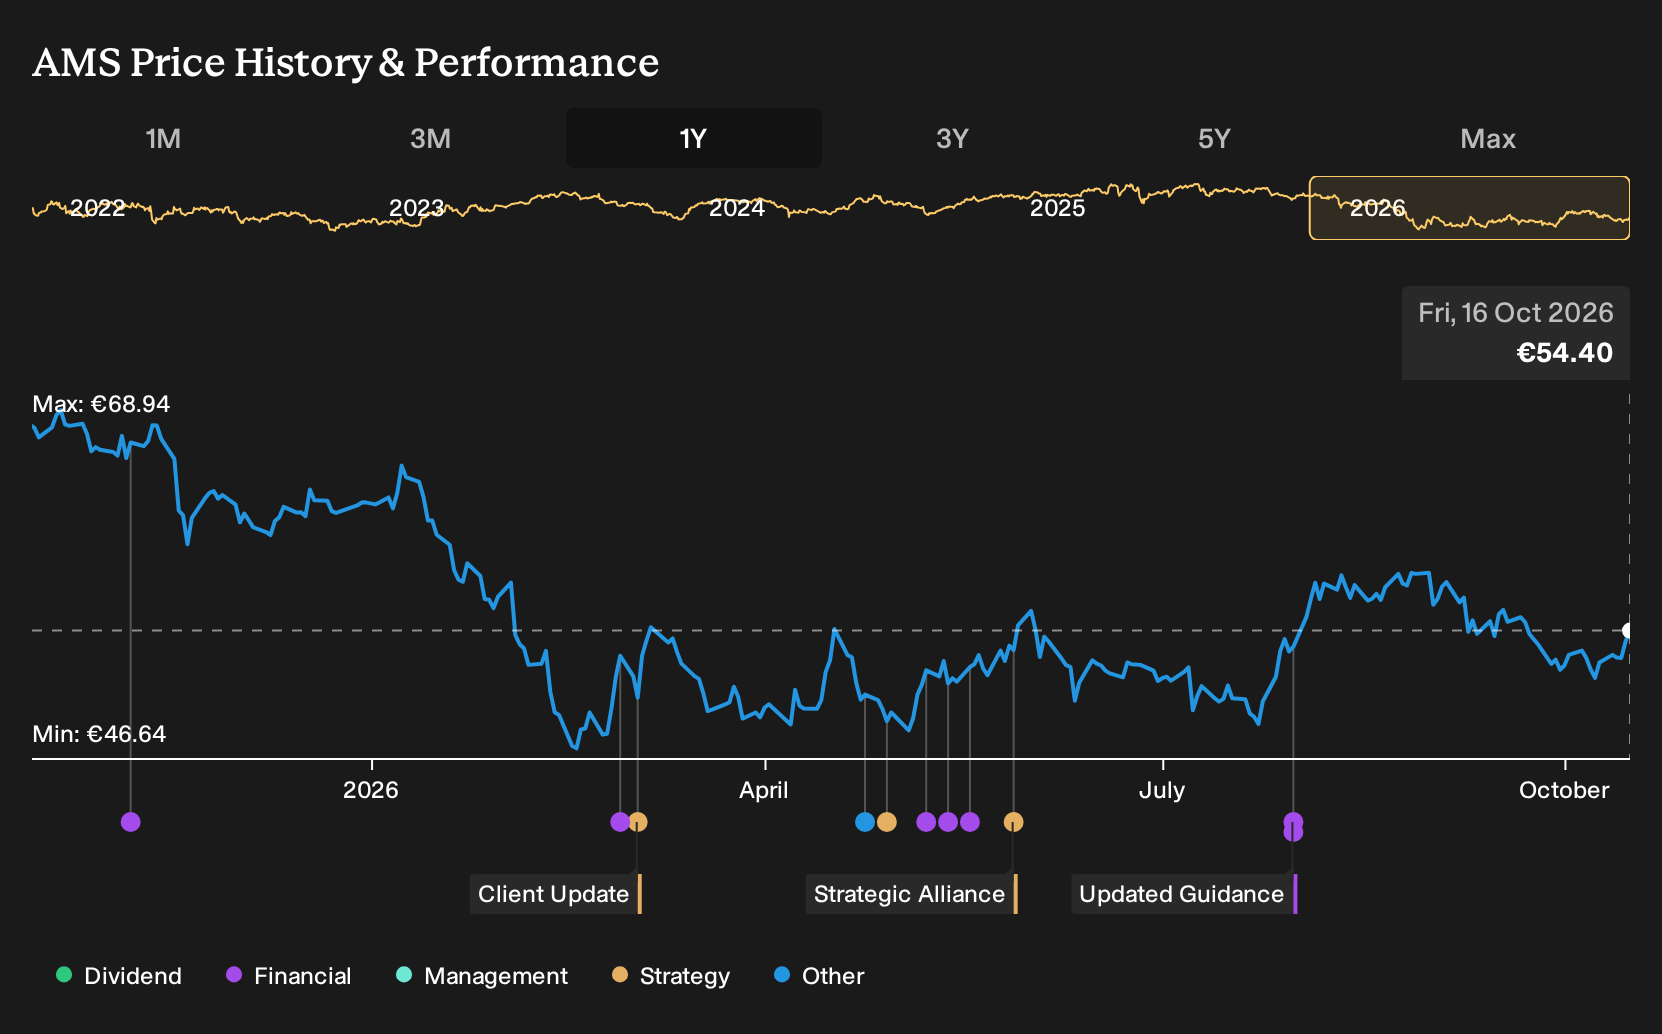
- Amadeus IT Group has seen its valuation questioned after an 18.9% share price decline over the past year, as investors compare the current market price with the cash flows implied by a Discounted Cash Flow model.
- The key debate now centers on whether concerns about AI-driven disintermediation are overstated relative to Amadeus IT Group's cash generation and long-term free cash flow profile.
- We will look at how Amadeus IT Group's investment narrative is being tested by the valuation gap implied by fresh DCF analysis.
Compare how Amadeus IT Group stacks up against other potential rebound candidates by scanning our curated list of 191 high quality undervalued stocks with solid cash generation and room for sentiment to shift.
Amadeus IT Group Investment Narrative Recap
To own Amadeus IT Group, you need to be comfortable with a travel technology business whose cash generation still hinges on flight volumes, while it works to deepen its role in airline IT, hospitality and payments. The recent 18.9% share price decline and fresh DCF work mainly challenge sentiment, not the operating thesis.
The key short term swing factor is how quickly air traffic and bookings stabilise after recent geopolitical disruptions. The biggest risk is that AI driven tools from airlines or online agencies cut volumes flowing through Amadeus platforms, just as higher spend on AI, biometrics and hospitality offerings weighs on margins.
Recent commentary around Amadeus IT Group has focused on the DCF analysis that indicates an intrinsic value above the current market price. That ties directly into the catalyst question, because it highlights how much depends on execution in cloud migration, AI products and higher value content in distribution.
No major new operational announcements sit directly behind this latest share price move. As a result, more attention falls on existing initiatives, such as the public cloud migration targeted for completion in 2025 and the AI driven tools already deployed. The way these projects translate into unit economics and free cash flow remains the practical yardstick for investors.
What The Current Forecasts Assume For Amadeus IT Group
Amadeus IT Group's current analyst framework leans heavily on a steady ramp in both revenue and profitability. Consensus models point to revenue expanding by 7.8% a year over the next three years, with profit margins moving from 19.9% today to 21.9% on a similar time frame. The earnings base in those projections starts at about €1.3b and works toward €1.8b by 2029, which implies roughly a €0.5b step up in annual profit if those estimates play out.
Those earnings forecasts sit inside a broader set of assumptions that matter if you are assessing the stock as a potential rebound candidate rather than just a screen for cheap optics. Analysts are effectively baking in not only higher throughput from travel volumes but also better mix from higher value airline IT, hospitality and payments contracts. In addition, they see the share count shrinking by about 3.36% per year over the next three years, which would mechanically lift earnings per share if the profit pool holds at forecast levels.
Valuation work tied to these numbers clusters around a 2029 snapshot for Amadeus IT Group. The consensus price target of €69.16 is built on earnings of €1.8b and assumes the stock trades on a 19.1x P/E multiple at that point, compared with about 16.5x today. To line up with that view, you would need to be comfortable that the business can reach roughly €8.3b in revenue by 2029 and that investors are prepared to pay a richer multiple than the current 13.0x P/E seen across the GB Hospitality industry.
The implied gap between the current share price of €51.28 and the average target hints at how much weight the market is placing on AI risk and travel demand swings right now. More bullish analysts who sit closer to €82.0 are signalling confidence that distribution volumes, cloud migration benefits and new AI products can support those €1.8b earnings. At the other end, the €51.0 bear case target effectively questions either the ability to reach that profit level or the idea that the stock should re rate to a premium 2029 multiple.
Amadeus IT Group's narrative projects about €8.3b in revenue and €1.8b in earnings by 2029. That profile assumes revenue grows at roughly 7.8% a year and that profit rises by about €0.5b from current earnings of €1.3b.
Uncover why Amadeus IT Group's fair value indicates a 27% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Amadeus IT Group leans heavily on slower hospitality and airline migrations. The most cautious analysts still had revenue reaching about €8.1b and earnings near €1.8b by 2029, yet they paired that with a lower 14.5x P/E. That signals a far cooler mood, and it may shift again after this news.
Explore 2 other Amadeus IT Group fair value estimates, including one that suggests it could be worth just €64.68.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Amadeus IT Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Amadeus IT Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amadeus IT Group's overall financial health at a glance.
Looking for more investment ideas beyond Amadeus IT Group?
If Amadeus IT Group has sharpened your focus on valuation, cash generation and risk, it can help to widen the lens and compare it with other opportunities that fit different profiles.
- Target stronger balance sheets and robust fundamentals by scanning our list of solid balance sheet and fundamentals (204 results) that can help anchor a more resilient portfolio.
- Hunt for mispriced quality by reviewing a curated 614 high quality undiscovered gems that may not yet be widely followed by the market.
- Dial down volatility by concentrating on our 234 resilient stocks with low risk scores that focus on resilience and more stable business profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com