
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Has Changed For Evotec Since Its 61% Fall
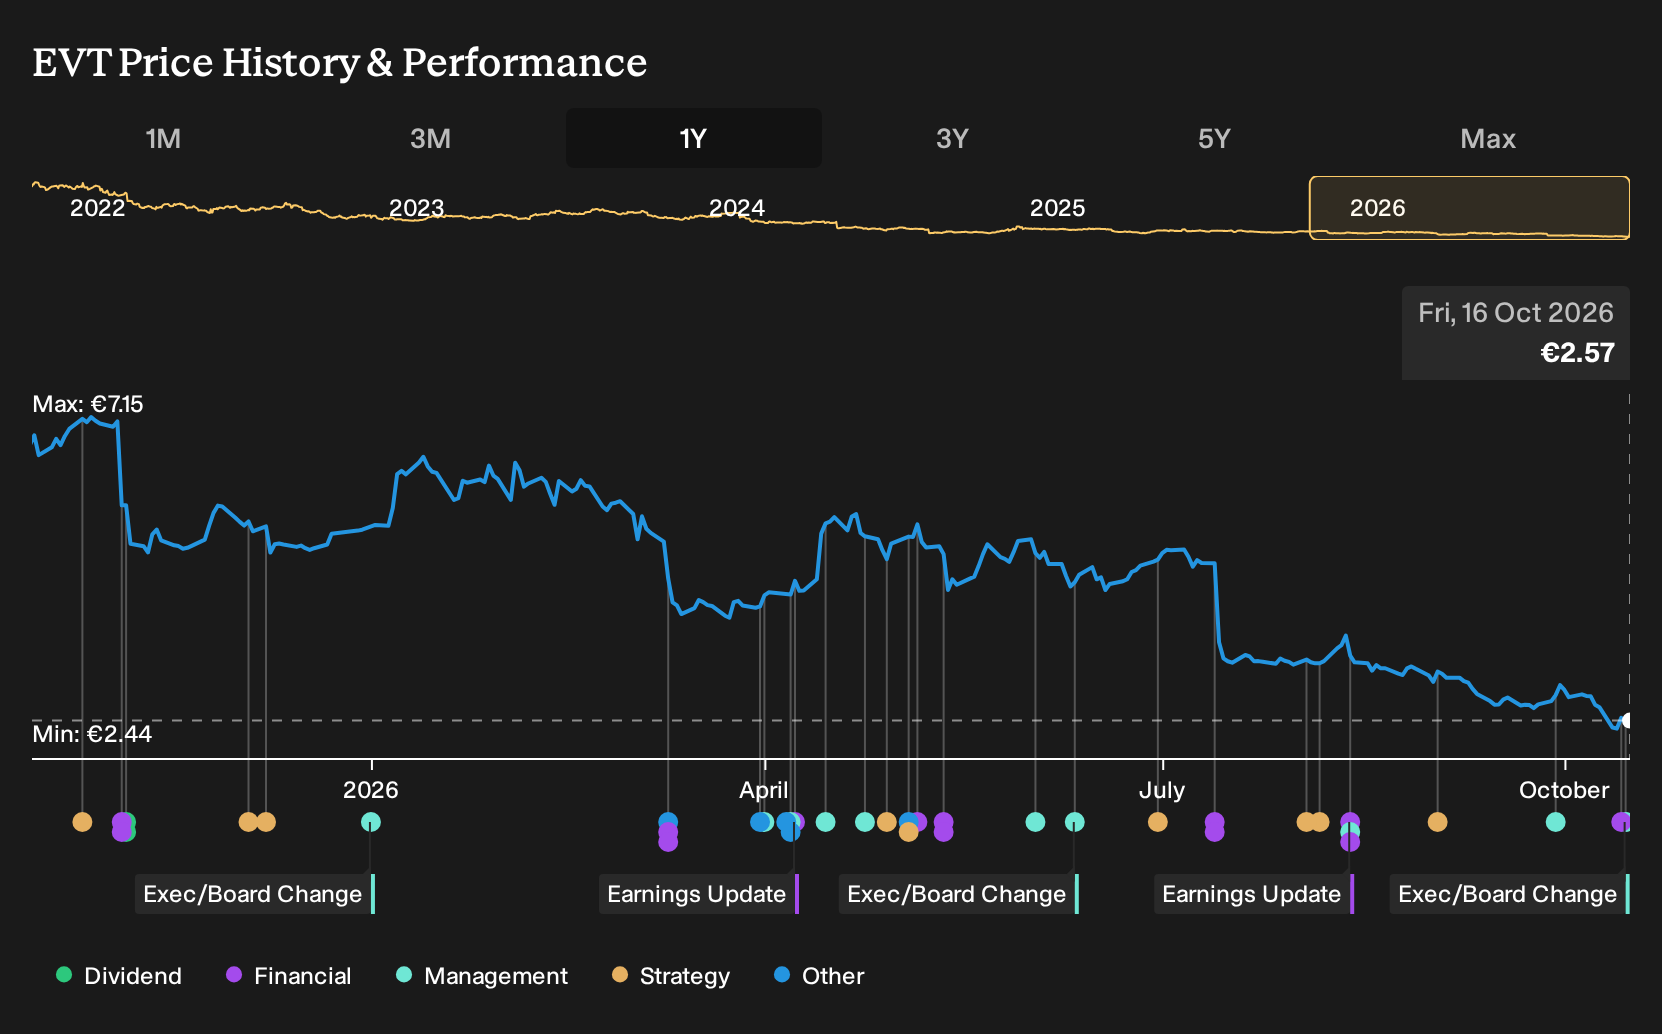
Evotec’s latest news hit hard. The company cut its 2026 revenue and EBITDA guidance after partnership milestones slipped and first half revenue came in lower than the prior year. Holding Evotec over the past year would have meant a 61.0% loss, including dividends. If you had bought in back on 16 October 2025, the question now is whether the AI push and asset light model still justify fresh optimism or call for a reassessment of risk.
Evotec has already moved. Pinpoint other ways to investigate the theme among 127 healthcare AI stocks.
The Two Stories Evotec Investors Were Weighing
The shares cost €6.88 at the start of the period, and anyone looking at Evotec then had to choose which story felt more credible.
The bullish view pointed to a Fair Value of €9.47, essentially a price implied by expectations that revenue could rise 8.3% a year and profit margins could move from a loss to 5.5% within three years. This relied on deeper large pharma partnerships and AI platforms turning into higher margin, recurring income.
The cautious camp worked off a Fair Value of €6 and assumed slower 4.2% annual revenue growth with profit margins eventually reaching 6.6%. That narrative focused on pressure from inflation, regulation, and tougher competition that could squeeze profitability as Evotec shifted toward an asset light setup.
What The Results Changed For The Evotec Debate
Evotec’s cut to its 2026 revenue and EBITDA guidance, together with a 19% drop in first half sales and an adjusted EBITDA loss of €42.7 million, clearly leaned toward the cautious view that focused on pressure on profitability. The Q2 numbers reinforced that picture. Revenue declined to €143.5 million, net income remained in loss territory at €46.6 million, and net margin weakened to 32.5%. Profitability in the bullish case remained unproven.
The key lesson is straightforward. When a thesis depends on margin recovery and an AI or asset light pivot, it is important to check guidance, reported EBITDA, and net margin each period and ask whether they are actually moving toward the target, not just whether the narrative sounds appealing.
What Evotec’s Lower Price Now Asks You To Believe
Today Evotec trades at €2.57, which is far below where holders started a year ago. The selected Narrative’s Fair Value sits above the current price and rests on the idea that partnerships, precision medicine work, and AI enabled platforms can reshape earnings power.
Any buyer now would need to believe Evotec’s asset light shift and cost cuts can turn today’s pressured margins into sustainably higher profitability and recurring revenue.
"Asset-light strategy, expanding precision medicine initiatives, and disciplined cost controls position Evotec for improved profitability, enhanced partnerships, and long-term recurring revenue growth. Disciplined cost management and a successful cost-out program have already resulted in reductions exceeding 600 FTEs and operating expense cuts over €60 million, supporting margin improvement and a return to profitability, with midterm targets of 8-12% revenue CAGR and greater than 20% EBITDA margin, which could increase future earnings and cash flows."
The price and this Narrative do not agree. → Uncover what this Narrative says Evotec is actually worth
Looking Beyond Evotec’s AI Bet
Evotec is leaning hard on AI heavy drug discovery and precision medicine. You could also look at who is building treatments that actually reach patients today.
Across oncology, immunology, and neuroscience, another large healthcare group is pushing a wide mix of therapies and devices. It is spending heavily on research and acquisitions to keep that pipeline stocked.
Those efforts target complex diseases where treatment need is high and alternatives are limited. In several areas, that can give products longer usage and stronger pricing power.
Medtech is part of the story too, from advanced surgery tools to premium eye care. As more procedures and therapies depend on specialized hardware and branded drugs, the role of this diversified player keeps evolving.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 25% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com