
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Arlo Technologies (ARLO) Stock Dropped, So What Is Driving Attention Now?
Arlo Technologies (ARLO) caught investor attention after reporting Q2 revenue of US$155.9 million, up 20.5% year on year, with earnings and guidance both ahead of analyst expectations.
Despite the upbeat quarter, Arlo Technologies’ share price has drifted, with a 1-month share price return down 8.2% and year to date also lower, while the 1-year total shareholder return has declined 30.7% even as the 3-year and 5-year total shareholder returns remain firmly positive. At the latest close of US$12.16, that disconnect between improving near term results and weaker recent performance suggests the market is still reassessing Arlo’s growth potential and risk profile after a strong multi year run.
Scan how the market is treating other fast growing but recently sold off tech stocks using our curated list of 33 high quality undervalued stocks.
Bulls see Arlo Technologies as a solid growth story temporarily on sale, while bears point to the sharp pullback and question durability. Which side do the current valuation markers support next?
Most Popular Narrative: 43% Undervalued
Analysts following Arlo Technologies see a fair value of $21.40 against the latest close at $12.16. As a result, the current narrative leans toward a wide valuation gap that hinges on the subscription engine really delivering.
Continual migration of subscribers to higher-priced AI-driven service tiers (Arlo Secure 6) and the corresponding increase in ARPU (now over $15, up 26% y/y) reinforces the long-term shift to recurring, high-margin (85% non-GAAP service margin) subscription revenue, supporting expanding net margins and earnings visibility.
See why 12 investors see Arlo Technologies as 43% undervalued.
Result: Fair Value of $21.40 (UNDERVALUED)
Still, the Arlo Technologies story could be knocked off course if hardware price competition bites into margins or if customers tire of recurring subscription fees.
Find out about the key risks to this Arlo Technologies narrative.
Another View: Valuation Check Against Earnings
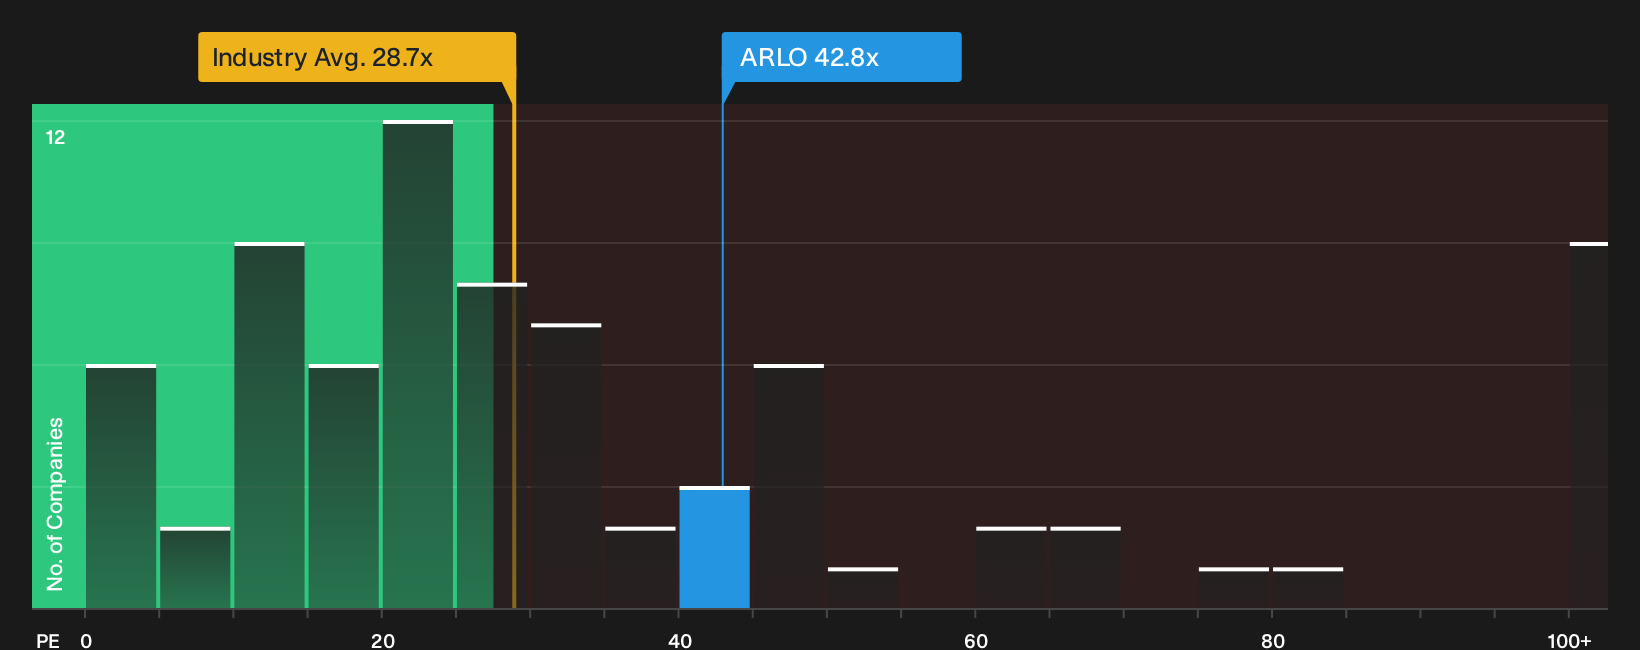
There is a catch. On earnings, Arlo Technologies trades on a P/E of about 42.8x, while the US Electronic industry sits nearer 28.7x and the fair ratio points to 19.5x. That premium suggests investors are already paying up, so how much safety margin is really left in the story?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Arlo Technologies can create plenty of noise, so move quickly, review the full data for yourself, and weigh up 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Arlo Technologies?
If Arlo Technologies has sharpened your thinking, do not stop here. Broader context from other opportunities can help you stress test your thesis and spot gaps before capital is on the line.
- Target higher conviction opportunities by scanning a 20 high quality undiscovered gems that many investors may not be watching yet.
- Build a sturdier core to your portfolio by focusing on businesses in the list of solid balance sheet and fundamentals (25 results) that can better handle shocks.
- Calm the volatility in your holdings by filtering for the 32 resilient stocks with low risk scores that align with a more measured risk profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com