
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Defensive Dividend Stocks For Steady Income In Volatile Markets
Markets feel jumpy as war risks spread, emerging economies wrestle with higher debt costs, and enthusiasm around AI collides with bubble worries. Income investors are quietly looking for cover. Reliable dividends and steadier price swings can feel like a rare anchor when headlines turn messy. This article walks through three stocks from a defensive, developed-market screener that appear closely exposed to these cross currents and explains how each might matter for your portfolio decisions.
The three dividend stocks covered next are just a sample, and the full screen surfaced 26 more developed-market companies with similarly income-focused stories that are not unpacked here. To go straight to the source, analyze, filter, and identify your highest-conviction ideas inside the Defensive Dividend-Paying Stocks in Developed Markets screener.
EnBW Energie Baden-Württemberg (XTRA:EBK)
EnBW Energie Baden-Württemberg is an integrated German utility that fits the defensive dividend theme through regulated power, grid and customer businesses in a developed market. It generated about €20b from Sustainable Generation Infrastructure, €13.5b from Smart Infrastructure for Customers and €9.4b from System Critical Infrastructure, with a market value of roughly €21.9b.
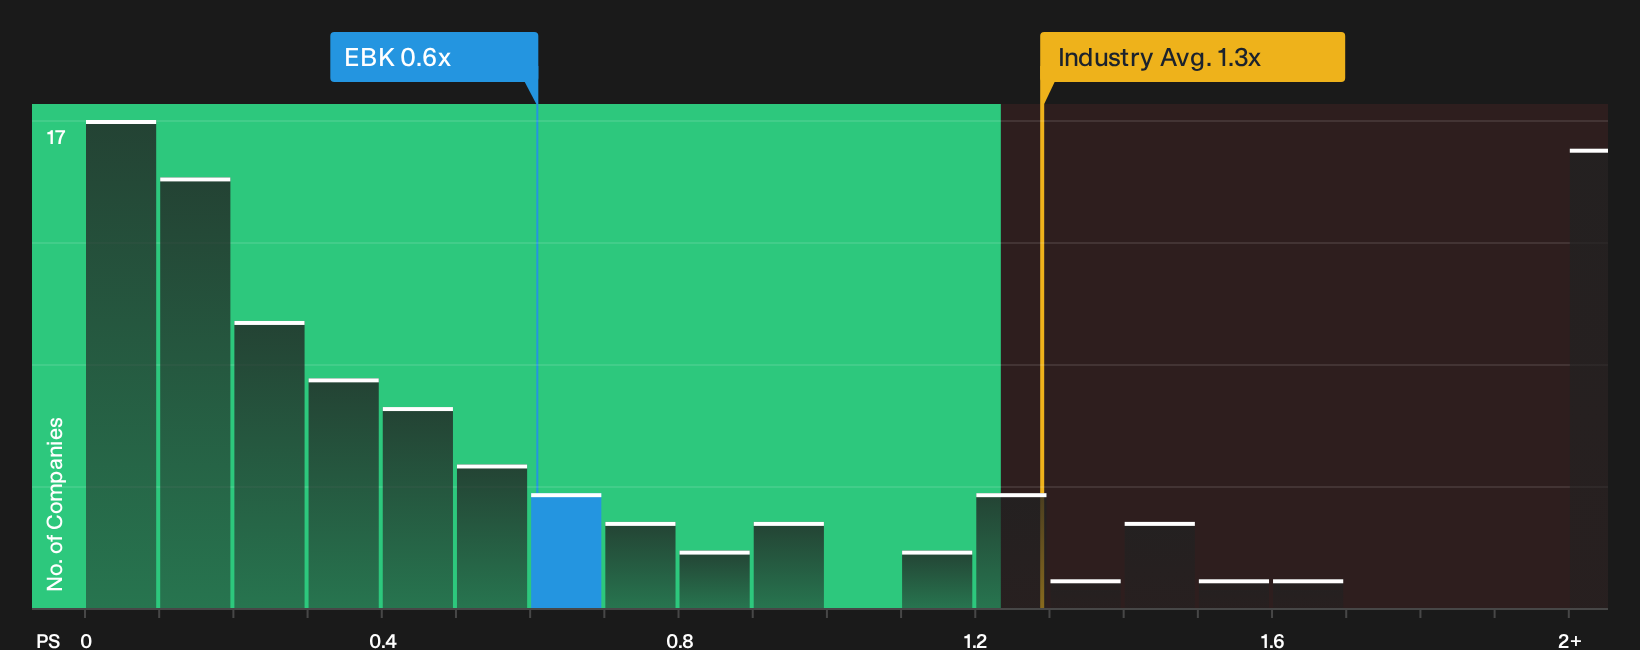
EnBW Energie Baden-Württemberg brings together power generation, grids and customer supply in a single, regulated-heavy utility. This is the type of business many income seekers look to when risk appetite fades. The stock trades on a low P/S of about 0.6x compared with European peers, although the group is currently loss making and dividend coverage from earnings and cash flow looks strained. A large, ongoing build out of fast-charging and grid assets could help determine whether that apparent value and income profile holds together if a single unseen pressure shifts direction.
If that pressure point matters to you, review the EnBW Energie Baden-Württemberg financial health report to see how EnBW Energie Baden-Württemberg's balance sheet and cash flows line up against its dividend ambitions.
Target Healthcare REIT (LSE:THRL)
Target Healthcare REIT owns a UK portfolio of modern, purpose-built care homes that fit the defensive dividend theme through long leases and needs based demand. The trust earns about £72 million from property investment and has a market value near £710 million.
Target Healthcare REIT gives you exposure to UK care homes where income is anchored by long leases and a needs based tenant base, which is exactly what many investors look for in a defensive, developed-market income strategy.
"Structural growth in the over 85 population and a rising proportion requiring residential care is described as underpinning high occupancy and supporting continued inflation linked rental uplifts, which is presented as a basis for sustained revenue and earnings resilience."
The real test for Target Healthcare REIT is how one unseen pressure on operators feeds back into rent cover, margins and future dividend decisions.
If you want to see how that pressure could be accelerating or masking the real story, read the full narrative for Target Healthcare REIT for the next layer of insight.

New Jersey Resources (NJR)
New Jersey Resources is a US$5.3b regulated natural gas distributor with a defensive, dividend focused profile that fits this screener’s aim for steadier, utility style income. Most revenue comes from Natural Gas Distribution at about US$1.4b, with Energy Services at US$525 million and Clean Energy Ventures at US$127 million adding diversification.
New Jersey Resources edges into this defensive dividend screen as a regulated, utility-like gas distributor with a growing mix of fee based and clean energy earnings. This gives income seekers a different way to lean into stability without relying solely on classic electric utilities.
"New contracts and capacity additions at Adelphia Gateway and Leaf River are expected to more than double Storage & Transportation net financial earnings between fiscal 2025 and 2027."
Any change in a single assumption about future cash generation and funding costs is likely to have a meaningful impact on how investors perceive the dividend profile.
When that single assumption starts to shift, the full narrative for New Jersey Resources shows how New Jersey Resources could see risks, cash flows and valuation expectations rapidly decoupling.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first and slow research often gets caught chasing prices after the breakout. Scan what is still under the radar for now. Act now.
- Spot income workhorses before yields start dropping by scanning a curated set of 216 dividend fortresses that aim to keep payments coming while prices swing around.
- Track powerful computing demand as it builds and filter through 55 AI infrastructure stocks that connect directly to data centers, chips and the grid supporting AI momentum.
- Go after early-stage automation leaders by screening 91 robotics and automation stocks that could benefit if robots and smart factories move from concept to everyday infrastructure.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com