
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Eastman Chemical (EMN) JPMorgan Downgrade
- Eastman Chemical has seen its shares decline over the past five years as investors reassess the business against its recent free cash flow of about US$418.5 million and its long term cash generation profile.
- The company’s valuation now leans heavily on how effectively it converts that cash flow base into durable earnings, even as analysts such as JPMorgan reassess the outlook.
- We will now explore how Eastman Chemical's investment narrative could be influenced by JPMorgan's more cautious rating stance on the stock.
Scan how Eastman Chemical stacks up on cash generation and valuation next to other potential opportunities by reviewing our curated list of 33 high quality undervalued stocks.
Eastman Chemical Investment Narrative Recap
To stay invested in Eastman Chemical, you need to be comfortable with a specialty materials group that leans on steady free cash flow and execution on cost cuts, debottlenecks, and circular plastics projects. The key near term swing factor is how reliably that US$418.5 million of recent free cash flow translates into earnings, provided demand in core end markets stays healthy enough to absorb higher value products.
The biggest operational risk right now sits in external pressures that could squeeze pricing and volumes, especially if global trade frictions, Chinese overcapacity, or softer Fibers demand persist. JPMorgan’s more cautious stance mainly reframes expectations rather than changing the practical near term catalyst; that still depends on delivering cost savings and sustaining Chemical Intermediates spreads.
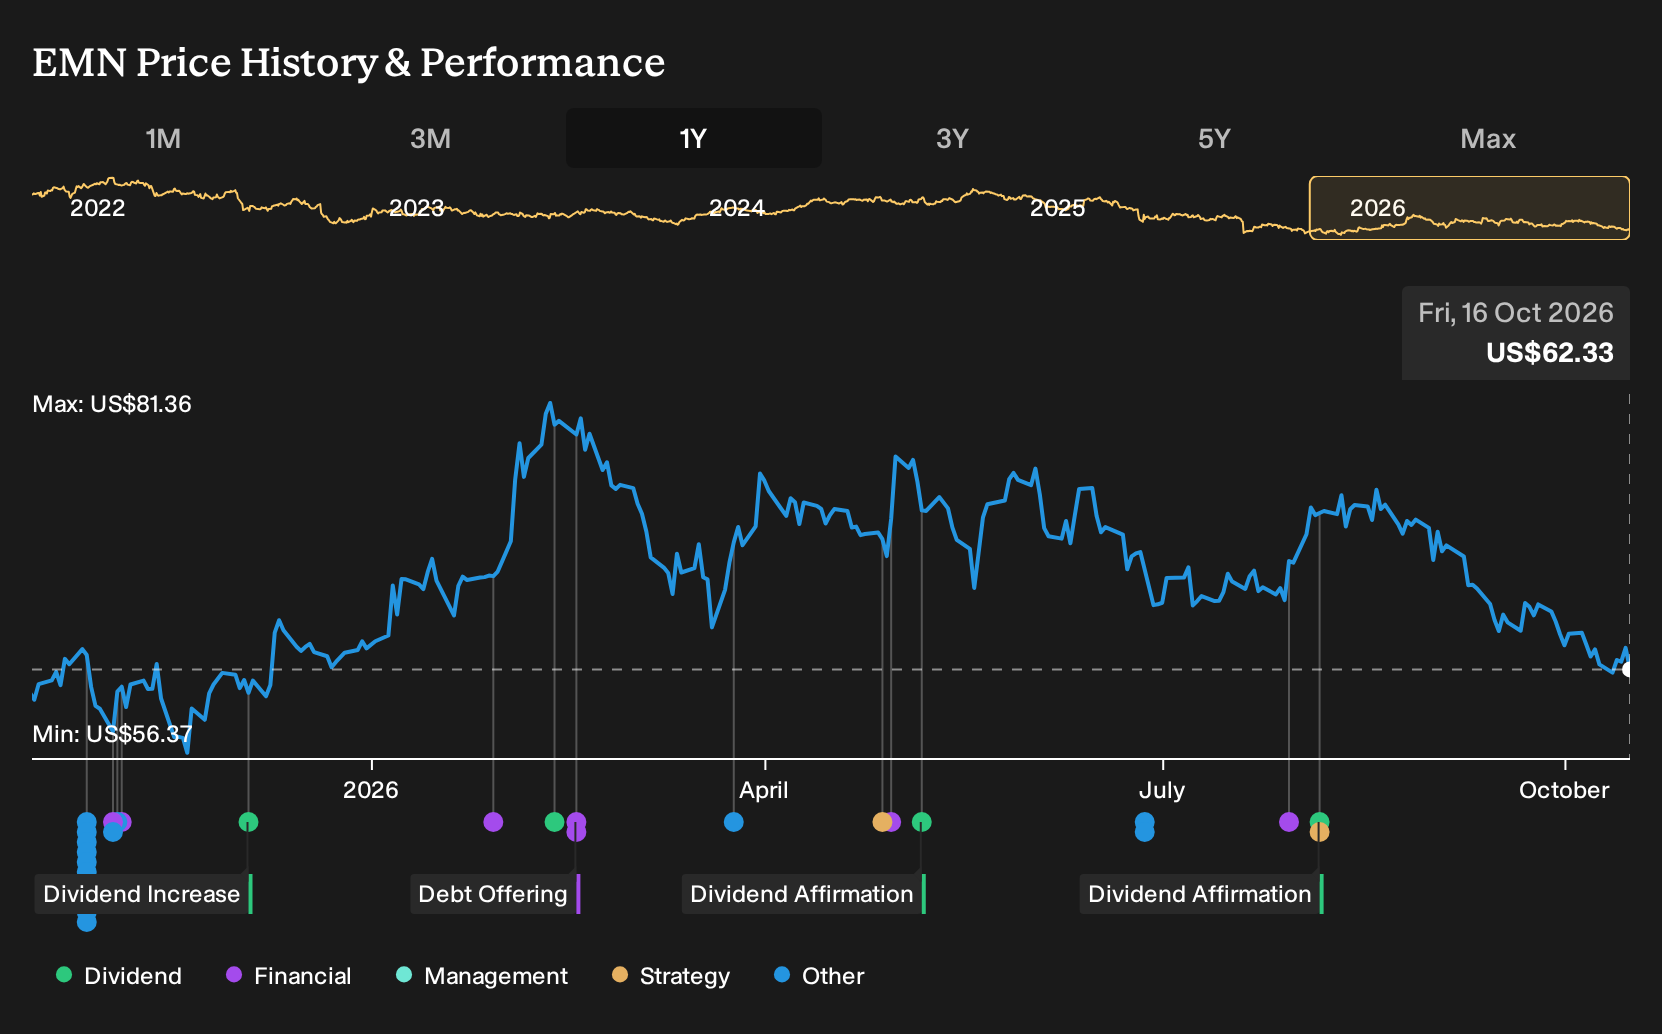
In that context, the most relevant recent development is the DCF work suggesting Eastman Chemical trades below an estimate of its future cash flow value, with the share price at US$62.33 versus a modelled value of about US$110.65. That view rests on the business continuing to generate and expand cash flows from projects such as Kingsport methanolysis, cost programs, and debottlenecks across Advanced Materials and Chemical Intermediates.
JPMorgan’s downgrade to Neutral with a US$66 price objective fits into that picture as a more muted interpretation of the same operating story rather than a new thesis. For you, the practical question is whether execution on Renew growth, margin improvement, and future projects such as Longview ethylene to propylene can offset risks from weaker Fibers, thinner spreads if feedstocks ease, and debt that is not fully covered by operating cash flow.
Eastman Chemical's current analyst script points to about US$9.4b of revenue and US$841.0 million of earnings by 2029. This outlook is built on an assumed 2.1% yearly rise in sales and an earnings increase of roughly US$399.0 million from the US$442.0 million generated today.
Uncover why Eastman Chemical's fair value indicates a 24% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternative angle on Eastman Chemical leans hard into Kingsport methanolysis as a potential upside catalyst. The most optimistic analysts were pencilling in revenue of about US$10.1b and earnings around US$944.0 million by 2029 before this downgrade. You can treat JPMorgan’s move as a prompt to compare those projections with more cautious views, and then decide which story feels more realistic to you.
Explore 3 other Eastman Chemical fair value estimates, including one that suggests up to 78% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Go with your instincts.
- A great starting point for your Eastman Chemical research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Eastman Chemical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eastman Chemical's overall financial health at a glance.
Looking for more investment ideas beyond Eastman Chemical?
Once you have formed a view on Eastman Chemical, it can help to compare that thesis with other listed businesses that have different risk and income profiles using the Simply Wall St Screener.
- For investors who care most about balance sheet resilience and fundamental strength, scan our list of solid balance sheet and fundamentals (25 results) to see which companies clear a similar quality bar.
- If you want to focus on price versus underlying worth, compare Eastman Chemical to a 33 high quality undervalued stocks that combine strong cash generation with more modest expectations reflected in their share prices.
- For income focused portfolios, check out a 8 dividend fortresses that prioritise generous yields backed by robust underlying finances.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com