
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Estée Lauder Companies (EL) Fairly Valued On Bobbi Brown Leadership Change?
Estée Lauder Companies (EL) has put Bobbi Brown’s future in new hands. On 8 October 2026, the group appointed Gaétane Baudry as Senior Vice President and Global General Manager of the brand.
Estée Lauder Companies’ recent leadership refresh at Bobbi Brown comes at a moment when the shares are trying to rebuild confidence, with a 90-day share price return of 24.99% and a 30-day gain of 11.89%. However, year-to-date performance remains slightly negative and the 5-year total shareholder return is still down 65.54%, signalling short term momentum in contrast to a much weaker long term journey.
Spot parallels or contrasts with Estée Lauder Companies by scanning hand-picked consumer and beauty stocks that screen well on cash flows and balance sheets in our 33 high quality undervalued stocks.Estée Lauder Companies still owns a broad, global portfolio of beauty brands, yet the stock trades far below its 2022 high. After the Bobbi Brown shakeup, does the current valuation fairly reflect the slimmer business?
Most Popular Narrative: 2.3% Undervalued
Estée Lauder Companies closed at $104.54 against a most-followed fair value estimate of $107.04, which suggests only a modest valuation gap but still leaves the recovery story in focus.
Estée Lauder Companies is progressing its multi year Profit Recovery and Growth Plan and One ELC operating model, which has already lifted gross margin by nearly 400 bps between fiscal 2024 and fiscal 2026 and expanded operating margin by 320 bps to 11.2%. This points to further structural cost efficiencies that could support future operating margin and earnings.
See why 102 investors see Estée Lauder Companies as 2% undervalued.
Result: Fair Value of $107.04 (UNDERVALUED)
Still, the Estée Lauder Companies narrative depends on travel retail staying resilient and on restructuring delivering savings without hurting execution or brand equity.
Find out about the key risks to this Estée Lauder Companies narrative.
Another View: Estée Lauder Companies Through The Sales Multiple
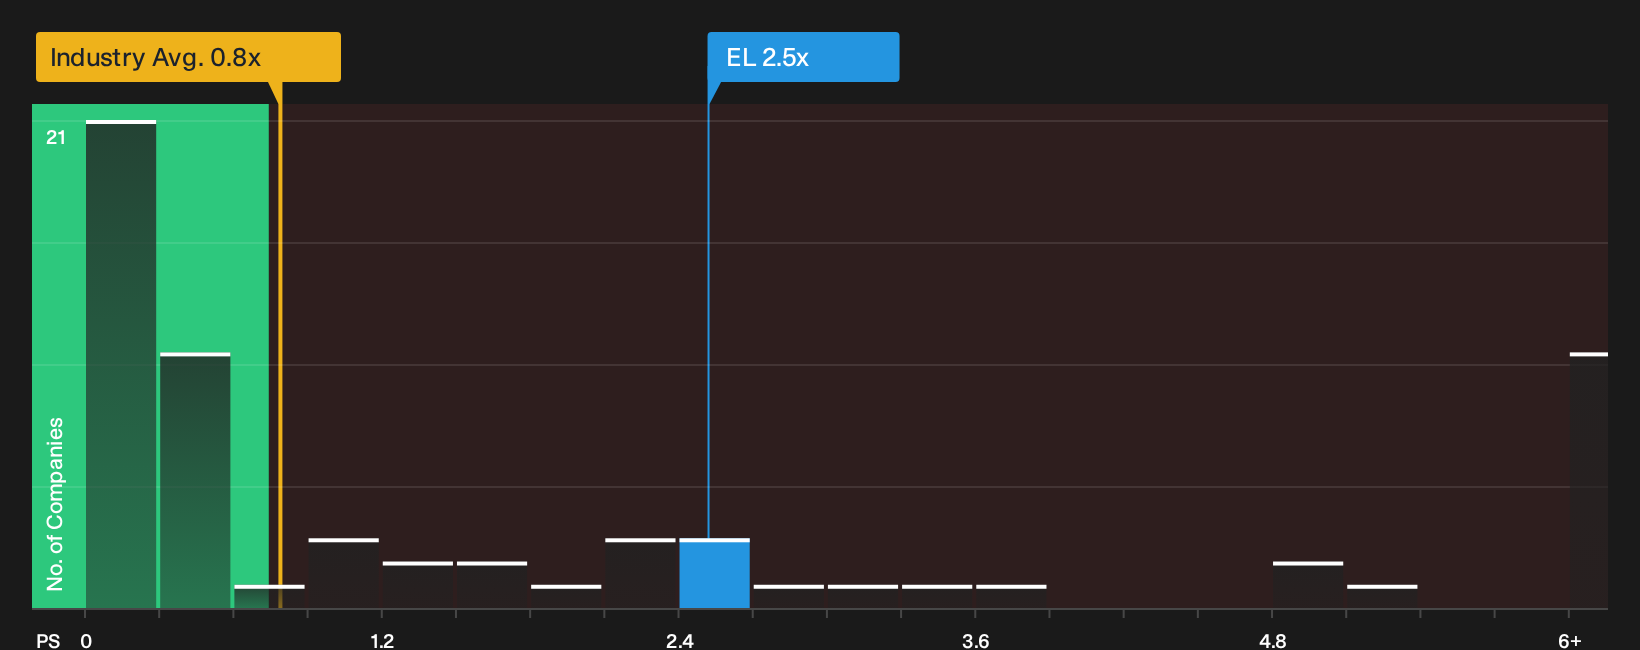
The DCF work suggests Estée Lauder Companies is modestly undervalued, yet its P/S ratio of 2.5x tells a tougher story. That price tag sits above the US Personal Products industry at 0.8x, peers at 2.3x, and even a fair ratio of 2.4x. Is investors’ optimism here an extra buffer or an extra risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Estée Lauder Companies can either paralyse you or push you to test the numbers yourself and move fast. Balance that caution and optimism by weighing 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Estée Lauder Companies?
If Estée Lauder Companies leaves you uncertain, you could broaden your watchlist with additional ideas that align with your risk tolerance and income objectives.
- Explore potential income opportunities by reviewing a curated set of higher-yielding payers through 8 dividend fortresses.
- Look for potential value by filtering companies with strong cash flows and attractive valuations using 33 high quality undervalued stocks.
- Focus on financial strength by reviewing businesses with robust balance sheets in the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com