
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Ingredion (INGR) Could Be 11% Overvalued As Tate And Lyle Deal Shapes View
Ingredion (INGR) has traded under pressure this year, with the share price down about 11% year to date and roughly 17% over the past 12 months. That pullback is drawing fresh attention to what the ingredients producer actually delivers today.
Recent trading hints at a bit of stabilisation, with a 7 day share price return of 2.99% and a 1 day move of 0.68% from a US$97.93 close. However, the 1 year total shareholder return is still down 16.73%, while the 3 and 5 year total shareholder returns of 17.65% and 16.36% point to a much more resilient long term picture.
Scan other ingredient and food producers that have also been under recent pressure, yet still screen well on quality, using our hand picked list of solid balance sheet and fundamentals (25 results) as a comparison set.
Bulls see Ingredion’s recent pullback as a discount on a steady ingredients franchise, while bears read it as justified repricing. Which side do the current valuation signals support next?
Most Popular Narrative: 11% Overvalued
Ingredion is trading at $97.93, while the most followed valuation story on the stock pegs fair value closer to $88.23. That gap highlights a clear tension between a solid ingredients franchise today and what investors are paying for its future mix shift.
The acquisition of Tate & Lyle has the potential to transform Ingredion from a predominantly commodity-oriented starch and sweetener processor into a more global specialty ingredients platform. The primary upside comes from mix shift toward higher-margin functional ingredients, meaningful cross-selling opportunities with global CPG customers, and scale-driven cost synergies.
See why 8 investors see Ingredion as 11% overvalued.
Result: Fair Value of $88.23 (OVERVALUED)
Still, the Ingredion story carries real pressure points, including integration risk around Tate & Lyle and any setback to margin targets that underpin the long term thesis.
Find out about the key risks to this Ingredion narrative.
Another View: Ingredion’s Earnings Multiple
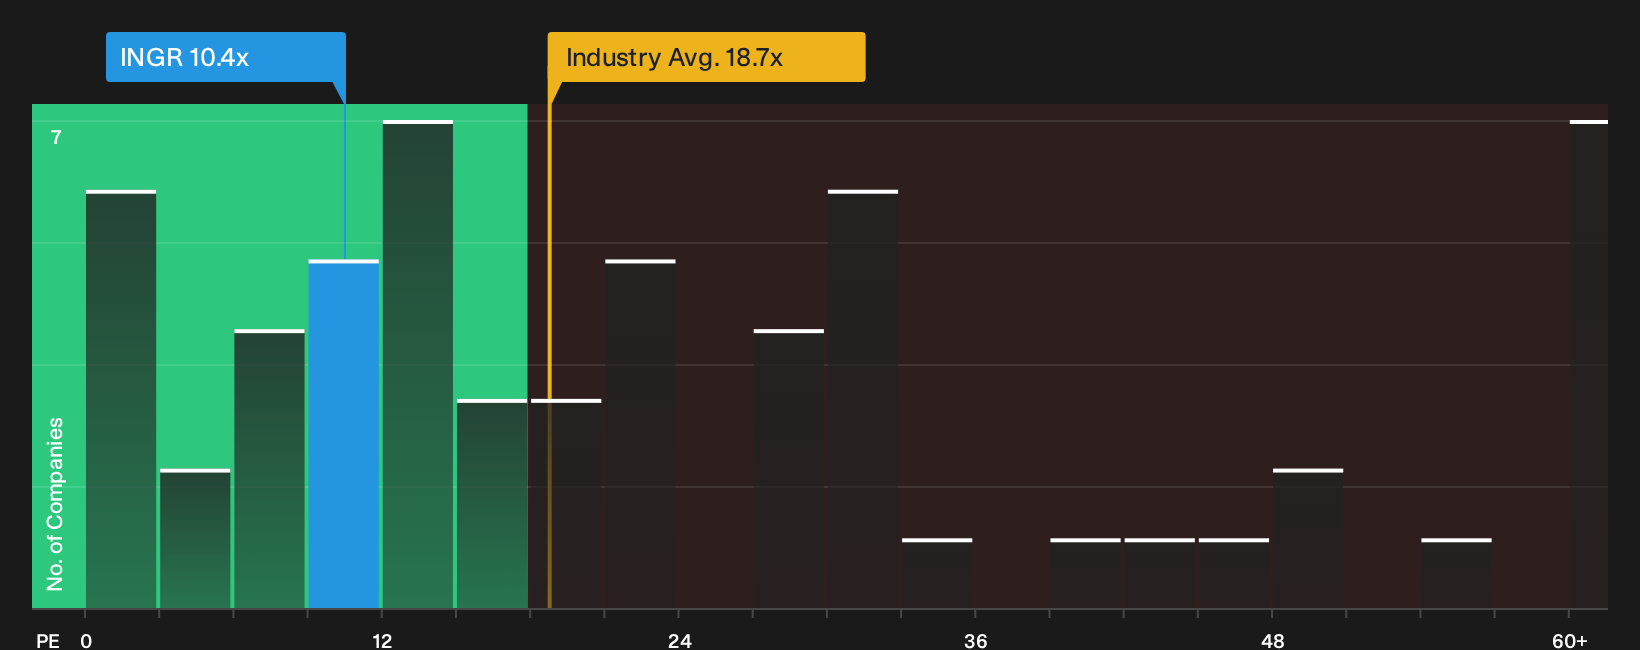
While the most followed narrative tags Ingredion as 11% overvalued against a fair value of $88.23, the current P/E of 10.4x tells a different story. The ratio sits well below peers at 25x, the wider US Food industry at 18.7x, and even an estimated fair ratio of 16.5x. That kind of gap can point to either a bargain on steady earnings or a warning that the market is bracing for disappointment. Which explanation makes more sense to you given the recent acquisition risks?
See what the numbers say about this price in our valuation breakdown, then compare it against other consumer and food producers with similar earnings profiles using the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment looks split in the article so far, which is exactly why it helps to move quickly, test the data yourself, and pressure test Ingredion’s setup against the potential upsides that have investors interested through the 5 key rewards
Looking for more investment ideas beyond Ingredion?
You have already done the work on Ingredion. Do not stop there. Broaden your watchlist now so you are not reacting after the next move.
- Target long term compounding potential by scanning a curated pool of quality opportunities through the 33 high quality undervalued stocks.
- Secure more dependable portfolio income by focusing on companies that feature the kind of payouts highlighted in the 8 dividend fortresses.
- Guard against unnecessary downside risk by filtering for resilient businesses with the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com