
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Vericel (VCEL) And The Burn Care Story Behind Its Undervalued View
Vericel (VCEL) has drawn attention after the latest trading data showed modest single-digit moves over the past week and month, while the past 3 months told a different story.
Vericel’s recent pullback, with a 1-day share price return of down 2.17% and a 90-day share price return of down 12.53%, contrasts with a year-to-date share price return of 12.69% and a 1-year total shareholder return of 13.62%. Together, these figures point to longer term momentum still holding up despite shorter term volatility.
Scan for other healthcare names showing similar pullbacks with intact longer term performance using our hand picked 33 healthcare AI stocks as a starting universe.
Vericel appears to be a solid specialist in burn and sports medicine therapies, yet the recent 90 day slide raises a simple question: Is a business with this profile being offered at an appealing price or not?
Most Popular Narrative: 34% Undervalued
Vericel’s most followed valuation story pegs fair value at about $60.57 per share, compared with the last close at $40.13. This narrative places significant emphasis on the company’s ability to scale both cartilage repair and burn care.
Burn Care’s evolution into a second growth and cash engine, with NexoBrid supported by a BARDA agreement valued at up to about $197m to $200m over 10 years and options for further procurement, positions Vericel to add a partially non cyclical revenue stream that can improve earnings visibility.
See why 8 investors see Vericel as 34% undervalued.
Result: Fair Value of $60.57 (UNDERVALUED)
Still, the Vericel narrative depends heavily on just a few therapies, and a slower than expected ramp after the Burlington facility and sales force build out could pressure margins.
Find out about the key risks to this Vericel narrative.
Another View: Vericel Looks Expensive On Earnings
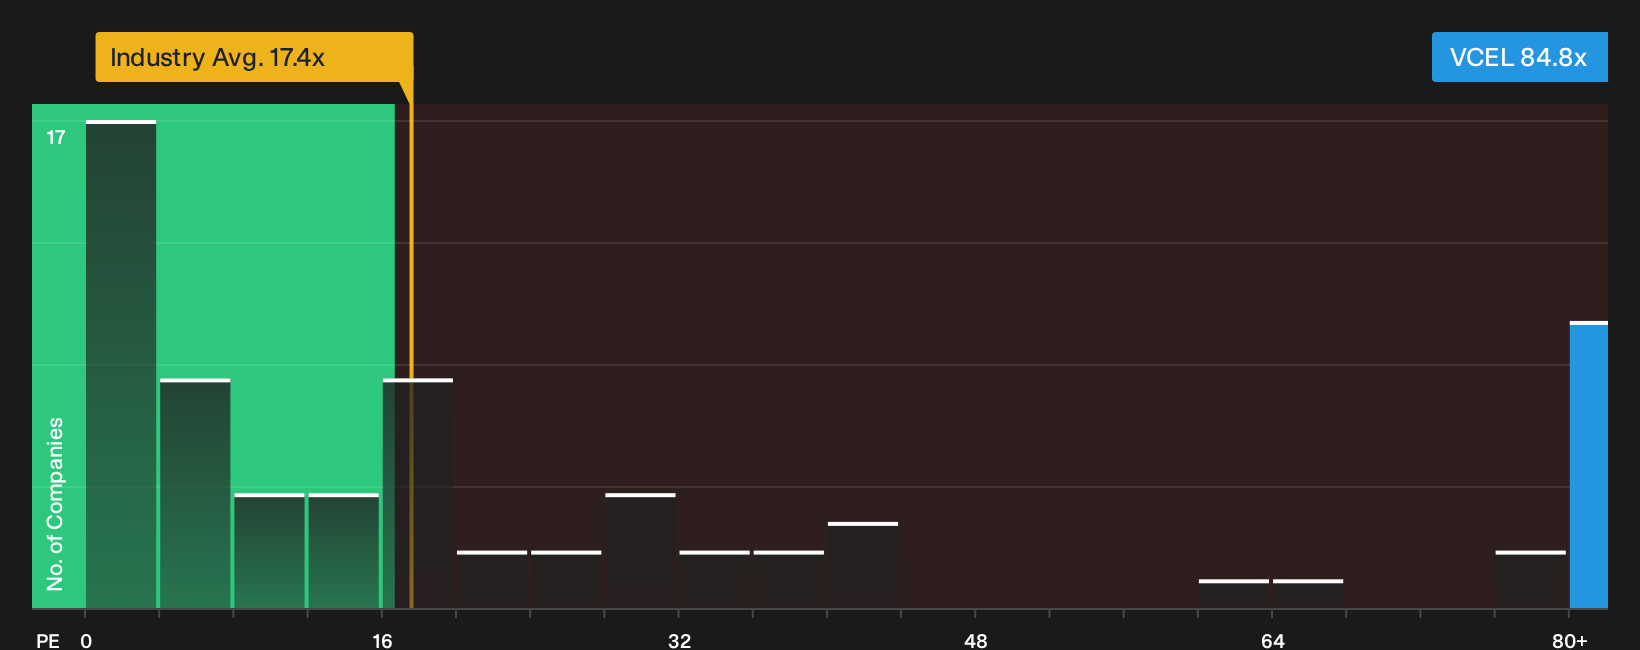
On the flip side of that $60.57 fair value story, Vericel trades on a P/E of 84.8x. The biotech industry sits closer to 17.4x, peers average about 15x, and the fair ratio is 24x. That gap suggests investors are paying up for growth. Is that premium comfort or concern for you?
To see how those valuation gaps stack up in more detail, including where the ratio could drift toward over time, take a look at See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The Vericel story has shown mixed messages so far. If you want to act before sentiment shifts again, start by checking the 3 key rewards.
Looking for more Vericel sized investment ideas?
Vericel offers one angle on healthcare risk and reward. You owe it to your capital to scan a broader field before settling on any decision.
- Target potential mispricing by reviewing companies that screen as 33 high quality undervalued stocks and could offer a margin of safety if the fundamentals hold up.
- Protect the downside by focusing on businesses with robust finances highlighted in our list of solid balance sheet and fundamentals (25 results) so short term swings feel less painful.
- Get ahead of the crowd by scouting 20 high quality undiscovered gems that combine quality fundamentals with low current attention from the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com