
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Starbucks (SBUX), Why Is Its Latest Update Drawing Fresh Attention?
Starbucks (SBUX) just paired solid comparable sales gains in North America with a decision to trim its fiscal 2026 store expansion plans, closing about 250 underperforming locations and booking related restructuring charges.
The share price reaction reflects that broader story. Starbucks shares are up 7.5% over the past week and 16.1% year to date on a share price return basis, while the 1 year total shareholder return of 17.2% contrasts with a weaker 5 year record, suggesting momentum has picked up recently after a tougher stretch.
Spot patterns in how investors are reacting to Starbucks and similar consumer brands by scanning the hand-picked 33 high quality undervalued stocks that pair solid cash flows with stronger balance sheets.The recent jump in Starbucks shares can be read two ways. Is the market finally catching up with how the business is running, or are investors simply leaning harder into a changing story on sentiment as the valuation piece comes into focus?
Most Popular Narrative: 13% Undervalued
On the most followed narrative, Starbucks screens close to its $112.23 fair value estimate, with the last close at $97.52 and a discount rate of 8.83% applied to future cash flows.
The Back to Starbucks plan, including Green Apron Service, standardized store scorecards, and a $2b cost-savings program through fiscal 2028, is still in progress and is expected to continue affecting operating margins and earnings as more of the targeted savings and process changes flow through the P&L.
See why 230 investors see Starbucks as 13% undervalued.
Result: Fair Value of $112.23 (UNDERVALUED)
Still, the Starbucks story could shift quickly if unionisation pressures keep store level costs elevated, or if further legal and regulatory challenges emerge.
Find out about the key risks to this Starbucks narrative.
Another View: Starbucks Through The P/E Lens
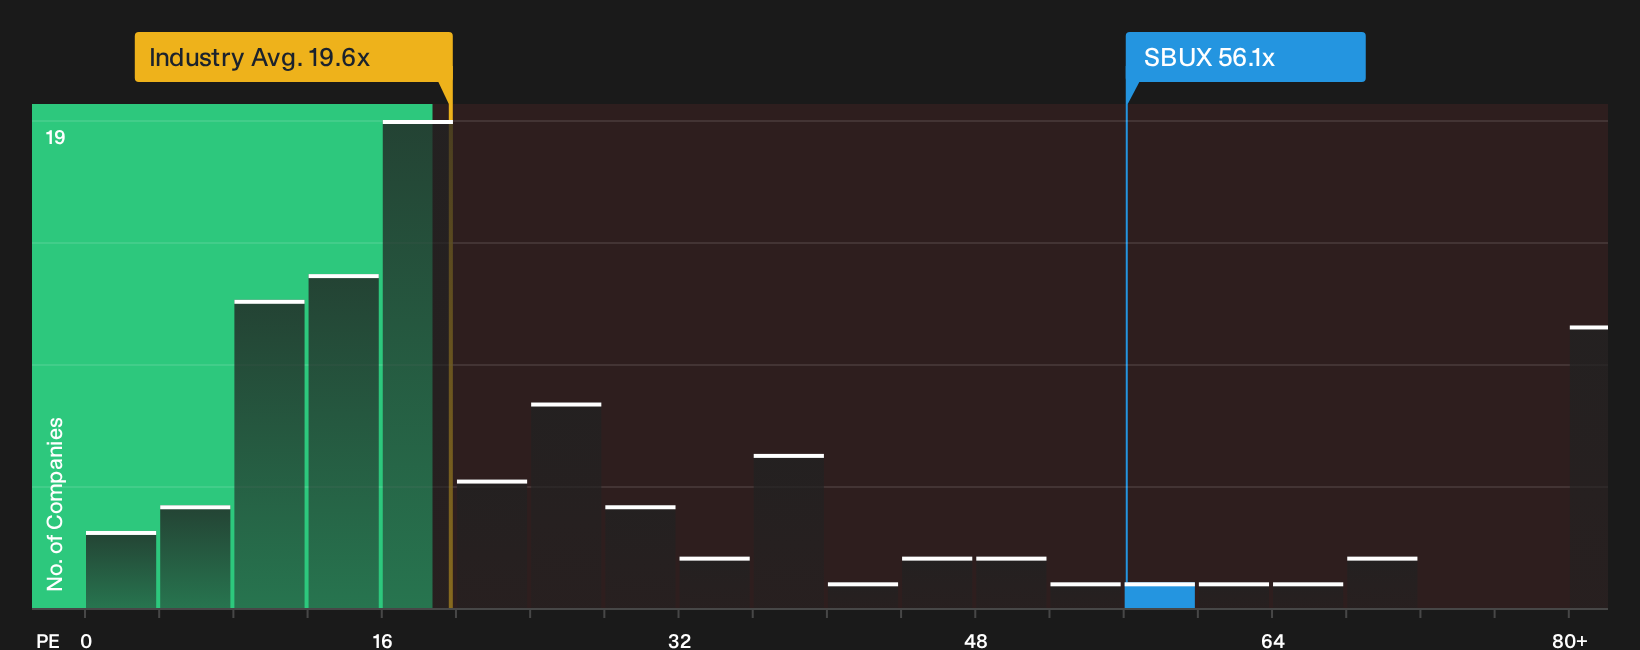
There is a catch. While the SWS DCF model points to Starbucks trading close to its fair value, the current P/E of 56.1x is far richer than the US Hospitality industry at 19.6x, the peer average at 40.6x, and even the 32.5x fair ratio level that some investors may use as a reference point.
If sentiment cools and the share price drifts nearer that reference ratio, the reset implied by those gaps could be painful for holders who are leaning hardest on the DCF story for comfort. Alternatively, this valuation may simply reflect the premium that investors are willing to pay for the Starbucks brand.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in Starbucks right now is mixed, with real enthusiasm sitting beside clear concerns about future risks and rewards. Take a close look at the data, stress test your own assumptions, then weigh up the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Starbucks?
If Starbucks has you rethinking how you build a watchlist, use that momentum. Put the same scrutiny on other opportunities before the market does.
- Target stronger potential upside by reviewing a curated set of companies trading below their estimated worth through the 33 high quality undervalued stocks.
- Strengthen your income stream by scanning stocks that aim to combine yield with resilience using the 8 dividend fortresses.
- Protect your downside by focusing on businesses that score well on stability with the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com