
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Franco Nevada (TSX:FNV) Could Be 15% Undervalued After Gold Price Strength
Why Franco-Nevada Is Back On Investor Radar
Franco-Nevada (TSX:FNV) is back in focus after recent commentary highlighted projected third quarter earnings growth of 36.4%. Investors are watching Cobre Panamá deliveries and new royalty investments tied to record gold prices.
Recent headlines around record gold prices, new royalty deals and the Cobre Panamá update have arrived alongside a 90 day share price return of 22.49% and a 1 year total shareholder return of 21.59%. Franco-Nevada also carries a 5 year total shareholder return of 103.73%, pointing to momentum that has been building rather than fading.
Scan beyond Franco-Nevada and size up other royalty rich and cash flow focused miners with the 36 elite gold producer stocks that are also reacting to record bullion prices and portfolio updates.
Franco-Nevada’s royalty engine looks strong on paper and the recent 90 day surge reflects that story. The real tension now is simple: Are you paying a fair price for that strength at today’s CA$344.54 share level?
Most Popular Narrative: 15% Undervalued
Franco-Nevada’s most followed valuation storyline pins fair value at CA$404.97, above the recent CA$344.54 close, which sets up a bullish skew in the debate without ignoring risk.
Recent and ongoing acquisitions of high-quality, long-life assets (e.g., Cote Gold, Arthur/AngloGold's Nevada projects, Yanacocha, Western Limb) have substantially diversified the portfolio, decreasing operational risk and underpinning a stronger, more stable growth trajectory for revenues and cash flow. The company's strong balance sheet, high cash flow generation, and conservative financial management position it to capitalize on market dislocations and seize attractive, distressed or strategic royalty/streaming deals, enabling compounding returns and supporting higher net margins over time.
See why 49 investors see Franco-Nevada as 15% undervalued.
The fair value estimate of CA$404.97 is built on a 7.89% discount rate applied to analyst forecasts for revenue, earnings and margins, rather than a simple P/E shortcut. Analysts in this framework are assuming 9.2% annual top line growth, profit margins rising toward 69.4% and earnings of about US$2.1b by 2029, which together justify a future P/E of 33.3x in their model.
Against that backdrop, the current CA$344.54 price sits close to the CA$345.62 future cash flow value from the SWS DCF model. This marks Franco-Nevada as trading roughly in line with that separate cash flow estimate even while the narrative-based fair value is materially higher. That split highlights the key question for you as a shareholder or potential investor: how much weight to give to premium assumptions on growth and profitability compared with a more conservative cash flow view.
Result: Fair Value of CA$404.97 (UNDERVALUED)
Still, Franco-Nevada’s story leans heavily on gold price strength. Concentrated exposure to assets like Candelaria and Cobre Panamá could quickly challenge that bullish narrative.
Find out about the key risks to this Franco-Nevada narrative.
Another View: Franco-Nevada Looks Expensive On Earnings
Fair value models paint Franco-Nevada as modestly cheap, with the CA$344.54 share price sitting around 0.3% below an estimated cash flow value of CA$345.62. The earnings multiple tells a tougher story and puts more pressure on that undervalued label.
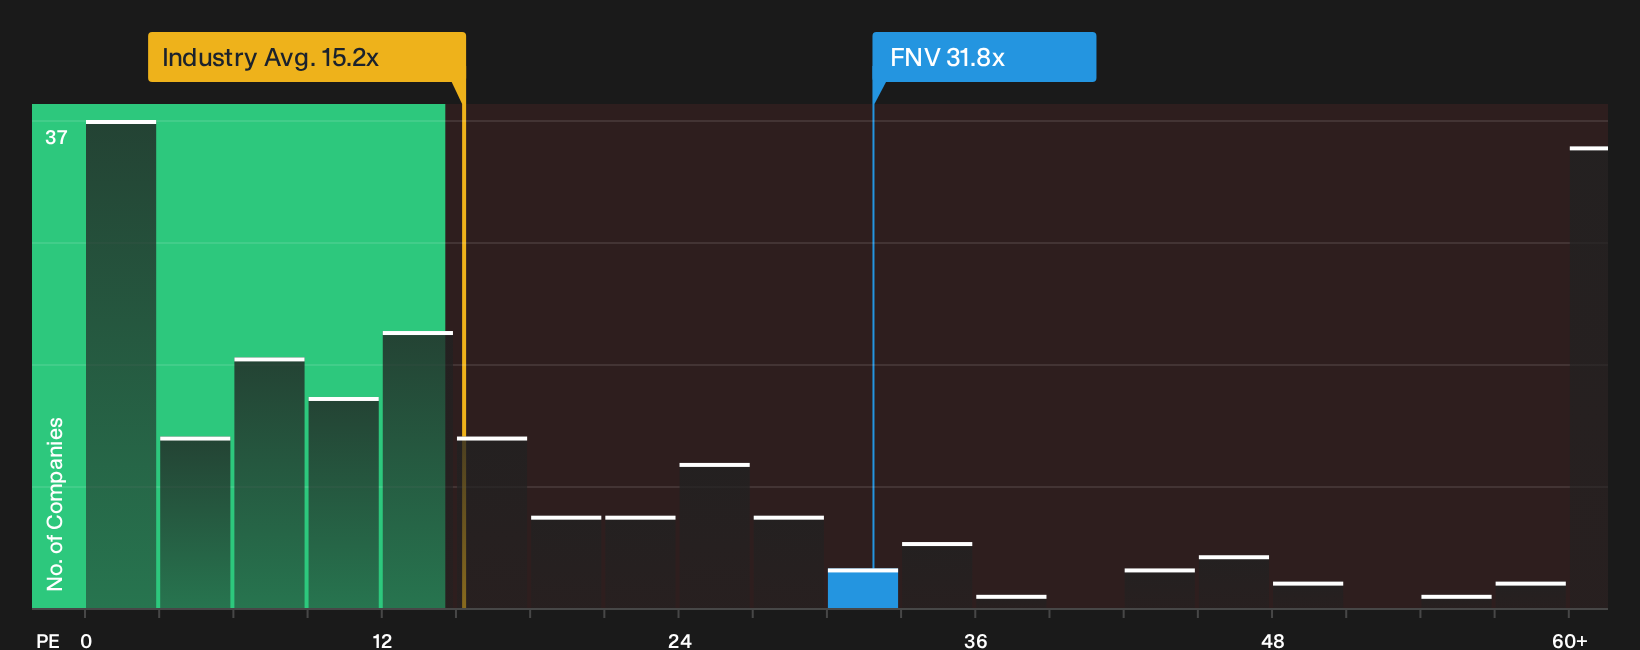
On P/E, the stock trades at 31.8x compared with about 15.6x for peers and 15.2x for the wider Canadian metals and mining group, while the fair ratio sits at 18.4x. That gap implies investors are already paying a hefty premium for quality and growth. The question is whether you are comfortable underwriting that premium if expectations slip.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feel the bullish tilt in the Franco-Nevada debate and want your own take before sentiment shifts again? Move quickly, examine the drivers in detail, and weigh both risks and rewards for yourself with the 3 key rewards.
Looking For More Investment Ideas Beyond Franco-Nevada?
If Franco-Nevada has sharpened your interest, do not stop here. Broaden your watchlist today so you are not catching up after the next move.
- Target resilient balance sheets and fundamentals by scanning a list of solid balance sheet and fundamentals (8 results) that can handle tougher conditions without forcing rushed decisions.
- Hunt for quality at a discount by running the 5 high quality undervalued stocks before prices shift and the better entries close off.
- Spot early-stage opportunities with real potential using the 19 elite penny stocks with strong financials before they find wider attention and pricing becomes less forgiving.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com