
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Tetra Tech (TTEK) Pulls Back As Water And Federal Work Support Fair Value Case
Tetra Tech (TTEK) drew fresh attention after a recent pullback left the shares down about 3% over the past month, even though the previous three months showed a gain of more than 11%.
At around US$34.72 per share, Tetra Tech has seen short term momentum cool, with a 30 day share price return of about 2.7% in decline. However, the 90 day share price return of 11% and 1 year total shareholder return of roughly 7% still point to steadier underlying sentiment.
Scan beyond Tetra Tech and spot other consulting and infrastructure stocks with similar momentum shifts using the hand-picked 33 high quality undervalued stocks list.
Recent gains set one story, the pullback tells another. For Tetra Tech at about US$34.72, does it make more sense to commit now or wait for a cheaper entry based on today’s valuation?
Most Popular Narrative: 14% Undervalued
Tetra Tech’s most followed valuation story puts fair value at about $40.33 per share, compared with the recent close near $34.72. That gap anchors the thesis that the recent pullback has not erased what this narrative sees as a pricing discount.
Increased global spending on water infrastructure programs, including the roughly £105b U.K. AMP8 cycle and Ireland’s planned €11.8b water investments, together with double digit municipal water treatment growth in the U.S., points to a long pipeline of projects where Tetra Tech can convert existing contract capacity into future net revenue and earnings.
Expanding defense and federal infrastructure work, supported by new multi year awards with agencies such as the U.S. Army Corps of Engineers, the FAA, NOAA, and the EPA, gives Tetra Tech more contracted scope that can flow through backlog into future net revenue and earnings as task orders are executed.
See why 16 investors see Tetra Tech as 14% undervalued.
Result: Fair Value of $40.33 (UNDERVALUED)
Still, the Tetra Tech story faces pressure if the USAID and State Department work is not replaced and if weakness in renewables continues to drag on commercial revenue.
Find out about the key risks to this Tetra Tech narrative.
Another View: Tetra Tech Through The P/E Lens
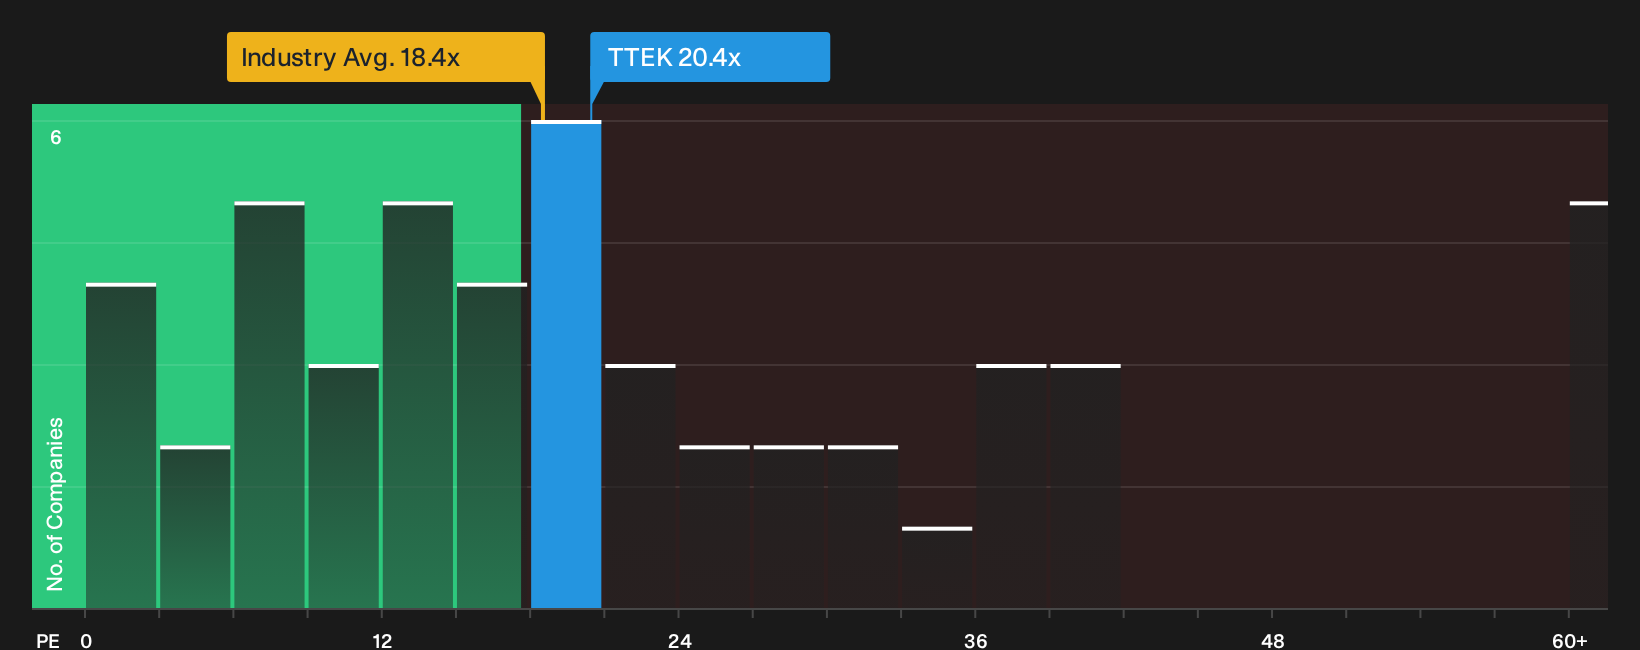
The SWS DCF model points to Tetra Tech trading at a discount to an estimated fair value of $46.26, yet the picture looks less generous when using earnings multiples. At a P/E of 20.4x, the stock trades richer than the US Commercial Services sector on 18.4x and above its own fair ratio of 16.9x, which suggests less margin for error if growth or margins soften.
For a closer look at what this earnings multiple gap might imply for upside and downside scenarios, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mixed tone of this Tetra Tech story leaves plenty of room for your own judgment, so move fast, review the numbers in detail, then weigh the 3 key rewards
Looking for more Tetra Tech style investment ideas?
If you stop only at Tetra Tech, you risk missing other opportunities that fit your goals just as well or even better across sectors and styles.
- Target resilient compounders with strong downside protection by scanning our 32 resilient stocks with low risk scores, which is designed for investors who care about durability as much as upside.
- Hunt for quality at a discount by using the curated 33 high quality undervalued stocks, a tool that filters for solid fundamentals and potential mispricing.
- Spot future leaders early by running through the focused 20 high quality undiscovered gems, where fundamentals matter more than headline attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com