
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Walmart Stock And Other Inflation Resistant Consumer Staples Picks
Inflation is back in the spotlight, Fed rate hikes are back on the table, and suddenly the stocks that looked comfortable last year feel less certain. When borrowing costs rise and budgets tighten, pricing power and steady demand start to matter a lot more. This article walks through three Consumer Staples and Discount Retailers screener stocks that look closely tied to this new backdrop, and explains why their exposure to the latest inflation shock could either help or hurt a portfolio.
The three examples covered next are just a small slice of the idea, and the full screen turned up 21 more Consumer Staples and Discount Retailers that carry similarly interesting stories and risk profiles.
If you want to identify which tickers best match your own risk tolerance and income goals, head into the Consumer Staples and Discount Retailers screener to filter, analyze, and focus on the highest conviction plays for your watchlist.
Coles Group (ASX:COL)
Coles Group gives this screener direct exposure to Australian grocery and household essentials, with most revenue from supermarkets that tend to see relatively steady demand when inflation pushes shoppers toward value and everyday staples.
Coles Group runs Australian supermarkets, liquor stores, online grocery and delivery services, plus loyalty and financial products, anchored firmly in everyday essentials. Supermarkets generated about A$41.5b of revenue, liquor about A$3.5b, and other activities A$0.6b, and the business carries a market cap near A$32.0b.
For a Consumer Staples and Discount Retailers theme, Coles Group brings something simple but powerful: a large footprint in food and basics that households keep buying even when higher rates and rising prices squeeze other spending. This is why one operational upgrade now matters so much.
"The completed rollout and ramp-up of Coles' automated distribution centres (ADCs) and customer fulfilment centres (CFCs) are now expected to drive material improvements in supply chain efficiency, product availability, and cost-to-serve."
Everything from future pricing power to earnings resilience could hinge on how one less visible cost pressure behaves over the next few years.
Those cost pressures are only one part of the story, and the full narrative for Coles Group maps how Coles Group could translate supply chain efficiency into pricing power, stronger cash flow, and improved competitive resilience.

Walmart (WMT)
Walmart sits right in the sweet spot of this Consumer Staples and Discount Retailers theme, with a large presence in low priced groceries, essentials, and club formats. These offerings tend to attract budget conscious shoppers when inflation and higher rates lead households to stretch every dollar.
Walmart operates global supercenters, supermarkets, ecommerce sites, and Sam's Club warehouses focused on everyday essentials. Walmart U.S. generates about US$495.3b of revenue, Walmart International about US$141.4b, Sam's Club about US$99.1b, and the business is valued around US$942.6b.
"Rapid growth in Walmart Connect, with margins of about 70% and profits described as purely incremental to the core retail operation, can further lift consolidated net margins as advertising becomes a larger share of earnings."
What really determines how Walmart converts that defensive traffic into long term earnings power is how one still maturing profit pool scales from here.
That hinge point on future earnings is exactly what the full narrative for Walmart unpacks. It shows how advertising, membership and scale could be quietly accelerating Walmart's profit engine.

Loblaw Companies (TSX:L)
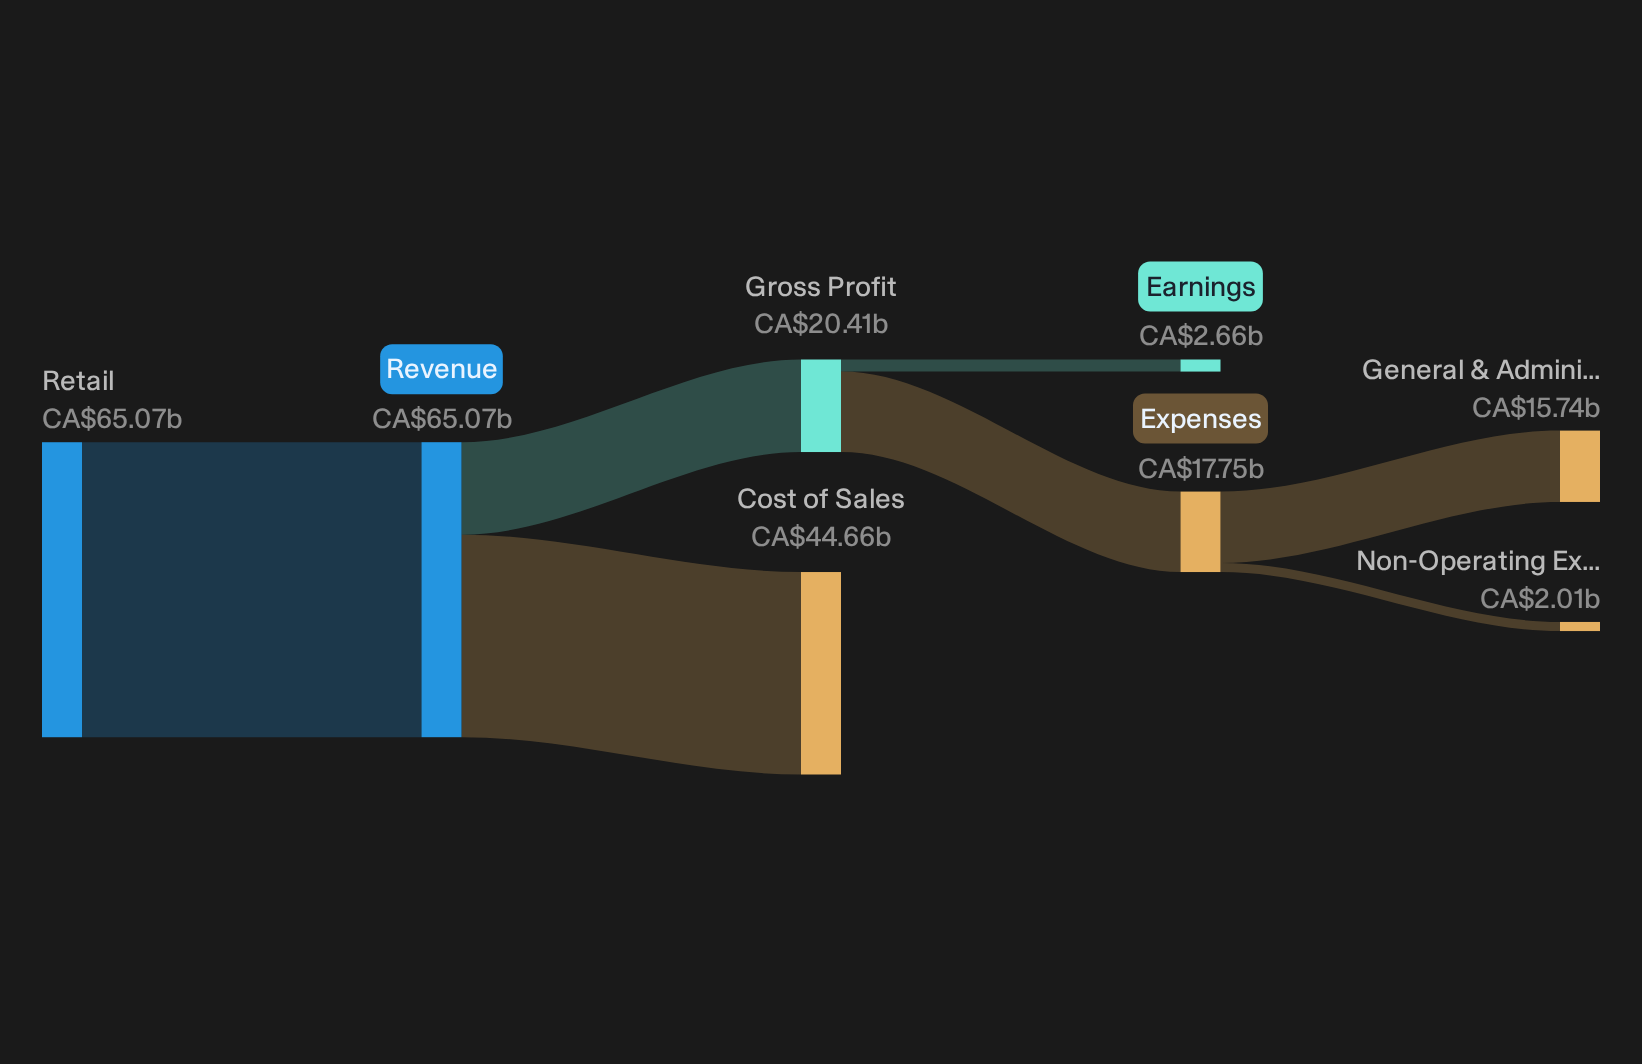
Loblaw Companies ties neatly into the Consumer Staples and Discount Retailers theme through its mix of value focused grocery chains and essential pharmacy outlets, with about CA$65.1b of Retail revenue in Canada and a market value around CA$80.6b supporting its role as a large domestic anchor.
Loblaw Companies is accelerating new store openings to roughly 75 locations in 2026, with about half in food and mostly hard discount formats and half in Shoppers Drug Mart, which extends its reach into value oriented small boxes and additional pharmacy sites.
What really matters for investors is how one less visible driver ultimately shapes pricing power and margin resilience if inflation pressure lingers.
If that quiet driver matters to you, read the full narrative for Loblaw Companies to see how Loblaw Companies could turn discount expansion into lasting pricing power and cash flow strength.
Seeking Alternatives Before The Crowd
Fresh opportunities move first. Breakout stories build momentum, laggards keep dropping, and quiet winners fly under the radar for now. Check the next wave of ideas and consider your options promptly.
- Spot cash rich operators with room to move by scanning the curated list of solid balance sheet and fundamentals (12 results). This can help you focus on companies where balance sheet quality may still be overlooked.
- Explore structural tailwinds in power demand by checking the hand picked 42 power grid technology and infrastructure stocks before this grid upgrade theme becomes widely recognized.
- Track robotics demand as automation spreads by reviewing the focused 91 robotics and automation stocks and identify potential beneficiaries before that theme attracts broader attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com