
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Coty (COTY) Faces Turnaround Questions, Is The Stock Expensive?
Investor scrutiny of Coty (COTY) intensified after recent like for like sales declines raised questions about possible market share losses, even as beauty markets expanded, putting the turnaround plan and cash flow potential under closer review.
Recent trading has been volatile for Coty. The 30 day share price return of 31.69% and 90 day gain of 18.52% suggest short term momentum has picked up, yet the 1 year total shareholder return is still down 26.27%. This keeps longer term holders under pressure and adds extra weight to the current debate about whether the recent like for like sales softness signals a deeper reset in expectations or a temporary bump in its turnaround story.
Scan how Coty’s recent swings compare with a curated set of 33 high quality undervalued stocks that pair stronger balance sheets with cash flows the market may be underpricing.
Coty’s brands and R&D push give it a clear presence in beauty, yet the share price rebound after steep multi year losses sets up a tougher test. Does the current valuation fairly reflect that mix?
Most Popular Narrative: 21% Overvalued
Coty last closed at $3.20, while the most followed valuation storyline puts fair value at $2.65, so the share price already sits above that narrative anchor and leans on a lot going right in execution.
The focus on premiumization within Coty’s Prestige division, supported by owned and long duration licenses and plans to offset the Gucci Beauty exit through amplified launches and new licenses such as Swarovski and Etro, is set up to influence future revenue mix and adjusted EBITDA margins.
The Coty.Curated and Color the Future programs, which include cutting around 20% of Consumer Beauty SKUs and concentrating on fewer, larger launches, are intended to lift shelf productivity and lower obsolescence and could support gross margin and segment EBITDA over time.
See why 9 investors see Coty as 21% overvalued.
Result: Fair Value of $2.65 (OVERVALUED)
Still, Coty’s recent like for like sales declines while beauty categories grew, and the planned Gucci Beauty exit, both sit uncomfortably against that richer valuation story.
Find out about the key risks to this Coty narrative.
Another View on Coty’s Valuation
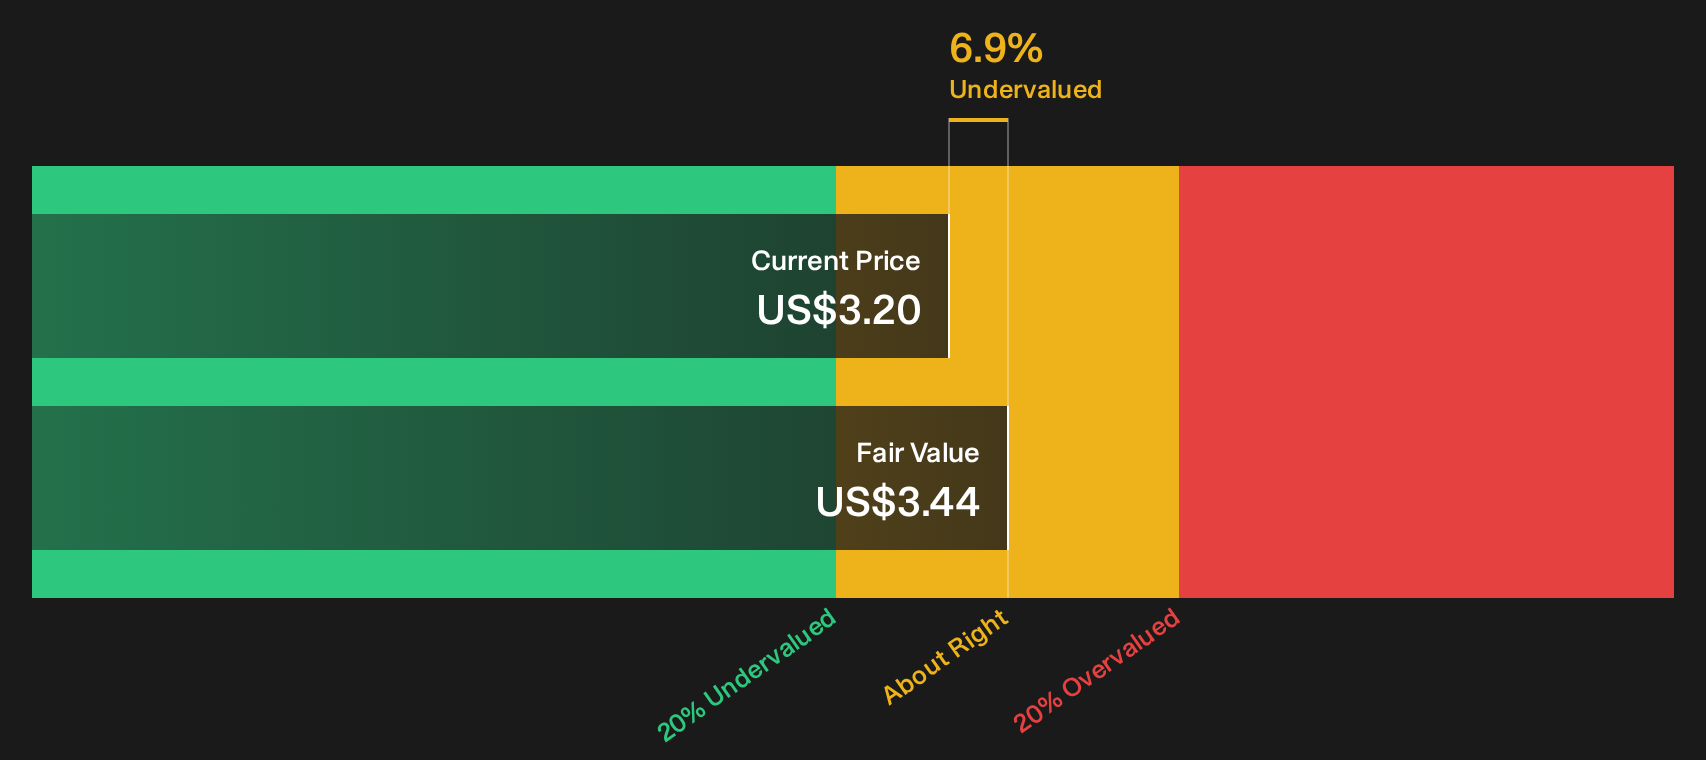
The analyst narrative tags Coty as 21% overvalued at $3.20 versus a fair value anchor of $2.65. Our DCF model points in a different direction. It estimates future cash flows support a value of $3.44, which puts the current quote about 6.9% below that mark.
This type of gap between a DCF outcome and a narrative driven target often reflects how much weight investors place on near term sales softness compared with longer term margin repair. Which lens do you consider more useful for evaluating Coty at this point.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this Coty story feels finely balanced between risk and potential, review the data promptly and test the narratives yourself. To understand that upside more clearly, check the 3 key rewards
Looking for more investment ideas beyond Coty?
If Coty has sharpened your focus on valuation, you can apply that momentum to your wider watchlist and bring fresh ideas onto your radar quickly.
Use the Simply Wall St Screener to identify new opportunities that fit your style before the broader market pays attention.
- Target quality at a discount by scanning a curated set of 33 high quality undervalued stocks that combine solid fundamentals with prices the market may be underestimating.
- Prioritize resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that can help cushion your portfolio when conditions are challenging.
- Spot potential early movers by checking a focused group of 14 elite penny stocks with strong financials where strong financial traits align with lower share prices.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com