
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
China State Construction International Holdings (SEHK:3311) Has Investors Asking A Bigger Question
Fresh valuation work on China State Construction International Holdings (SEHK:3311) has attracted attention, indicating that its discounted cash flow estimate is significantly higher than the current share price. The analysis links this valuation gap to projected free cash flow growth.
Recent trading in China State Construction International Holdings has been mixed, with the share price at HK$8.725 posting an 11.57% 90-day share price return while still showing a year to date share price decline of 5.68%. Over a longer window, the total shareholder return of 45.94% across five years, alongside a 6.92% 30-day share price return, suggests sentiment has been rebuilding. This frames the current discounted cash flow valuation gap as part of a broader story of recovering momentum after a weaker 1-year total shareholder return of 6.20%.
Scan a curated field of potential cash flow mispricings alongside China State Construction International Holdings by reviewing the 191 high quality undervalued stocks that currently screen as trading below their assessed value.
Bulls point to China State Construction International Holdings trading well below some cash flow estimates, while bears focus on the weaker 1 year return. Which story do the current valuation numbers lean toward?
Preferred P/E of 5.1x: Is it justified for China State Construction International Holdings?
On simple earnings terms, China State Construction International Holdings trades on a P/E of 5.1x, which screens as inexpensive when set beside both its own fair value markers and sector peers. At the last close of HK$8.725, that multiple aligns with an SWS DCF estimate that places fair value at HK$15.60, indicating the share price is well below the future cash flow estimate.
The P/E ratio compares the current share price to earnings per share and effectively shows how much investors are willing to pay for each unit of profit. For a construction and infrastructure contractor like China State Construction International Holdings, this metric often reflects how dependable investors think those earnings are, given project cycles, funding structures, and execution risk.
Here, the 5.1x P/E is well below the Hong Kong Construction industry average of 12.6x. This points to a steep discount relative to peers. It also sits under an estimated fair P/E of 8.1x for the stock, suggesting that if sentiment moved closer to that level, the pricing gap could narrow meaningfully.
Explore the SWS fair ratio for China State Construction International Holdings.
Result: Price-to-earnings of 5.1x (UNDERVALUED)
Still, the falling 1 year total return and the gap to the HK$10.96 price target leave room for sentiment to sour if project economics or cash flows disappoint.
Find out about the key risks to this China State Construction International Holdings narrative.
Another view on China State Construction International Holdings valuation
Price based metrics paint China State Construction International Holdings as inexpensive, yet the SWS DCF model goes further. It values the shares at HK$15.60 compared with the HK$8.725 market price, which points to a deep discount. If both measures lean the same way, where might the market be misreading the story?
Look into how the SWS DCF model arrives at its fair value.
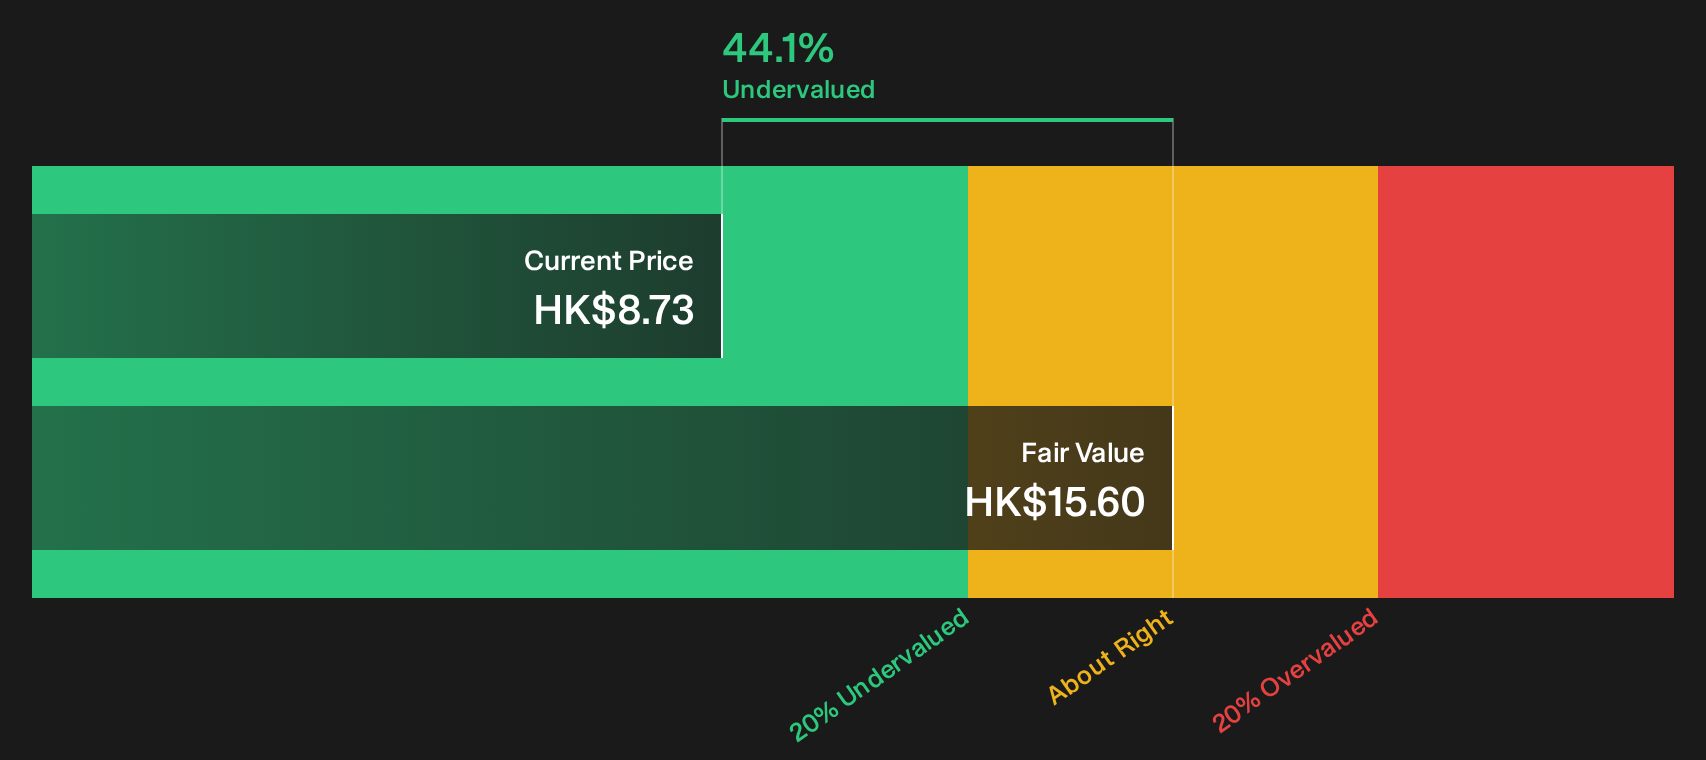
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China State Construction International Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on China State Construction International Holdings can either unsettle you or prompt a closer look at the underlying drivers of that valuation gap. If you want to weigh those cross currents yourself, review the 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond China State Construction International Holdings?
Do not stop with China State Construction International Holdings when plenty of other candidates might fit your style, goals, and preferred balance of risk and stability.
- Chase potential mispricing by scanning the 191 high quality undervalued stocks that combine compressed valuations with stronger fundamentals than the market seems to be pricing in.
- Strengthen your downside protection by filtering for a list of solid balance sheet and fundamentals (204 results) that can better handle tough conditions and financing shocks.
- Hunt for under-followed opportunities by reviewing a carefully built pool of 614 high quality undiscovered gems before other investors start paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com