
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Caledonia Mining (CMCL) Could Be 52% Undervalued Following Blanket Guidance Cut
Production reset at Blanket mine
Caledonia Mining (CMCL) has cut 2026 production guidance for its Blanket mine and released weaker third quarter output figures, putting fresh focus on how the Zimbabwe gold producer is running its core asset.
Recent trading reflects that reset in expectations. Caledonia Mining’s share price is around US$23.54 and, despite a strong 90 day share price return of 40.2%, the stock is still down 10.6% year to date with a 1 year total shareholder return that has declined 29.35%. The 3 year and 5 year total shareholder returns of 125.1% and 119.37% show how sentiment has swung over different timeframes as investors reassess both growth potential and risk after production updates and earlier project news.
Scan how Caledonia Mining compares with other gold producers under pressure by reviewing the hand-picked 36 elite gold producer stocks in this space.
After a sharp 90 day rebound but with production guidance trimmed for 2026, Caledonia Mining now sits in an awkward middle ground. Does that combination already sit in the price, or is patience on entry still worth something?
Most Popular Narrative: 52% Undervalued
Against a last close of $23.54, the most followed narrative on Caledonia Mining points to a fair value of $49.43, framing the recent production reset against a much higher implied worth.
Caledonia Mining Corporation (NYSE: CMCL) currently trades near $24.00 with a market capitalization of roughly $480 million, presenting a stark divergence between its robust cash generation and its politically discounted equity valuation. With FY 2025 revenue surging 46% to $267.7 million, EBITDA reaching $125.3 million, and a transition to a net cash position of $23.8 million, the fundamental baseline is mispriced relative to global peers.
See why 4 investors see Caledonia Mining as 52% undervalued.
According to Genious_Trades, that gap sits on a simple comparison. The narrative fair value of $49.43 is more than double where Caledonia Mining currently trades, implying a 52.4% discount driven largely by how investors treat Zimbabwe risk.
The argument leans heavily on two pillars. Blanket, which generated most of group revenue, is treated as a cash engine. Bilboes and other projects are assigned material optionality that the narrative claims is not being reflected in the current share price.
That story cuts both ways for readers. On one side, the analyst price target of $43.88 is 86.4% above the last close and is based on estimates that sit within a tight range of agreement. On the other, the SWS DCF model points to a future cash flow value of $7.17 per share, which is well below the present $23.54 quote and suggests a very different read on long term cash generation.
Even away from those models, a few data points help frame the debate. Revenue of $271.76m and net income of $64.79m translate into a 23.8% profit margin, which is higher than last year’s 18.3% margin. Over the past five years, earnings growth of 33.4% per year and an even faster 73.1% jump in the latest year feed into a 25.2% return on equity, flagged as high by SWS metrics.
The board and management backdrop adds some context for how that capital is being overseen. Directors show an average tenure of 3.8 years with 89% independence and what SWS describes as an appropriate mix of new and seasoned members. Management tenure averages 4.2 years, which clears the internal bar for experience, and CEO total compensation of $907,190 sits below the $2.47m median for similar sized US companies.
Income focused readers may also care about the cash return. Caledonia Mining pays a 2.38% dividend that SWS describes as reliable, while earnings, although forecast to grow slower than the wider US market, are still expected to increase 16% per year with revenue projected to rise 23.8% annually, faster than the 13.2% forecast for the broader US market.
Even with those positives, risk flags are not absent. All funding is described as coming from higher risk external borrowing rather than customer deposits, and the narrative itself highlights Zimbabwe specific regulatory and currency questions as key drivers of the equity discount that quantitative models and SOTP work are trying to interpret.
Putting those threads together, you are left with three reference points that do not agree. The narrative fair value at $49.43 points to deep undervaluation, the analyst target at $43.88 sketches a smaller gap, and the SWS DCF estimate at $7.17 challenges both by implying the current quote prices in more generous future cash flows than that model supports.
Result: Fair Value of $49.43 (UNDERVALUED)
Still, the whole Caledonia Mining narrative leans heavily on execution at Bilboes and on Zimbabwe-specific regulatory and currency risks staying contained.
Find out about the key risks to this Caledonia Mining narrative.
Another View: SWS DCF model points the other way
While the Genious_Trades narrative pins Caledonia Mining’s fair value at $49.43, the SWS DCF model lands at just $7.17 per share. That implies the current $23.54 price already reflects richer cash flows, which raises a simple question for readers: Which story feels more realistic?
Look into how the SWS DCF model arrives at its fair value.
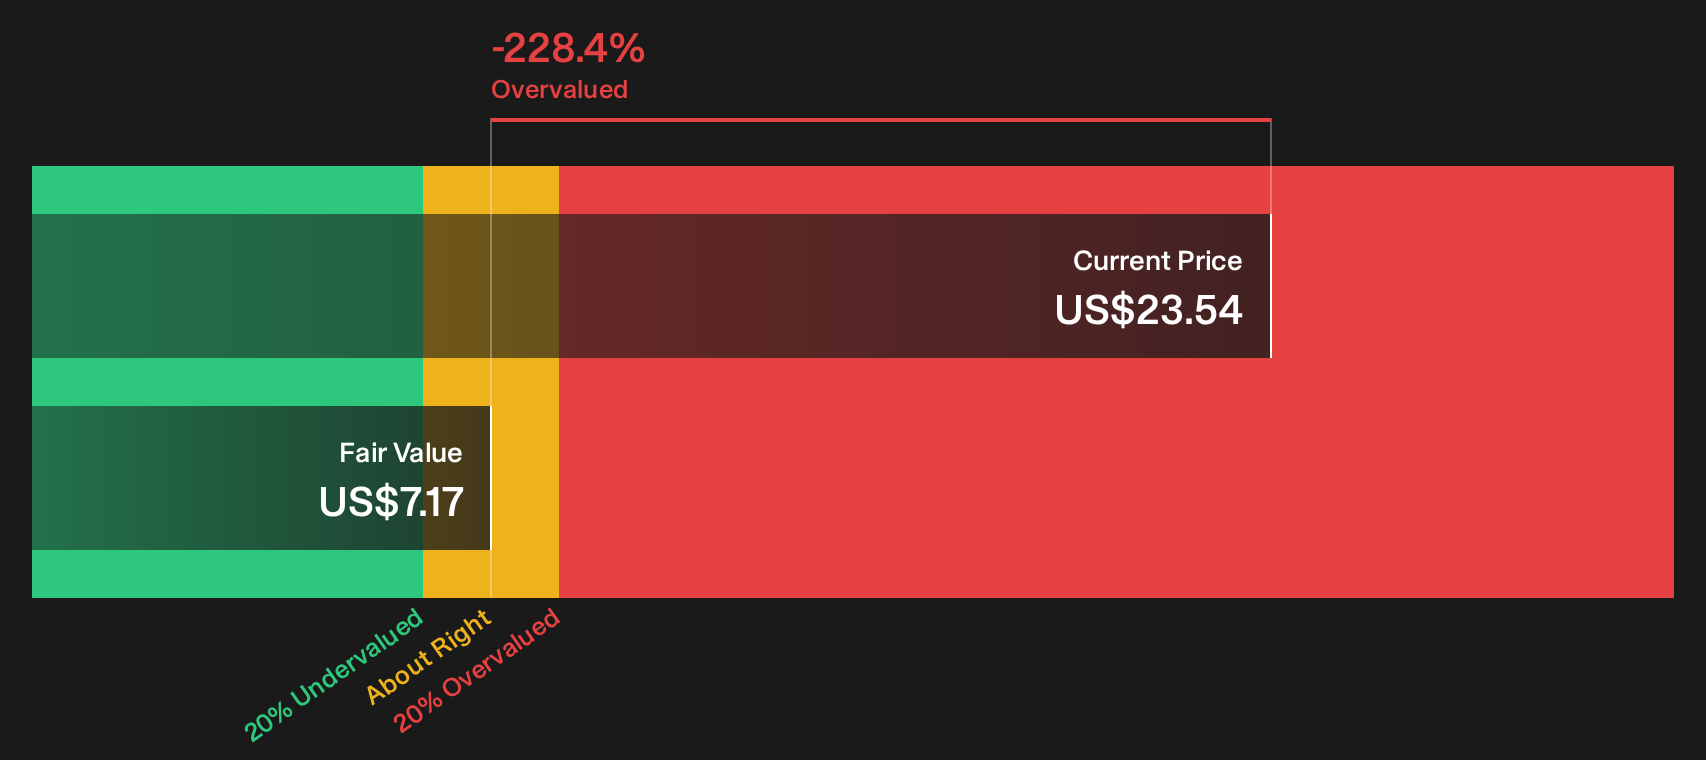
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Caledonia Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of caution and optimism around Caledonia Mining feels finely balanced, move fast on your own homework and pressure test the bullish angles by checking the 6 key rewards.
Looking for more Caledonia Mining style ideas?
If Caledonia Mining has sharpened your focus, keep that momentum and use clear rules, not hunches, to source your next watchlist candidates.
- Target potential mispricing by scanning a curated pool of quality companies that still look cheap on fundamentals with the 33 high quality undervalued stocks.
- Build a steadier income stream by filtering for consistent payers and higher yields using the 8 dividend fortresses.
- Sharpen your risk controls by focusing on businesses that pair solid finances with fewer red flags through the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com